AI
The End of the Demo Era: VivaTech Turns 10 and Demands Utility

Inside the sprawling halls of Paris’s Porte de Versailles, the atmosphere at the tenth anniversary of Europe’s premier technology gathering feels remarkably sober. The flashing holograms and robotic dogs of previous years have been quietly pushed to the periphery. Instead, the defining VivaTech AI trends centre on something far less cinematic: immediate, measurable commercial utility. Ten years since its inception, the conference has outgrown its adolescent fascination with what technology could do. Now, European founders and international investors are betting everything on artificial intelligence that actually works on the factory floor, in the back office, and across the supply chain.
This shift at VivaTech mirrors a broader correction across the global technology sector. The initial speculative frenzy surrounding generative models has collided with the harsh realities of corporate budgets and data privacy constraints. We have officially entered the deployment phase. Executives no longer want to pay for experimental software that hallucinates legal precedents or hallucinates customer service responses. They demand secure, ring-fenced tools that drive margin expansion.
The numbers reflect this systemic maturation. According to recent data synthesized by the Organisation for Economic Co-operation and Development (OECD), enterprise adoption of applied AI models is projected to drive a 1.4% annual increase in labour productivity across the Eurozone by 2027. Yet, the same dataset reveals a glaring friction point: only 18% of mid-sized firms have successfully integrated these models beyond pilot programs.
The gap between pilot and production is where the money is now being made. European venture capital has adjusted its focus accordingly. According to the Financial Times, funding for pure-play foundation model startups dropped by 22% in the first quarter of 2026, while capital allocated to vertical-specific AI applications surged. Investors are no longer funding the picks and shovels; they are funding the extraction.
Walking the convention floor this May, the changing guard is impossible to ignore. Startup booths are stripping the phrase Large Language Models (LLMs) from their primary marketing copy. The pitches have transformed. Founders are no longer selling the intelligence of their neural networks; they are selling automated invoice reconciliation, predictive supply chain routing, and immediate cost reduction.
Arthur Mensch, CEO of Paris-based Mistral AI, summarised this shift during a closed-door briefing on Tuesday. He noted that enterprise clients have abandoned open-ended experimentation in favour of strict, highly defined use cases. This pragmatism is fundamentally reshaping the European tech ecosystem. The continent, long criticised for failing to produce consumer internet giants, is leaning heavily into its traditional strengths: industrial engineering, regulatory compliance, and complex B2B software.
The capital backing these ventures is equally pragmatic. The French state investment bank, Bpifrance, announced a €500 million facility specifically earmarked for enterprise AI adoption within legacy manufacturing firms. This is not speculative capital. It is modernisation infrastructure. By targeting established industries, European policymakers are attempting to engineer an economic transition rather than merely chasing Silicon Valley’s consumer-focused tail.
That said, selling applied intelligence requires an entirely different sales motion. Startups must now prove integration capabilities with legacy SAP and Oracle databases. They have to navigate complex procurement cycles. The romantic era of the overnight AI unicorn is dead. We are now in the era of the gruelling enterprise sales cycle, where security audits matter more than parameter counts.
This transition toward utility is not happening in a vacuum. It is being heavily engineered by Brussels. The enforcement of the European AI Act has fundamentally altered the structural economics of software development on the continent. Critics initially warned that the legislation would stifle innovation, but the reality on the ground at VivaTech suggests a different outcome. Regulation has inadvertently created a massive market for compliance-grade, sovereign AI solutions.
What are the main AI trends at VivaTech?
At VivaTech, the primary AI trends centre on applied artificial intelligence, strict regulatory compliance under the EU AI Act, and enterprise-grade deployment. Companies are actively abandoning generative novelty in favour of measurable productivity gains, secure sovereign data solutions, and demonstrable return on investment.
This compliance-first approach offers a distinct competitive moat. American tech giants are currently battling copyright infringement lawsuits and regulatory scrutiny regarding their data scraping methodologies. European startups, conversely, are building models explicitly trained on licensed, opt-in data. They are offering guarantees that foreign competitors cannot match. When a German automotive manufacturer integrates a predictive maintenance model, they require absolute certainty that their proprietary telematics data will not be used to train a public model.
The picture is more complicated than a simple trans-Atlantic rivalry. It is a divergence in product philosophy. The US model prioritises general intelligence and rapid consumer adoption. The emerging European model, showcased vividly across the VivaTech pavilions, prioritises domain-specific accuracy, data sovereignty, and legal safety. In the enterprise sector, safety is rapidly becoming a premium feature rather than a bureaucratic burden.
The downstream consequences of this shift are profound for both policymakers and small-to-medium enterprises (SMEs). For the latter, the barriers to entry are finally lowering. For the last three years, AI deployment was effectively restricted to multinational corporations with vast engineering resources. The current generation of applied tools, heavily promoted at VivaTech, operates as plug-and-play software.
This democratization of capability will aggressively disrupt traditional B2B service sectors. Legal research, entry-level accounting, and supply chain logistics are facing immediate margin compression. According to a recent analysis by Bloomberg Intelligence, professional services firms that fail to adopt automated workflows will see their operating margins contract by up to 15% over the next 24 months. The cost of remaining analogue is becoming fatal.
Still, this transition requires massive infrastructure. The bottleneck has shifted from software capability to physical compute. Sovereign data solutions demand localized data centres. European nations are currently scrambling to build the requisite energy and cooling infrastructure to support this localized compute demand. The next major geopolitical battleground will not be the algorithms themselves, but the raw gigawatts required to run them domestically.
Governments are acutely aware of this vulnerability. French President Emmanuel Macron used his opening address at the conference to announce accelerated permitting processes for green-energy data centres. The goal is clear: to ensure that the intellectual property generated by European applied AI remains physically housed within the borders of the European Union.
Competing Perspectives: The Compute Deficit and Market Fragmentation
Not everyone in the halls of Porte de Versailles shares this optimistic vision of a European industrial renaissance. A vocal contingent of investors argues that the continent’s focus on applied AI is essentially a concession of defeat in the foundational model race. The bear case is structural and compelling.
Europe remains fragmented. A startup cannot scale across the continent without navigating 27 different legal jurisdictions and language barriers. More critically, the hardware deficit is severe. According to Reuters technology analysts, Europe currently accounts for less than 12% of the global advanced GPU supply. You cannot build a sovereign AI ecosystem if you rely entirely on Californian hardware manufactured in Taiwan.
Dissenting voices argue that by focusing purely on B2B applications, European firms risk becoming entirely dependent on the foundational API layers controlled by OpenAI, Google, and Anthropic. If the base cost of inference rises, the profit margins of these European applied AI companies will collapse. In this view, the regulatory moat created by the AI Act is a temporary illusion, easily breached once the foundational models reach a threshold of undeniable superiority.
Yet, the counter-argument remains potent. Foundational models are rapidly commoditising. Open-source alternatives are narrowing the performance gap weekly. If intelligence becomes a cheap, ubiquitous utility, the real economic value will accrue to the companies that own the proprietary workflow integrations and the industry-specific data.
Ten years on, VivaTech has shed its adolescent idealism. The focus on artificial intelligence that practically functions within the rigid constraints of modern business represents a necessary maturation. Europe is no longer attempting to clone Silicon Valley. It is building an ecosystem tailored to its own industrial and regulatory DNA.
The tension between foundational dependence and applied utility will define the next decade of enterprise technology. However, the mood in Paris suggests a quiet confidence that the pendulum is swinging back toward business fundamentals. The era of the speculative demo has officially concluded; the era of ruthless execution has begun.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


AI
PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand
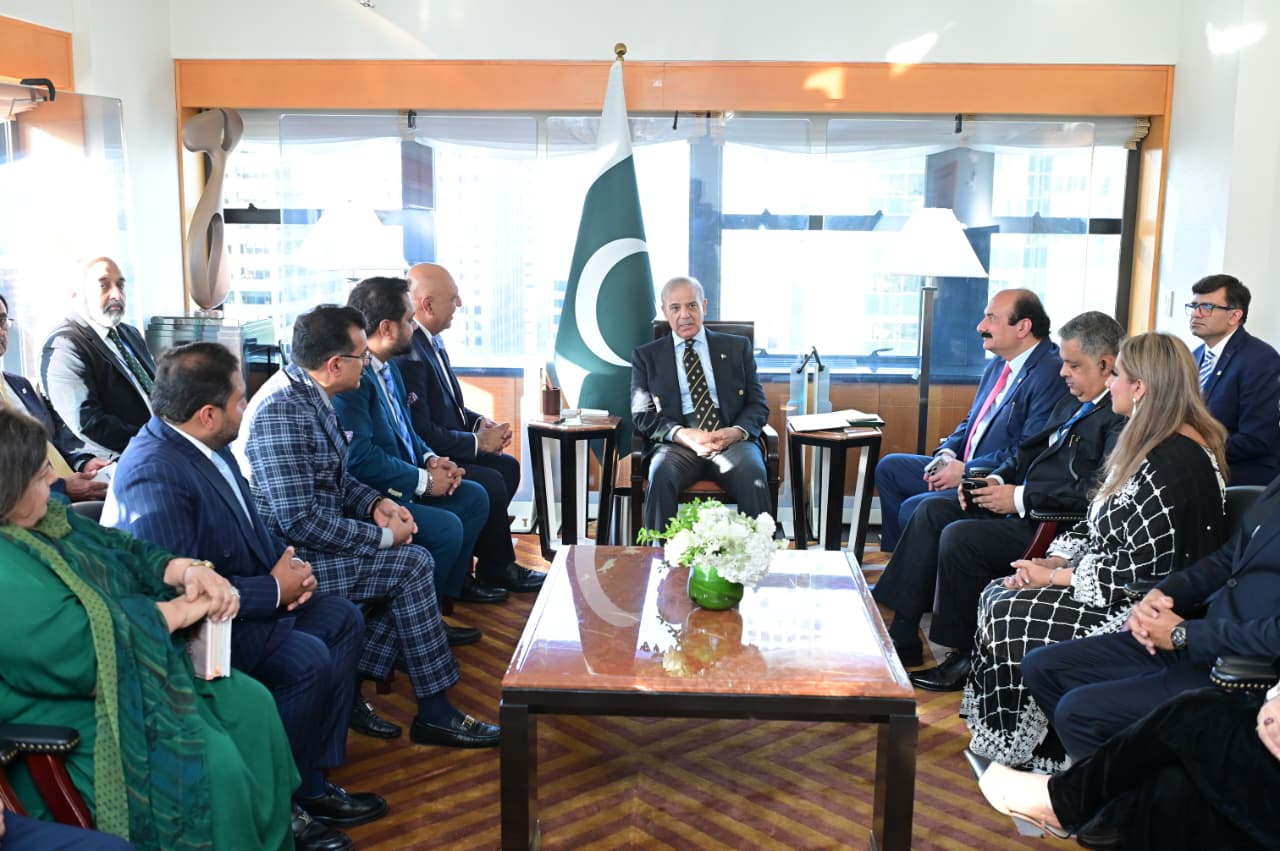
NEW YORK, September 24, 2026 — Prime Minister Muhammad Shehbaz Sharif has invited Pakistani business leaders and professionals based in the United States to invest in Pakistan, highlighting government measures aimed at improving the business environment and encouraging investment.
The invitation came during meetings with Pakistani-American business personalities and professionals working across information technology, artificial intelligence, automobiles, energy, construction and other sectors.
According to the Associated Press of Pakistan (APP), the prime minister said the government was working to create a conducive environment for investment and business activity. He also pointed to reforms at the Federal Board of Revenue (FBR) and measures intended to promote innovation in agriculture.
But the latest appeal to the Pakistani-American business community comes against a broader backdrop: Pakistan is seeking to attract more private investment, expand exports and turn improving macroeconomic conditions into sustained economic activity.
Why Pakistani-American Investors Are Being Targeted
The Pakistani diaspora represents an important source of capital, business expertise and international commercial connections.
Pakistan’s remittance flows demonstrate the economic significance of its overseas population. World Bank data show that Pakistan received approximately $40.48 billion in personal remittances in 2025, equivalent to around 9.9% of GDP.
The State Bank of Pakistan also reported workers’ remittances of approximately $3.66 billion in August 2026, with the monthly series showing substantial inflows throughout 2026.
Investment, however, differs from remittances: it involves deploying capital into businesses, projects or financial assets with the expectation of returns. That distinction makes the government’s effort to attract diaspora entrepreneurs particularly relevant.
IT and AI Among the Sectors in Focus
The technology sector is one of the most significant areas highlighted by the government.
The September 24 meeting included Pakistani-American professionals associated with IT and artificial intelligence, alongside representatives from traditional sectors such as automobiles, energy and construction.
Pakistan’s broader investment framework identifies services, including IT and telecommunications, as areas open to foreign investment. The Board of Investment says Pakistan maintains a liberal investment regime and has mechanisms designed to facilitate local and foreign investors.
For Pakistani-American technology entrepreneurs, potential areas include:
- Software and SaaS businesses
- Artificial intelligence
- IT-enabled services
- Fintech
- Digital infrastructure
- Business-process outsourcing
- Export-oriented technology companies
- Technology startups and venture investment
The attraction for diaspora entrepreneurs is not necessarily limited to providing capital. Entrepreneurs with operations in the United States can potentially bring technology, management expertise, international customers, investment networks and access to global markets.
Agriculture Is Another Priority
Agriculture was also specifically mentioned during the prime minister’s meetings.
APP reported that Shehbaz Sharif said the government was taking measures to promote innovation in agriculture.
That creates potential investment themes around:
- Agri-processing
- Agricultural technology
- Cold-chain infrastructure
- Food processing
- Irrigation technology
- Storage and logistics
- Export-oriented agriculture
- Livestock and dairy
- Farm mechanization
For investors, the distinction between producing agricultural commodities and investing in higher-value processing and supply-chain infrastructure can be particularly important because value-added businesses can connect domestic production with international markets.
What Pakistan’s Investment Framework Offers Foreign Investors
Pakistan’s Board of Investment states that the country follows a liberal investment regime and that its mandate includes promoting, encouraging and facilitating both local and foreign investment.
The Board’s investment information also states that foreign investors can have 100% equity ownership in many areas, although restrictions or specific rules apply to certain sectors.
The government’s Investment Policy 2023 also emphasizes investor protection, investment promotion and expanding Pakistan’s investment-promotion presence abroad, including in the United States.
That policy framework provides important context for the prime minister’s latest appeal to Pakistani-American businesses.
Pakistan Has Also Introduced a New Long-Term Residency Route for Investors
Another development relevant to international investors is Pakistan’s Long-Term Residency (LTR) framework.
According to the Board of Investment, the Foreigners (Long Term Residency) Order, 2025 created a residency-by-investment framework offering five-, seven- and ten-year residency options, subject to eligibility and investment requirements. The BOI says the minimum investment requirement is $50,000, to be materialized within one year through authorized banking channels.
The scheme is separate from the government’s broader investment-promotion policies, but it illustrates the effort to create additional mechanisms for attracting international capital and entrepreneurs.
The U.S.-Pakistan Economic Relationship Adds Another Layer
The appeal to Pakistani-American businesses also comes while economic engagement between Pakistan and the United States remains an important part of Pakistan’s external economic strategy.
In July 2026, Reuters reported that Pakistan had requested a proposed $10 billion U.S. exchange stabilization facility, while discussions were also taking place with U.S. financial institutions including the Export-Import Bank and the U.S. International Development Finance Corporation.
More recently, Reuters reported that Pakistan expected a decision from the United States on the proposed facility while continuing discussions with U.S. EXIM Bank and the Development Finance Corporation on potential projects.
These developments concern government-to-government and institutional financing rather than Pakistani-American private investment, but together they illustrate the wider economic relationship in which the latest business-community outreach is taking place.
What the Government Says About Investment Facilitation
Pakistan’s Board of Investment describes itself as the interface between international and domestic investors and the public and private sectors. Its investment regime information highlights measures intended to reduce the cost and procedural burden of doing business and to facilitate investment.
The government has also continued promoting the Special Investment Facilitation Council and other mechanisms intended to streamline investment processes.
For an investor considering Pakistan, however, the existence of an investment framework does not remove the need for sector-specific due diligence, regulatory approvals, taxation analysis, foreign-exchange considerations and commercial risk assessment.
What Pakistani-American Investors Should Examine Before Investing
The prime minister’s invitation is a political and economic call for greater investment, but prospective investors still need to evaluate individual opportunities on their own merits.
Key issues include:
1. Regulatory requirements
Investment rules differ according to the sector. The BOI notes that some industries are subject to specific restrictions or approvals.
2. Ownership structure
Foreign ownership can reach 100% in many sectors, but exceptions exist, making a sector-specific review necessary before establishing a company.
3. Profit and capital repatriation
Pakistan’s investment framework provides mechanisms for foreign investors to repatriate eligible profits, dividends and investment proceeds, subject to applicable foreign-exchange procedures.
4. Taxation
Investors should examine federal and provincial taxes, withholding obligations, customs duties and sector-specific incentives before committing capital.
5. Infrastructure and operating costs
An attractive investment proposition depends not only on headline incentives but also on electricity, logistics, labor, financing, connectivity and supply-chain costs.
6. Exit strategy
Investors should establish how capital can be repatriated, shares transferred and profits distributed before entering the market.
Pakistan’s Investment Push Extends Beyond the United States
The latest initiative is part of a wider effort to attract overseas Pakistani capital.
Earlier in September 2026, Economic Affairs Minister Ahad Cheema directed officials to develop a structured mechanism through which overseas Pakistanis could participate in viable infrastructure projects, including potential opportunities involving railways, highways, power, civic infrastructure and airports.
In July, Planning Minister Ahsan Iqbal also invited Pakistani-American entrepreneurs, technologists and financiers in Chicago to bring capital, expertise and global networks to Pakistan’s economic development.
This indicates that the September 24 appeal is not an isolated announcement but part of a broader government effort to engage overseas Pakistanis and international investors.
The Bigger Question: Can Investment Follow the Outreach?
The government’s challenge is to convert investment invitations into bankable projects and completed investments.
That requires more than announcements. Investors typically assess regulatory predictability, taxation, currency convertibility, infrastructure, security, financing costs, market size, contract enforcement and the ability to repatriate returns.
The U.S. State Department’s investment-climate assessment has previously identified challenges in Pakistan including regulatory complexity, intellectual-property concerns, changing taxation policies and security-related investor concerns. At the same time, it noted that U.S. companies operate profitably in several Pakistani sectors and that there are no restrictions specifically targeting U.S. investors.
That combination—investment opportunity alongside identifiable investment risks—is important context when assessing the latest government outreach.
What Comes Next for Pakistani-American Investment
Prime Minister Shehbaz Sharif’s September 24 appeal places Pakistani-American businesses at the center of Pakistan’s effort to attract additional investment.
The sectors discussed—AI, IT, energy, automobiles, construction and agriculture—cover both emerging technologies and established parts of the economy.
Pakistan’s investment framework, expanding diaspora-focused initiatives and continuing U.S.-Pakistan economic engagement could provide additional channels for investment. However, the eventual impact will depend on whether proposed opportunities develop into commercially viable projects and whether investors find the regulatory and economic environment sufficiently predictable.
For Pakistani-American entrepreneurs, the latest message from Islamabad is therefore straightforward: the government wants greater diaspora participation not only through remittances, but also through entrepreneurship, capital, technology and long-term investment.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
WASHINGTON — Newly disclosed federal financial records show that investment accounts belonging to President Donald Trump underwent an aggressive portfolio restructuring in July 2026, logging 1,156 individual securities transactions valued between $79 million and $270 million.
While headline attention has focused on multi-million-dollar sales of artificial intelligence and mega-cap tech leaders—including Microsoft, Amazon, and Meta Platforms—a comprehensive examination of the filings reveals a more complex strategy: a transition driven by automated index rebalancing, defensive fixed-income allocation, and concurrent dip-buying.
Executive Overview: July 2026 Disclosure Breakdown
According to analysis of official filings submitted to the U.S. Office of Government Ethics and reported by CNBC, total purchases across the eight managed accounts exceeded total sales.
| Category | Aggregate Value Range | Key Assets / Companies Involved |
| Total July Transactions | $79 Million – $270 Million | 1,156 total trades logged across 8 accounts |
| Total Purchases | $43.6 Million Minimum | Municipal bonds, short-term ETFs, Broadcom, Nvidia |
| Total Sales | $35.6 Million Minimum | Microsoft, Amazon, Oracle, Meta, Northrop Grumman |
| Primary Liquidation Event | July 20, 2026 | Multi-million dollar trims in $MSFT and$AMZN ($5M–$25M bracket each) |
| Quick Re-Entry Trades | July 23, 2026 | Modest buybacks in $MSFT ($100K–$250K) and$AMZN ($1K–$15K) |
Dissecting the Big Tech Trims: Algorithmic Rebalancing vs. Market Sentiment
The largest individual entries in the September filing occurred on July 20, 2026, when investment managers executed broad sell-offs in major cloud and AI infrastructure vendors.
As reported by Quartz, individual sell orders for Microsoft and Amazon each landed in the $5 million to $25 million filing bracket. Simultaneously, managers offloaded between $1 million and $5 million in Oracle stock, alongside position trims in Meta Platforms, Alphabet, and Nvidia.
However, reporting focused exclusively on liquidations misses the broader picture:
- Simultaneous Accumulation: On the very day managers sold Oracle, they added $500,000 to $1 million in Nvidia, while opening $1 million to $5 million positions in enterprise software giants like Salesforce, Intuit, and Marvell Technology.
- Immediate Re-entry: Just three days after the July 20 sell-off, the accounts repurchased positions in Microsoft ($100,001–$250,000 range) and Amazon ($1,001–$15,000 range).
- Fixed-Income Pivot: Significant capital was rotated into defensive yield assets, including the Vanguard Short-Term Bond Index ETF, State Street SPDR Bloomberg International Treasury Bond ETF, and local government bonds such as Miami-Dade County aviation paper.
Financial analysts noted in coverage by Livemint that these multi-directional trades mirror index-tracking models adjusting for market weightings rather than a deliberate directional bet on the tech sector.
White House Clarification: Automated Model Portfolios
Trading volume of this scale by a sitting U.S. president inevitably draws regulatory and public scrutiny. Addressing the disclosures, White House spokesperson Davis Ingle emphasized that the President maintains no personal involvement in daily trade execution.
“The President’s investment portfolio is managed by independent third-party financial institutions through automated model portfolios benchmarked to broad indices like the Schwab 1000,” White House officials stated. “Trading decisions are algorithmically executed without input, direction, or prior knowledge from the President or his family.”
Unlike past presidential administrations that placed assets into blind trusts or single-index mutual funds, the current arrangement relies on third-party wealth managers utilizing direct indexing models.
Regulatory Scrutiny and Geopolitical Overlap
Despite White House assurances, the timing of specific trades has drawn criticism from Capitol Hill.
On July 20, the same day managers sold $250,000 to $500,000 worth of defense contractor Northrop Grumman, President Trump signed an executive order tightening supply chain mandates for defense suppliers and restricting critical material sourcing from foreign nations.
According to government oversight documents cited by Bloomberg, congressional lawmakers—including Senator Elizabeth Warren—have submitted formal inquiries demanding full transparency regarding the identity of the third-party money managers overseeing the accounts to rule out insider conflicts of interest under U.S. Securities and Exchange Commission rules.
Key Takeaways for Market Observers
- Net Buyer Status: Despite headline sales in Big Tech, Trump’s accounts were overall net buyers in July, adding at least $43.6 million in assets.
- Broad Sector Diversification: Capital moved away from concentrated cloud computing mega-caps into short-duration fixed income, municipal bonds, and specialized semiconductor stocks.
- Systemic Model Management: The rapid buy-sell cycles (such as selling and repurchasing Microsoft within 72 hours) strongly align with algorithmic portfolio rebalancing rather than strategic macroeconomic forecasting.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

The iPhone 18 Pro transitions to TSMC’s 2nm process node, integrating a titanium-alloy chassis with advanced graphene vapor chambers. This solves thermal throttling for AAA gaming and AI rendering. However, these material upgrades push the bill of materials higher, indicating an impending increase in Average Selling Price and altering enterprise fleet procurement strategies.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know

How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)

CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]

IPhone 18 Pro Specifications, Pricing, and Thermal Architecture Leaks Analyzed

Pre-IPO Investing Strategies: How Institutional Money is Approaching Anthropic

Smash Bros Ultimate 13.0.5 Patch Notes: What Actually Changed
How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)
IPhone 18 Pro Specifications, Pricing, and Thermal Architecture Leaks Analyzed
Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
Pre-IPO Investing Strategies: How Institutional Money is Approaching Anthropic
CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]
Smash Bros Ultimate 13.0.5 Patch Notes: What Actually Changed
NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support
World School Summit 2026 Malaysia: 41st Edition
PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand
Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings
-
Digital5 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital5 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China5 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools