Analysis
ETFs Are Eating the World: AI Jitters and Oil’s Reversal

ETFs are reshaping markets as AI hype drives volatility and oil reversals hit energy. A political‑economy view of risk, power, and flows.
ETFs are “eating the world” because low‑cost indexing has pulled vast amounts of capital into a small set of benchmarks, concentrating ownership and flows. AI‑fueled swings intensify crowding in tech, while oil’s reversal exposes how passive portfolios can lag real‑economy shifts and geopolitics.
Key Takeaways
- ETFs made investing cheaper and easier—but they also concentrate flows, power, and price discovery in a handful of indexes and providers.
- AI‑driven enthusiasm creates crowding risk inside passive vehicles, amplifying both rallies and selloffs.
- Oil’s reversal shows the blind spot of broad indexing: real‑economy shocks can move faster than passive portfolios.
- Regulators see the plumbing risks, but policy still lags the market reality.
- Investors need to understand the political economy of indexing, not just its fees.
The Hook: A Market Built for Speed, Not Reflection
Picture a day when the market opens with a jolt: an AI‑themed mega‑cap sells off on a single earnings comment, energy stocks surge on an OPEC headline, and most retail portfolios barely blink—because the flows are pre‑programmed. That’s the new normal. ETFs have turned markets into a high‑speed logistics network where money moves with incredible efficiency, but not always with great wisdom.
This is the core paradox: ETFs are eating the world, yet the world they’re eating is becoming more concentrated, more narrative‑driven, and more sensitive to macro shocks. The political economy angle matters here—because when capital becomes more passive, power becomes more centralized.
1) ETFs Are Eating the World—And It’s Not Just About Fees
ETFs won because they made investing easy: low costs, intraday liquidity, diversification in one click. The U.S. SEC’s ETF rulemaking in 2019 standardized and accelerated ETF growth by making it easier to launch and operate funds, effectively industrializing the format’s expansion (SEC Rule 6c‑11). Add zero‑commission trading and mobile brokerages, and the ETF wrapper became the market’s default delivery system.
But the bigger story is market structure. When indexing dominates, the market stops being a collection of independent price judgments and starts behaving like an ecosystem of shared pipes. The evidence is in decades of data on active manager underperformance: the persistence of indexing’s edge has been documented by S&P Dow Jones Indices’ SPIVA reports, which track active‑vs‑index outcomes across asset classes and regions (SPIVA Scorecards). As more capital goes passive, the marginal price setter becomes thinner.

The Power Shift You Don’t See in Your Brokerage App
Every ETF is a wrapper around an index. That means index providers and mega‑asset managers now sit at the center of capital allocation. Methodology choices—what gets included, what gets excluded, how often rebalanced—are no longer small technical details; they are de facto policy decisions. Index providers publish their methodologies and governance processes, but their influence has outgrown their public visibility (S&P Dow Jones Indices Methodology, MSCI Index Methodology Hub).
The political economy question is straightforward: who governs the gatekeepers? When a handful of index decisions can redirect billions overnight, “neutral” becomes a powerful political claim—one that deserves scrutiny.
2) Market Plumbing: When the Wrapper Becomes the Market
ETF liquidity is often secondary‑market liquidity—trading of ETF shares between investors. But the primary market (where new shares are created or redeemed via authorized participants) is what keeps the ETF aligned with its underlying holdings. This is sophisticated plumbing that works beautifully—until it doesn’t.
Regulators have flagged the risks of liquidity mismatch and stress dynamics in market‑based finance. The IMF’s Global Financial Stability Reports have repeatedly examined how investment funds can amplify shocks through redemptions and market depth constraints (IMF Global Financial Stability Report). The BIS Quarterly Review has also analyzed how ETFs can transmit stress across markets when liquidity in underlying assets dries up (BIS Quarterly Review).
This doesn’t mean ETFs are fragile by default. It means ETF stability is conditional—on underlying liquidity, dealer balance sheets, and the health of market‑making infrastructure. That’s a systemic issue, not an investor‑education footnote.
3) AI Jitters: Narrative Crowding Meets Passive Plumbing
AI is a genuine technological shift—but the market’s response has a familiar shape: concentration, hype cycles, and correlation spikes.
As AI narratives accelerate, money tends to flow into the same handful of mega‑cap names and thematic ETFs. That can create a feedback loop: flows drive prices, prices validate the narrative, and the narrative attracts more flows. Research institutions and regulators have emphasized how valuation sensitivity and concentrated exposures can heighten market vulnerability, especially when expectations outrun fundamentals (Federal Reserve Financial Stability Report).
The irony? Passive investing is supposed to diversify risk. But when the market’s capitalization itself is concentrated, indexing becomes a lever that amplifies concentration. Index providers track and publish concentration metrics, but the shift is structural: if the index is top‑heavy, the index fund is top‑heavy.
Morningstar’s fund flow research highlights how investor demand often clusters in the same categories at the same time—precisely the behavior that can exacerbate crowding in narrative‑driven sectors (Morningstar Fund Flows Research). In an AI‑fueled cycle, this means the same ETF wrapper that democratized access can also democratize risk.
4) Oil’s Reversal: The Old Economy Bites Back
While AI dominates headlines, oil reminds us that real‑world supply and geopolitics still run the table. When oil reverses—whether due to OPEC decisions, demand surprises, or geopolitical shocks—sector weights and macro assumptions change faster than broad passive portfolios can adapt.
The most credible real‑time oil data comes from institutions that track physical balances and policy developments. The International Energy Agency’s Oil Market Report, the U.S. EIA’s Short‑Term Energy Outlook, and OPEC’s Monthly Oil Market Report provide the market’s core macro narrative (IEA Oil Market Report, EIA Short‑Term Energy Outlook, OPEC MOMR).
Now connect that to ETFs: broad‑market indexes rebalance slowly, while sector ETFs can swing on a dime. If oil’s reversal signals a structural shift—say, prolonged supply constraints or a geopolitical premium—passive portfolios are late to the party by design. In the meantime, ESG‑tilted portfolios may under‑ or over‑expose investors to energy at precisely the wrong time, a tension widely discussed in responsible‑investment circles (UN‑supported PRI).
Oil’s reversal isn’t just a commodity story. It’s a governance and allocation story—about how passive capital interacts with geopolitics, energy policy, and the physical economy.
5) The Political Economy of Passive Power
ETFs feel apolitical because they’re built on formulas. But formulas are choices, and choices accumulate power. When a few providers and index committees control the rules, the market’s “neutrality” becomes a governance issue.
Concentration of Ownership and Voting
Large asset managers now represent substantial voting power across public companies—a fact regulators and policy analysts have debated extensively. The SEC’s resources on proxy voting and fund stewardship underscore the governance significance of fund voting policies (SEC Proxy Voting Spotlight). The OECD’s corporate governance work also highlights how ownership structures influence accountability and long‑term capital allocation (OECD Corporate Governance).
The result is a paradox: indexing reduces fees, but concentrates influence. That influence is often exercised behind closed doors via stewardship teams, policy statements, and index inclusion decisions.
Regulatory Lag
Central banks and financial authorities increasingly focus on market‑based finance and nonbank intermediation. Yet ETF‑specific regulation still looks incremental compared with the speed of market evolution. The IMF and BIS acknowledge these dynamics, but the policy response remains cautious—partly because ETFs have also delivered undeniable investor benefits (IMF GFSR, BIS Annual Economic Report).
In short: we have system‑level dependence on a structure whose governance remains diffuse.
6) What This Means for Investors, Policymakers, and Markets
For long‑term investors
- Know what you own: broad ETFs are only as diversified as the underlying index. If the index is top‑heavy, your portfolio is too.
- Understand liquidity layers: ETF trading liquidity can mask underlying asset illiquidity during stress.
- Treat thematic ETFs as tactical: AI‑focused ETFs can be useful, but they behave like crowded trades, not balanced portfolios.
For policymakers
- Index governance deserves visibility: transparency in methodology changes, inclusion criteria, and stewardship votes matters.
- Stress‑test the plumbing: market‑making capacity and authorized participant resilience should be policy priorities.
- Don’t confuse access with resilience: ETFs democratize investing, but democratization can also democratize systemic risk.
For institutions
- Scenario‑test the narrative: what if AI expectations compress sharply? What if oil flips the inflation story?
- Use active risk where it matters: passive core can coexist with active hedges or sector rotations.
- Engage stewardship intentionally: if you own the market, you own its outcomes.
7) Three Scenarios to Watch
- Crowding unwind: AI‑exposed indexes and ETFs face synchronized selling, revealing liquidity gaps.
- Oil regime shift: a sustained energy price reversal reshapes inflation expectations and sector leadership, forcing passive reweighting.
- Regulatory recalibration: a policy move on ETF transparency or index governance changes the economics of passive flows.
None of these scenarios are destiny—but all are plausible.
Conclusion: Convenience Won. Power Concentrated.
ETFs didn’t just win on price—they won on architecture. They are the pipes through which modern capital flows. But when the pipes grow large enough, they shape the city.
AI jitters and oil’s reversal are not separate stories. They are stress tests for a market that now relies on passive plumbing to allocate active realities. The promise of ETFs was democratization; the risk is centralization without accountability.
The real question isn’t whether ETFs are “good” or “bad.” It’s whether we’re willing to govern the system they’ve become. Because in a world where ETFs are eating the world, the rules of the dinner table matter more than the menu.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


Analysis
Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
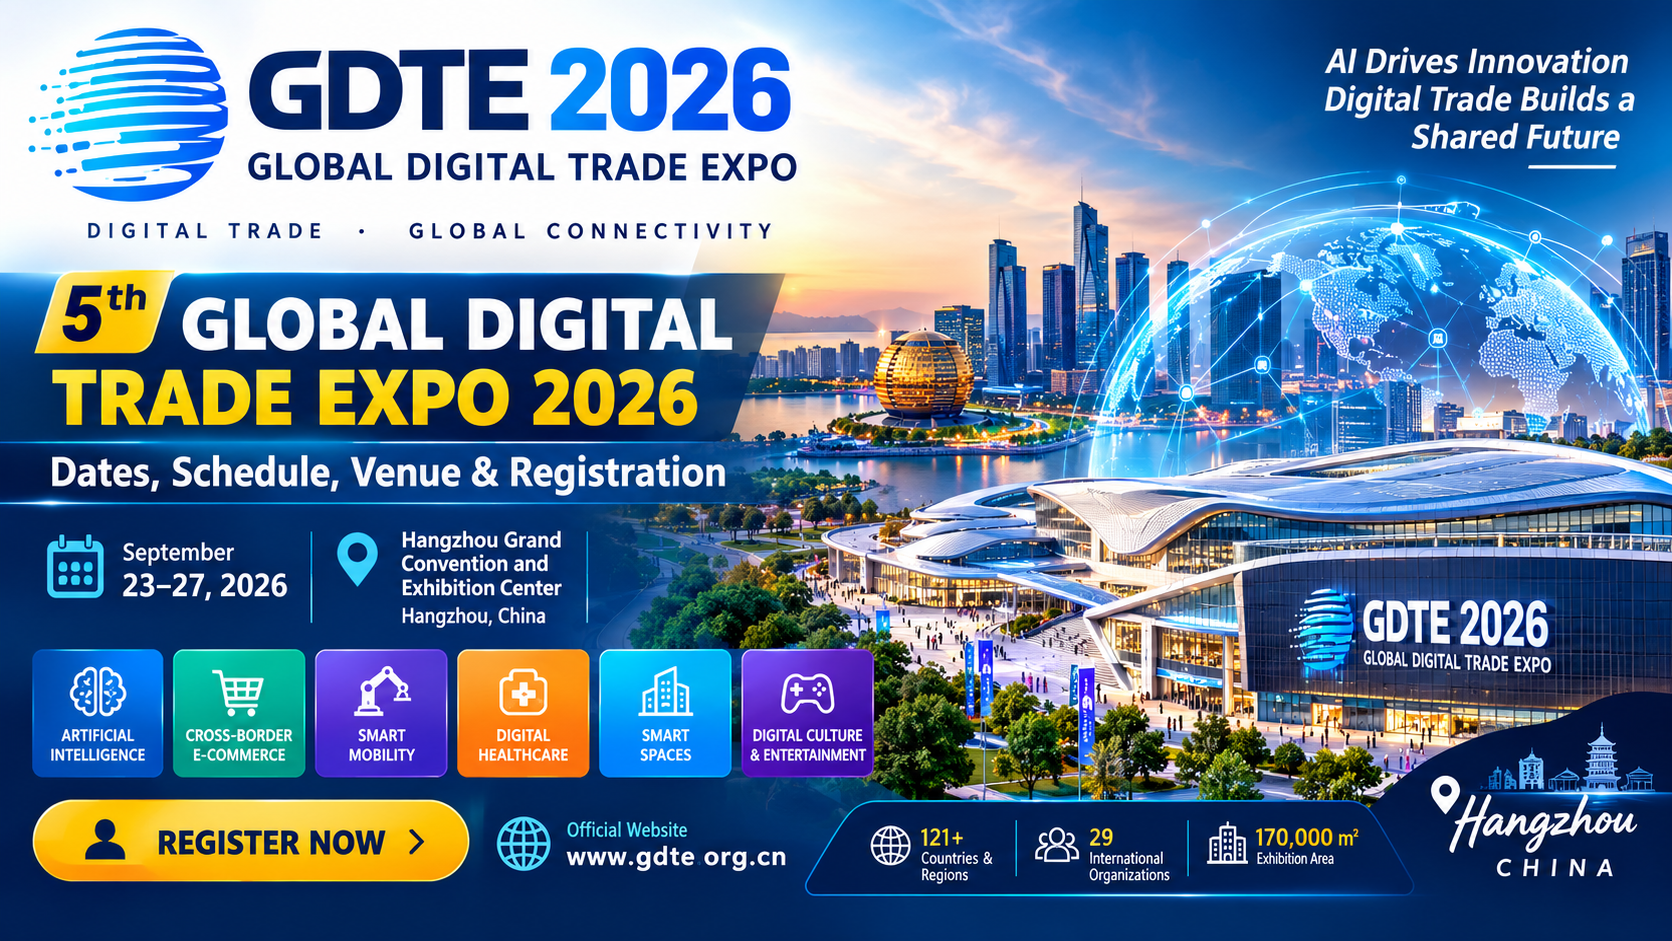
The Global Digital Trade Expo (GDTE) 2026 is set to bring together technology companies, digital-trade businesses, investors, policymakers, buyers and international organizations in Hangzhou, China, as artificial intelligence increasingly reshapes the global economy.
The 5th Global Digital Trade Expo will take place from September 23 to 27, 2026, at the Hangzhou Grand Convention and Exhibition Center in Zhejiang Province. The event will place particular emphasis on AI, digital trade, cross-border e-commerce and emerging technologies.
With representatives from 121 countries and regions and 29 international organizations confirmed to attend, GDTE 2026 is expected to be one of the year’s major international gatherings focused on digital trade and technology.
Global Digital Trade Expo 2026: Quick Details
| Event | Details |
|---|---|
| Event | 5th Global Digital Trade Expo (GDTE) |
| Dates | September 23-27, 2026 |
| Venue | Hangzhou Grand Convention and Exhibition Center |
| Location | Hangzhou, Zhejiang, China |
| Theme | Digital Trade, Global Connectivity |
| Main Focus | AI, digital trade, cross-border e-commerce, emerging technologies |
| Exhibition Area | About 170,000 square meters |
| International Participation | 121 countries and regions |
| International Organizations | 29 |
| Public Access | From 1:00 p.m. on September 24 |
| Official Website |
The expo is jointly hosted by the Ministry of Commerce of the People’s Republic of China and the People’s Government of Zhejiang Province, with Hangzhou and relevant commerce authorities serving as organizers.
When Is the Global Digital Trade Expo 2026?
The fifth GDTE is scheduled for:
September 23-27, 2026
The main exhibition will be held at the Hangzhou Grand Convention and Exhibition Center.
Public access is scheduled to begin at 1:00 p.m. on September 24, giving members of the public an opportunity to experience the technology demonstrations and interactive exhibitions.
GDTE 2026 Schedule at a Glance
September 23, 2026
Opening activities and professional/exhibition programming begin.
September 24, 2026
Public access begins from 1:00 p.m., with visitors able to explore exhibitions, technology demonstrations and interactive experiences.
September 25-26, 2026
The expo’s business, industry, investment and technology activities continue, including thematic forums, matchmaking and specialist events.
September 27, 2026
Final day of the fifth Global Digital Trade Expo.
Because individual forums and business-matching sessions may have separate schedules and registration requirements, visitors should check the official GDTE website before travelling.
What Is the Global Digital Trade Expo?
The Global Digital Trade Expo is China’s national-level international professional exhibition dedicated specifically to digital trade.
The event was created as a platform for displaying emerging digital technologies, products and business ecosystems while encouraging international cooperation, investment, technology exchange and trade.
Unlike a conventional technology exhibition, GDTE connects technology development with international commerce.
That makes the event particularly relevant to:
- Technology companies
- AI companies
- Software developers
- E-commerce businesses
- Exporters and importers
- Digital-service providers
- Fintech companies
- Investors
- Startups
- Government agencies
- Research institutions
- International buyers
- Trade associations
- Business delegations
AI Takes Center Stage at GDTE 2026
Artificial intelligence is expected to be one of the defining themes of this year’s expo.
More than one-third of exhibitors are expected to showcase AI-related products and technologies, highlighting the transition of AI from experimental technology toward practical commercial applications.
The exhibition will cover areas including:
- Artificial intelligence
- AI models
- Computing power
- Quantum technology
- Robotics
- Smart mobility
- Digital healthcare
- Cross-border e-commerce
- Digital entertainment
- Smart spaces
- Spatial intelligence
- Emerging digital services
The expo will also feature a new token globalization zone, focusing on the intersection of AI models, computing power and electricity.
Major Exhibition Zones
GDTE 2026 follows an expanded exhibition structure featuring a flagship digital-trade exhibition, specialized industry zones and an innovation-focused area.
1. Silk Road E-Commerce Zone
The Silk Road E-Commerce Zone will focus on cross-border digital commerce and international trade.
It is particularly relevant for businesses looking to expand internationally through digital platforms, AI-powered trade tools and e-commerce ecosystems.
Officials say nearly 30 AI tools for cross-border trade will be showcased in the zone.
2. Artificial Intelligence Zone
The AI zone will showcase developments involving:
- AI models
- Computing chips
- Quantum technologies
- AI applications
- Intelligent systems
3. Smart Mobility Zone
This section will highlight next-generation transportation technologies, including eVTOL aircraft and other advanced mobility solutions.
4. Digital Culture & Entertainment Zone
Digital media, XR, generative AI and entertainment technologies will be among the major themes.
The exhibition is expected to demonstrate how AI and immersive technologies are transforming entertainment and cultural industries.
5. Digital Healthcare Zone
This zone will highlight technologies such as:
- Surgical robots
- Exoskeletons
- Brain-computer interfaces
- AI-assisted healthcare
- Digital medicine
6. Smart Spaces Zone
The smart-spaces section will focus on areas such as:
- Smart cities
- Spatial intelligence
- Digital platforms
- Smart building management
- Low-carbon buildings
Global Business and Investment Opportunities
GDTE is not simply a technology showcase.
A major objective is to connect companies and international buyers with potential commercial, investment and technology partners.
The 2026 programme includes:
- 12 themed events
- 13 industry events
- Four investment and trade-promotion events
- 21 competitions and other frontier activities
Among the major events are expected to be the BRICS Special Economic Zones Hangzhou Dialogue, Silk Road E-Commerce Day and Digital Trade Africa Day.
The expo will also release the Global Digital Trade Development Report 2026 and China Digital Trade Development Report 2026. The United Nations is also expected to officially publish a global report during the event.
Who Should Attend GDTE 2026?
The event is especially relevant to professionals working in:
Technology
AI, cloud computing, software, robotics, quantum computing and emerging technology companies can use GDTE to identify potential partners and customers.
E-Commerce
Cross-border sellers, marketplaces, logistics providers and digital-payment companies can explore international business opportunities.
Finance and Fintech
Fintech companies and financial institutions can examine developments in digital payments, AI and digital financial services.
Startups
For startups, the expo can provide access to investors, technology partners, international buyers and potential distributors.
Investors
Investors can use the event to monitor emerging technology sectors and meet companies developing commercial applications of AI and other technologies.
Governments and Trade Organizations
Government agencies and trade-promotion organizations can explore new approaches to digital trade governance and international cooperation.
How to Register for Global Digital Trade Expo 2026
Registration requirements can vary depending on whether you are attending as a professional visitor, exhibitor, buyer, media representative or member of a business delegation.
The safest option is to begin through the official GDTE website:
The official website has historically provided professional-audience registration through its online channels.
Important Registration Advice
Before completing registration:
- Visit the official GDTE website.
- Select the appropriate visitor or professional registration option.
- Provide accurate personal and organizational information.
- Check whether your category requires registration review.
- Complete any identity or business verification requested.
- Save your confirmation or registration information.
- Check the final badge/entry instructions before travelling to Hangzhou.
For business delegations and specialized events, registration may be handled separately by participating organizations.
For example, the American Chamber of Commerce in Shanghai states that participation in its GDTE-related programme is subject to registration review and confirmation, while visitors seeking a GDTE badge may need to use the expo’s independent registration channel.
Is GDTE 2026 Free?
The exhibition itself is promoted as a professional event, but registration requirements can differ depending on the category of participation.
Some third-party event listings describe visitor admission as complimentary, while professional applications may be subject to review.
Visitors should therefore verify the latest admission and registration conditions directly through the official GDTE registration system rather than relying on third-party ticket websites.
Where Is the Global Digital Trade Expo Held?
The 2026 event will be held at:
Hangzhou Grand Convention and Exhibition Center
Hangzhou, Zhejiang Province, China
The venue is located in Hangzhou’s Xiaoshan District.
Hangzhou is particularly significant for GDTE because the city is one of China’s major technology and digital-commerce centers and has developed a strong ecosystem around e-commerce, fintech, cloud computing and artificial intelligence.
Why GDTE 2026 Matters for Global Digital Trade
The timing of the fifth GDTE is significant.
Digital trade is moving beyond conventional e-commerce. AI is increasingly influencing:
- Product discovery
- Digital advertising
- International payments
- Customer service
- Supply-chain management
- Trade documentation
- Translation
- Market research
- Business matching
- Logistics
- Cybersecurity
- Cross-border commerce
GDTE 2026 therefore provides a window into how these technologies could change the way companies conduct international business.
The event’s emphasis on AI also reflects a broader shift from simply demonstrating AI capabilities toward deploying AI in real commercial and industrial environments.
What Happened at the Previous GDTE?
The scale of GDTE has expanded considerably.
The fourth Global Digital Trade Expo in 2025 concluded with 102 major outcomes, while investment and trade-intent agreements reportedly reached 161.98 billion yuan, approximately US$22.7 billion at the reported exchange rate.
The 2026 edition is expected to build on that momentum with a larger exhibition footprint and broader international participation.
Global Digital Trade Expo 2026: Key Takeaways
For companies and professionals interested in international technology markets, the fifth GDTE offers several important opportunities:
For entrepreneurs: access to potential partners and customers.
For investors: exposure to emerging AI and digital-trade businesses.
For exporters: opportunities in cross-border e-commerce.
For technology companies: a platform to demonstrate products to international buyers.
For policymakers: discussions around digital-trade governance and international rules.
For researchers: access to emerging developments in AI, digital commerce and technology.
Final Word
The Global Digital Trade Expo 2026 is shaping up to be an important international event at the intersection of artificial intelligence, technology and global commerce.
Taking place in Hangzhou from September 23-27, 2026, the fifth edition will feature approximately 170,000 square meters of exhibition space, participation from 121 countries and regions, and representatives from 29 international organizations.
With AI expected to dominate the exhibition, the event will offer businesses and professionals an opportunity to see how emerging technologies are moving from laboratories and demonstrations into practical applications in international trade.
For prospective visitors, exhibitors and business delegates, the most important step is to verify the latest registration requirements directly through the official before making travel arrangements.
Event: 5th Global Digital Trade Expo
Dates: September 23-27, 2026
Venue: Hangzhou Grand Convention and Exhibition Center, Hangzhou, China
Focus: AI, digital trade, cross-border e-commerce and emerging technologies
Official Website:
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
Key Takeaways
- Sony has preliminarily agreed to a $7.85 million antitrust settlement in Caccuri v. Sony Interactive Entertainment, covering roughly 4.4 million eligible US PlayStation Network accounts.
- Individual payouts will range from an estimated $0.91 to $33.66 in PlayStation Store credit, depending on qualifying purchase history.
- No claim form is required — eligible accounts were identified automatically, and credit will be deposited directly into PSN wallets after final court approval.
- The final fairness hearing is scheduled for October 15, 2026 before Judge Araceli Martínez-Olguín in the US District Court for the Northern District of California.
- The case centers on Sony’s 2019 decision to stop allowing third-party retailers like Amazon, Best Buy, and GameStop to sell digital PlayStation game vouchers.
If you’ve bought digital games through the PlayStation Store over the past several years, you may be one of roughly 4.4 million account holders in line for a small but real payout from Sony. The settlement, formally titled Caccuri v. Sony Interactive Entertainment LLC, has received preliminary court approval and is headed toward a final fairness hearing on October 15, 2026. Here’s exactly what happened, who qualifies, and how much you can realistically expect.
What the Lawsuit Alleged
The case, filed in May 2021 in the US District Court for the Northern District of California by plaintiff Agustin Caccuri, alleges that Sony violated the Sherman Antitrust Act and the Clayton Act by monopolizing the market for digital PlayStation games. Before April 1, 2019, consumers could buy game-specific digital download vouchers from third-party retailers — Amazon, Best Buy, and GameStop among them — often at discounted prices that undercut Sony’s own PlayStation Store pricing.
On that date, Sony stopped allowing outside retailers to sell those vouchers. Plaintiffs argue this eliminated meaningful price competition, forcing consumers toward the PlayStation Store exclusively and, they contend, leading to higher digital game prices than would have existed in a competitive market. Specifically, eligible games are those where the post-discount PS Store price increased by at least 50 cents when comparing the period before April 1, 2019, to the period between April 1, 2019, and December 31, 2023.
Sony has not admitted wrongdoing. The company maintains it did not violate federal or state antitrust laws, and the court has not ruled on the underlying merits — this is a negotiated settlement, not a verdict.
A Rocky Road to Approval
This settlement wasn’t a straight line. An earlier version, originally announced in December 2024 and finalized in March 2025, was rejected by Judge Martínez-Olguín, who found it lacked clarity and didn’t meet Northern District of California guidelines for class-action settlement approval. Plaintiffs’ counsel were given 30 days to remedy the deficiencies, which led to the revised $7.85 million structure now headed to final approval.
Who Is Eligible
You may be eligible for compensation if you are a US-based PlayStation Network user who purchased one or more qualifying digital games through the PlayStation Store between April 1, 2019, and December 31, 2023, where:
- A game-specific voucher for that title was available at retail before April 1, 2019
- At least 200 game-specific voucher redemptions occurred prior to April 1, 2019
- The post-discount PS Store price rose by at least 50 cents in the post-2019 period compared to before
A full list of qualifying titles is available on the official settlement website. Crucially, eligible accounts were identified automatically through Sony’s own purchase records — there is no claim form to submit for most users.
How Much Will You Actually Get?
This is the detail generating the most online buzz — and the most misunderstanding. The $7.85 million headline figure is not what gets distributed to consumers. Under the settlement terms:
- Attorneys may request fees of up to 25% of the total ($7.85 million), plus expenses
- $30,000 in service awards go to the three named plaintiffs
- Administration costs are deducted before consumer distribution
After those deductions, roughly $5.89 million is expected to be spread across the identified pool of 4,407,533 accounts. Lead counsel Michael Buchanan has stated that individual recoveries should range from $0.91 to $33.66 in PlayStation Store credit, depending on the number and value of each account’s qualifying purchases.
| Settlement Component | Amount |
|---|---|
| Total settlement value | $7.85 million |
| Estimated attorneys’ fees (up to 25%) | ~$1.96 million |
| Named plaintiff service awards | $30,000 |
| Estimated remaining consumer pool | ~$5.89 million |
| Eligible accounts identified | ~4.4 million |
| Individual payout range | $0.91 – $33.66 |
How and When You’ll Get Paid
Compensation will be distributed automatically as PlayStation Network wallet credit — you do not need to file a claim. If your PSN account has since been deactivated, you can apply for a cash payment instead by contacting the settlement administrator directly.
Payment cannot occur until the court grants final approval at the October 15, 2026 fairness hearing. If approval is granted without a successful appeal, credits should follow in the weeks after. The opt-out deadline — for anyone who wants to preserve their right to sue Sony separately instead of accepting the settlement credit — has already passed as of July 2, 2026.
Why This Case Matters Beyond the Payout
Individual amounts here are modest — a few dollars in most cases — but the case sits within a broader pattern of antitrust scrutiny aimed at digital storefront monopolies across the tech industry. Google settled its own Play Store antitrust dispute with Epic Games in late 2025, and Apple has opened iOS to rival app stores in select markets under regulatory pressure. Sony’s settlement adds console gaming to that list, and comes at an awkward moment for the company: Sony recently announced plans to discontinue physical game production by 2028, a decision critics have already linked to this settlement as part of a broader “anti-consumer” narrative around digital game pricing and ownership.
Frequently Asked Questions
Do I need to file a claim to get PlayStation settlement money?
No. Eligible accounts were identified automatically based on Sony’s purchase records. If you qualify, credit will be deposited directly into your PSN wallet after final court approval — no claim form is required.
How much money will I actually receive from the Sony settlement?
Individual payouts are estimated to range from $0.91 to $33.66 in PlayStation Store credit, depending on how many qualifying digital games you purchased and their post-discount price increases.
When will the PlayStation settlement money be paid out?
Payment depends on final court approval at the fairness hearing scheduled for October 15, 2026, before Judge Araceli Martínez-Olguín. Credits are expected to follow in the weeks after approval, assuming no appeal is filed.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

The iPhone 18 Pro transitions to TSMC’s 2nm process node, integrating a titanium-alloy chassis with advanced graphene vapor chambers. This solves thermal throttling for AAA gaming and AI rendering. However, these material upgrades push the bill of materials higher, indicating an impending increase in Average Selling Price and altering enterprise fleet procurement strategies.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know

How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)

CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]

IPhone 18 Pro Specifications, Pricing, and Thermal Architecture Leaks Analyzed

Pre-IPO Investing Strategies: How Institutional Money is Approaching Anthropic

Smash Bros Ultimate 13.0.5 Patch Notes: What Actually Changed

NASA Cyberattack 2026: What the China Hack Means for Your Data Security

X (Twitter) Privacy Updates 2026 & The Best VPNs to Protect Your Data
IPhone 18 Pro Specifications, Pricing, and Thermal Architecture Leaks Analyzed
How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)
Pre-IPO Investing Strategies: How Institutional Money is Approaching Anthropic
CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]
NASA Cyberattack 2026: What the China Hack Means for Your Data Security
Smash Bros Ultimate 13.0.5 Patch Notes: What Actually Changed
Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
World School Summit 2026 Malaysia: 41st Edition
NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support
-
Digital5 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital5 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
China5 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business4 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools