AI
The Quiet Preparation: Will 2026 Mark the Revival of Southeast Asia’s IPO Hopefuls?

Southeast Asia tech startups are quietly strengthening corporate governance and cleaning their books for a major IPO comeback in 2026. Explore the data, trends, and strategic shifts reshaping the region’s capital markets.
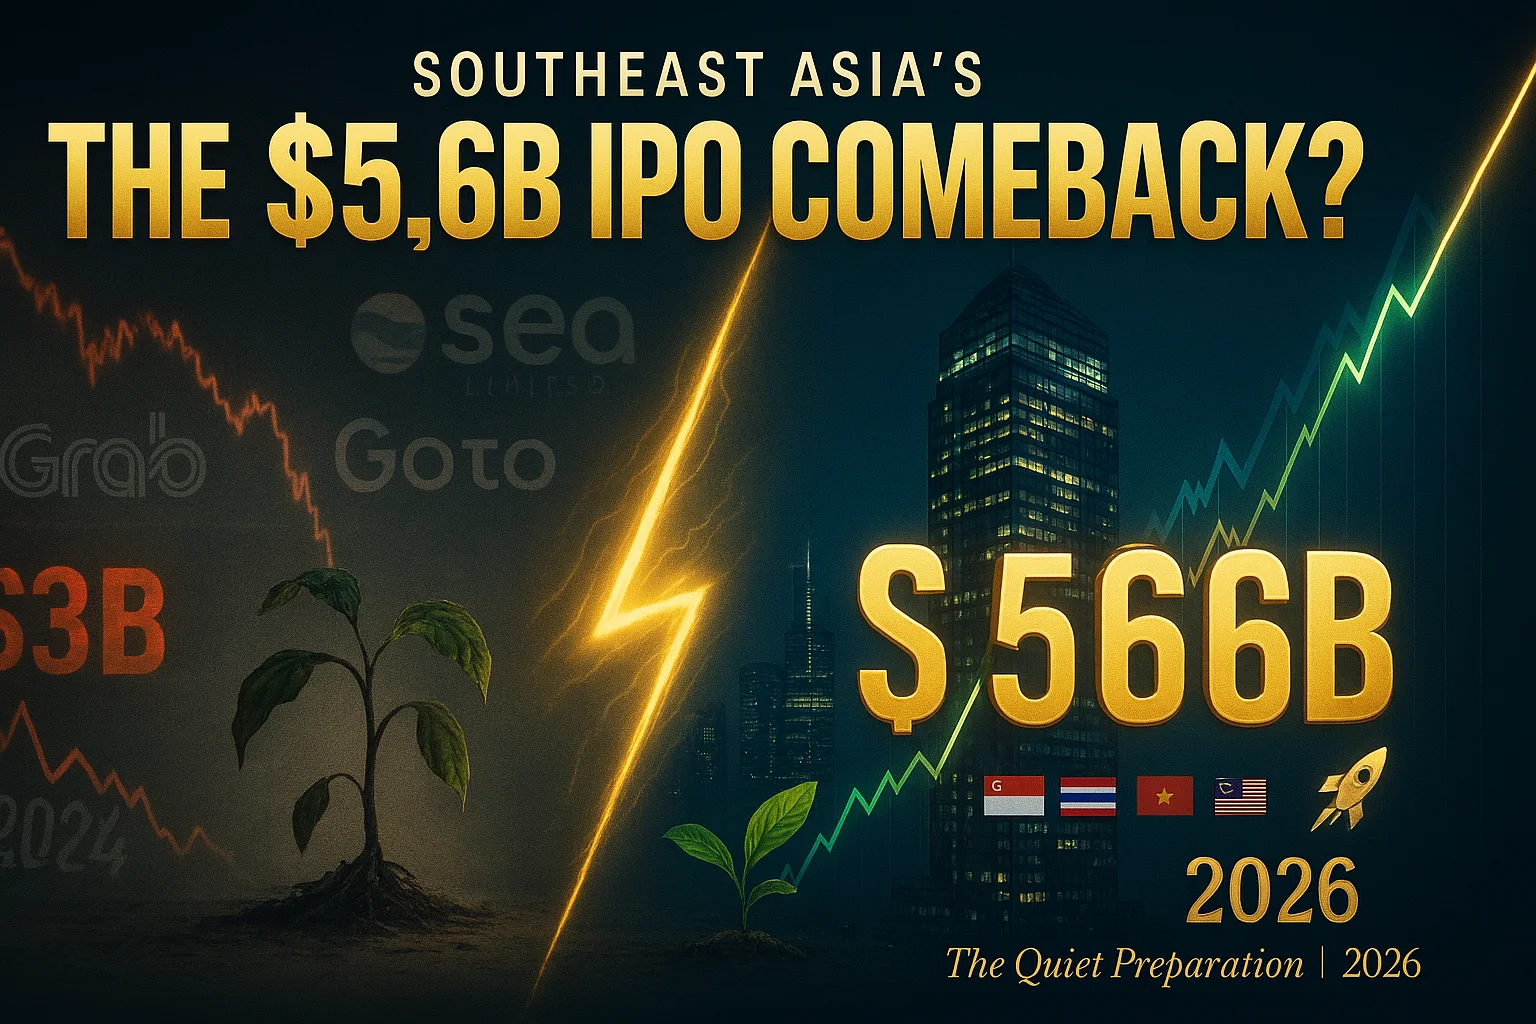
In the hushed corridors of Singapore’s financial district and Jakarta’s tech hubs, something remarkable is unfolding. While headlines trumpet AI breakthroughs and cryptocurrency swings, Southeast Asia’s tech startups are conducting a different kind of transformation—one that happens behind closed boardroom doors, in audit committee meetings, and through painstaking restructuring of corporate governance frameworks. After weathering a brutal funding winter that saw IPO activity plunge to its lowest level in nearly a decade in 2024, with only $3.0 billion raised across 122 IPOs, the region’s most ambitious companies are now methodically preparing for what many believe will be a defining moment: the 2026 IPO revival.
This isn’t the frenzied SPAC-era optimism of 2021. This is something more deliberate, more strategic—and potentially more sustainable.
The Harsh Reality Check: Southeast Asia’s IPO Winter
The numbers tell a sobering story. In 2024, Southeast Asia’s IPO markets raised approximately $3.0 billion across 122 listings in the first 10.5 months—the lowest capital raised in nine years, down from $5.8 billion across 163 IPOs in 2023. Even more striking, only one IPO in 2024 raised over $500 million, compared to four such blockbuster listings the previous year.
For context, this represents a dramatic reversal from the pandemic-era boom when Southeast Asian tech companies commanded eye-watering valuations and international investors couldn’t deploy capital fast enough. The e-Conomy SEA report had projected the region’s digital economy would reach $363 billion by 2025, but the path to monetizing that growth through public listings proved far more treacherous than anticipated.
What happened? The perfect storm arrived with force.
High interest rates across ASEAN economies constrained corporate borrowing, dampening IPO activity as companies opted to delay public listings, explained Tay Hwee Ling, Capital Markets Services Leader at Deloitte Southeast Asia. Add to that mix currency fluctuations, geopolitical tensions affecting trade, and market volatility among major trade partners like China that impacted investor confidence, and you have an environment where even the most promising tech companies chose to stay private.
The venture capital funding landscape mirrored this decline. Southeast Asian VC funding hit rock bottom in Q4 2024, with startups mustering only 116 equity capital rounds raising $1.2 billion—the lowest quarterly deal volume in more than six years. Late-stage fundraising took a particularly severe hit, with funding plunging by 64% and deal value dropping by 72%.
For Southeast Asia’s tech unicorns and aspiring public companies, the message was clear: the old playbook was broken.
The Turning Tide: Why 2026 Looks Different
Yet amid this apparent gloom, a remarkable transformation is taking shape. In the first 10.5 months of 2025, Southeast Asia’s IPO capital markets showed a rebound, with 102 IPOs raising approximately $5.6 billion—a 53% increase in total proceeds despite fewer listings than 2024. The average deal size more than doubled, rising from $27 million in 2024 to $55 million in 2025, driven by larger, higher-quality offerings.
This isn’t just a cyclical uptick. Multiple structural factors are converging to create what could be the region’s most favorable IPO environment in five years.
Macroeconomic Tailwinds Gathering Strength
The macroeconomic backdrop is stabilizing in ways that matter for capital markets. Expected interest rate cuts alongside easing inflation are creating a more favorable environment for IPOs in the years ahead, according to Deloitte’s regional analysis.
The IMF projects ASEAN to grow at 4.3% in both 2025 and 2026, while the Asian Development Bank forecasts developing Asia’s growth at 4.9% in 2025 and 4.7% in 2026. Though these figures fall short of historical averages, they represent stable, predictable growth—exactly what public market investors crave after years of volatility.
More critically, the digital economy component of this growth is accelerating. Thailand’s digital economy, estimated to contribute around 6% of GDP, is the second largest in the ASEAN region, with financial services, digital payments, and fintech seeing some of the fastest rates of job creation. By 2030, ASEAN’s digital economy is expected to more than double to $560 billion, driving jobs and innovation across the region.
This creates a powerful narrative for IPO candidates: they’re not just individual companies going public, but representatives of the fastest-growing segment of the world’s fourth-largest economy.
Regulatory Evolution: The Singapore Catalyst
Perhaps nothing signals the changing IPO landscape more clearly than Singapore’s aggressive regulatory reforms. The Monetary Authority of Singapore convened a review group to assess and enhance the country’s IPO ecosystem, with recommendations aiming to advance Singapore toward a more disclosure-based regulatory regime aligned with major developed markets.
The $5 billion Equity Market Development Programme represents more than just capital—it’s a statement of intent. Singapore is positioning itself as the natural listing destination for Southeast Asian tech companies that might have previously eyed New York or Hong Kong.
Several SaaS and fintech firms are said to be preparing to list in late 2025 or 2026, encouraged by the success of dual-listed companies and growing institutional interest in digital transformation themes. The successful debut of NTT Data Centre REIT, Singapore’s biggest IPO in four years, has injected renewed confidence into the market.
This regulatory evolution addresses a critical pain point. In the past, Southeast Asian companies often felt they had to choose between staying local with limited liquidity or going international with regulatory complexity. Singapore’s reforms aim to offer the best of both worlds: international standards with regional understanding.
Private Equity’s Patient Capital Creates IPO Pipeline
Another crucial development is private equity’s evolving role in the ecosystem. A total of 35 secondary exits were completed in 2025, marking the highest annual count since 2020, as sponsors adjusted expectations around timing, pricing, and structure.
This might seem counterintuitive—more secondary sales could mean fewer IPOs—but it actually creates a healthier pipeline. PE-backed companies that go through secondary transactions often emerge stronger, with cleaned-up cap tables and more realistic valuations. PE-backed IPOs in Southeast Asia in 2025 marked a clear departure from the previous cycle, with no single sector dominating as issuance shifted toward execution-driven offerings sized to clear the market.
Golden Gate Ventures and INSEAD estimate 700 exits, including IPOs and trade sales, between 2023 and 2025, driven by regional tech leaders and late-stage capital injections. These aren’t distressed sales—they’re strategic repositioning ahead of more favorable public market windows.
The Quiet Preparation: Inside the Corporate Governance Transformation
Here’s where the story gets truly interesting. Behind the IPO statistics and macroeconomic forecasts, Southeast Asia’s tech companies are undergoing a fundamental transformation in how they operate, govern themselves, and present their financials to the world.
Cleaning the Books: From Growth-at-All-Costs to Unit Economics
The phrase “cleaning the books” has become shorthand for a comprehensive financial overhaul that goes far beyond simple accounting adjustments. Companies preparing for 2026 IPOs are fundamentally rethinking how they measure and present success.
Take GoTo Group, Indonesia’s largest tech company formed from the merger of Gojek and Tokopedia. After years of negative earnings and billion-dollar write-downs, GoTo is inching closer to profitability, with net revenue 14% higher than the previous year and losses shrinking from IDR 4.5 trillion ($269 million) to about IDR 1 trillion ($60 million) in the first nine months of 2025.
This transformation involved painful but necessary changes: tighter control of incentive spending, pricing scheme adjustments, and a bigger role for their finance division in driving revenue. Cash from operations showed steady improvement, with deficits falling to around IDR 160 billion ($10 million) by the third quarter—roughly one-tenth of the negative operating cash flow at the same point in 2024.
The shift represents a broader industry reckoning. Companies are moving away from adjusted EBITDA metrics that exclude “non-recurring” expenses that somehow recur every quarter, toward genuine GAAP profitability or clear paths to it. Revenue recognition is being standardized to match international accounting standards. Related-party transactions—once common in family-controlled Asian conglomerates—are being eliminated or made fully transparent.
As one venture capital partner told me off the record: “In 2021, you could go public burning $100 million a quarter if your growth rate was impressive. In 2026, investors want to see that you can turn a profit within 12-18 months of listing, or at minimum, that your path to profitability doesn’t depend on hoping for better market conditions.”
Governance Overhaul: Building Boards That Command Respect
The governance transformation is equally dramatic. Building strong corporate governance is essential, including installing professional management, establishing a strong board of directors and commissioners, and forming key committees, noted Silva Halim, Chief Capital Market Officer of Mandiri Sekuritas.
What does this look like in practice? Companies are:
Professionalizing leadership structures: Founder-CEOs are surrounding themselves with experienced CFOs who have taken companies public before, often recruited from established listed companies or Big Four accounting firms.
Adding independent directors with relevant expertise: Boards are being expanded to include former executives from similar-stage companies, regulatory experts, and representatives from institutional investors. The days of boards comprising only founders, early investors, and friendly advisors are ending.
Establishing robust committee structures: Audit committees with genuinely independent chairs, compensation committees that tie executive pay to performance metrics investors care about, and risk management committees that don’t just exist on paper.
Implementing ESG frameworks: Environmental, Social, and Governance considerations are no longer nice-to-haves. They’re table stakes for institutional investors, particularly those based in Europe and increasingly Asia.
Three of Southeast Asia’s five newest unicorns—Carro, GCash, and others—are actively preparing for IPOs, which forces them to clean up governance and meet public-market expectations. Carro, the automotive marketplace, expects a potential US IPO in late 2025 or early 2026 and has been systematically strengthening its governance framework in preparation.
The Capital Structure Simplification
Perhaps the most complex aspect of IPO preparation is unwinding the convoluted capital structures many Southeast Asian tech companies accumulated during their private funding years.
Multiple share classes with different voting rights, convertible notes from emergency funding rounds, preferred shares with liquidation preferences that give early investors disproportionate exit returns—all of these need to be rationalized before a successful public listing.
The process requires delicate negotiation. Early-stage investors who took risks when a company was worth $10 million don’t want to be diluted to meaninglessness now that it’s valued at $1 billion. Founders want to maintain enough control to execute their vision. Public market investors want governance structures that protect minority shareholders.
Finding the balance is as much art as science, and it’s one reason the IPO preparation process now takes 18-24 months rather than the 6-12 months that was common in the SPAC era.
Sector Spotlight: Who’s Best Positioned for 2026?
Not all sectors are created equal in the coming IPO revival. The data reveals clear winners based on both investor appetite and operational readiness.
Fintech: The Perennial Favorite with New Maturity
FinTech continued to lead as the top-funded industry in Southeast Asia, attracting $821 million across 78 deals in the first nine months of 2024, despite year-over-year declines. The sector’s dominance reflects both its market maturity and the improving unit economics of regional fintech players.
GCash, the Philippines’ leading digital wallet, stands out. New funding from Ayala and MUFG in 2024 boosted GCash’s valuation and positioned the company for an IPO in 2025, which would mark a major milestone for the Philippine startup scene. The company has moved beyond pure payments to offer a full suite of financial services—loans, insurance, investment products—creating multiple revenue streams that public market investors value.
Thunes, which became a unicorn in early 2025 after a $150 million Series D, exemplifies the infrastructure play that resonates with institutional investors. Rather than competing in crowded consumer spaces, it provides the rails that enable cross-border payments, a B2B model with stronger margins and more predictable revenue.
Infrastructure and Logistics: The Unsexy Winners
While consumer tech grabbed headlines during the pandemic boom, infrastructure and logistics companies are emerging as IPO favorites precisely because they’re less glamorous. They have real assets, predictable cash flows, and business models that make sense without squinting.
Data centers, in particular, are hot. Singapore’s successful listing of NTT Data Centre REIT validated the thesis that digital infrastructure can be packaged as stable, income-producing assets. As AI adoption accelerates and cloud migration continues, the demand for data center capacity in Southeast Asia is outpacing supply.
Logistics networks built by e-commerce giants and delivery platforms have also matured to the point where they could be spun off as standalone entities. These networks have tangible value: warehouses, last-mile delivery fleets, sophisticated routing algorithms, and established relationships with millions of merchants and consumers.
Automotive and Mobility: The Vertical Integration Play
Carro started as a used car platform but has evolved into a multi-service mobility business, integrating financing, insurance, after-sales service, AI-led vehicle inspections and logistics. This vertical integration strategy represents a sophisticated understanding of what public market investors want to see: control over the entire value chain creates both competitive moats and opportunities to capture margin at multiple points.
The automotive sector in Southeast Asia remains fragmented and under-digitized, creating genuine opportunities for tech-enabled consolidation. Whoever controls both the data and the distribution wins—and that thesis is compelling enough to attract IPO investors willing to bet on multi-year transformations.
The Risk Factors: What Could Derail the Revival
For all the optimism, significant risks loom over Southeast Asia’s IPO renaissance.
Global Recession Fears and Trade Policy Uncertainty
Meanwhile, US President-elect Donald Trump’s return to the White House represents a wild card for many markets, including IPOs, with the revival of “America First” trade policies potentially upending Southeast Asia’s IPO ambitions.
The return of protectionist trade policies could disrupt the export-dependent growth models of many Southeast Asian economies. If tariffs on Chinese goods lead to a broader trade war, and if Southeast Asian countries get caught in the crossfire as production shifts out of China, the macroeconomic stability necessary for robust IPO markets could evaporate quickly.
China Economic Slowdown Spillover
A worse-than-expected deterioration in China’s property market could disrupt prospects across Asia, the IMF warned in its regional outlook. China remains Southeast Asia’s largest trading partner and a major source of tourism revenue. An economic hard landing in China would reduce demand for Southeast Asian exports and potentially trigger capital flight from regional markets.
Currency Volatility and Capital Controls
Exchange rate instability remains a perennial concern. Companies that earn revenue in Indonesian rupiah, Thai baht, or Vietnamese dong but report in US dollars face constant translation risks. Sharp currency depreciations can turn profitable quarters into losses on paper, spooking investors.
More concerning is the possibility of capital controls if regional currencies come under sustained pressure. Malaysia’s experience with capital controls during the Asian Financial Crisis remains a cautionary tale that international investors remember.
Regulatory Unpredictability
Despite Singapore’s positive reforms, regulatory uncertainty persists across the region. Data localization requirements in Indonesia and Vietnam can force costly infrastructure changes. Cross-border payment regulations vary wildly between countries. Competition authorities are increasingly scrutinizing dominant platforms.
For companies hoping to list in 2026, the challenge is preparing for an IPO while remaining nimble enough to adapt to regulatory changes that could fundamentally alter their business models.
Post-IPO Performance Anxiety
Perhaps the biggest risk is the memory of previous disappointments. Grab’s post-SPAC performance—trading well below its initial valuation—haunts the sector. Sea Limited’s rollercoaster ride from pandemic darling to value destruction and back has made investors wary of Southeast Asian tech valuations.
New IPO candidates need to deliver not just successful listings but sustained post-IPO performance. One or two high-profile flameouts in 2026 could shut the window for everyone else.
Investment Implications: Reading the Tea Leaves
For institutional investors, the 2026 Southeast Asia IPO pipeline presents both opportunities and obligations to conduct rigorous due diligence.
Valuation Frameworks for a New Era
The valuation multiples of 2021—when companies could command 20x forward revenue—are gone. Today’s IPO candidates should expect 5-8x revenue multiples for profitable companies, 3-5x for those with clear paths to profitability within 18 months.
The shift means companies need much larger revenue bases to achieve the same market capitalizations. A company targeting a $5 billion valuation needs at least $800 million in revenue, not the $250 million that might have sufficed in 2021.
For growth-stage investors and late-stage VCs, this creates both challenges and opportunities. Entry valuations must be disciplined enough to allow for successful exits even at more modest public market multiples. But for those who invested in 2022-2023 at trough valuations, the returns could be substantial.
Geographic Focus: Not All Markets Are Equal
Singapore will continue to dominate Southeast Asian tech IPOs in 2026, but Indonesia and Vietnam are increasingly viable alternatives for companies with strong domestic market positions.
Indonesia’s market offers scale—270 million people, rapidly growing middle class, improving digital infrastructure. Companies that can demonstrate market leadership in Indonesia, even if they’re not yet regional champions, can make compelling IPO cases.
Vietnam presents a different opportunity: manufacturing and export-oriented plays that benefit from China-plus-one strategies. Tech-enabled manufacturing, logistics, and supply chain companies based in Vietnam may find receptive public markets.
Sectoral Selectivity
Within sectors, investors should prioritize:
In fintech: Companies with lending and asset management products, not just payment facilitation. The former have better unit economics and more defensible moats.
In e-commerce: Vertical specialists (automotive, luxury, B2B) rather than horizontal generalists competing with Sea Limited and Lazada.
In SaaS: Companies with strong presence in multiple Southeast Asian markets and demonstrated ability to expand upmarket to enterprise customers.
In logistics: Asset-light models leveraging technology to coordinate third-party capacity, rather than capital-intensive approaches requiring continuous fundraising.
Policy Recommendations: Enabling Sustainable Growth
For Southeast Asian governments and regulators hoping to support vibrant public markets, several policy priorities emerge.
Harmonize Listing Requirements
The fragmentation of listing requirements across ASEAN exchanges creates unnecessary complexity. A startup that meets SGX listing requirements should be able to list on the Indonesia Stock Exchange or Stock Exchange of Thailand with minimal additional compliance burden.
Progress on the ASEAN Digital Economy Framework Agreement could provide a template for similar harmonization in capital markets regulation. The goal isn’t identical rules—each market has unique characteristics—but mutual recognition and reduced friction.
Strengthen Market Infrastructure
Retail investor participation in IPOs remains limited in most Southeast Asian markets outside Singapore. Improving digital brokerage infrastructure, reducing transaction costs, and educating retail investors about public markets would broaden the investor base and improve post-IPO liquidity.
Malaysia and Thailand have made progress on digital brokerage adoption, but Indonesia, Vietnam, and the Philippines lag behind. Governments could accelerate adoption through tax incentives for small investors and regulatory sandboxes for innovative brokerage models.
Develop Institutional Investor Base
Southeast Asia needs more domestic institutional capital to reduce dependence on foreign portfolio flows that can reverse quickly during global risk-off episodes.
Pension reforms to allow higher equity allocations, insurance regulation that doesn’t penalize public equity investments, and sovereign wealth fund strategies that include domestic tech exposure would all help develop a more stable institutional investor base.
Address Short-Termism in Corporate Governance Codes
Many Asian corporate governance codes emphasize quarterly reporting and short-term performance metrics. While transparency is valuable, this can discourage the long-term investments in R&D, market expansion, and talent development that tech companies need.
Reforms could include longer protected periods for newly listed companies before they face takeover attempts, allowing founders to maintain dual-class voting structures for defined periods, and encouraging long-term incentive compensation tied to multi-year milestones.
Strategic Advice: Navigating the Path to Public Markets
For founders and CFOs contemplating 2026 IPOs, several strategic imperatives stand out.
Start Earlier Than You Think
IPO preparation isn’t something you begin six months before filing. The companies most likely to succeed in 2026 began their preparations in 2024 or earlier.
This means installing audit committees now, conducting pre-IPO audits of financial controls, identifying and fixing revenue recognition issues before underwriters spot them, and beginning the process of board professionalization well before you need those independent directors’ signatures on registration statements.
Choose Your Market Thoughtfully
The question “Where should we list?” requires sophisticated analysis of where your customers are, where comparable companies trade, and where you can maintain liquidity post-IPO.
For truly regional companies, dual listings merit consideration. The complexity and cost are substantial, but accessing both Asian and Western capital pools can be worth it. For companies with clear geographic anchors, listing close to your customer base makes sense even if valuations are somewhat lower—the understanding and long-term support from local institutional investors often outweighs pure valuation optimization.
Build Your Equity Story Deliberately
Companies need a compelling equity story and investment thesis that will resonate with public investors, with long-term goals focused on positive market reception and sustained aftermarket performance, advised Pol de Win, SGX Group’s Senior Managing Director.
This equity story needs to be more sophisticated than “We’re the X of Southeast Asia.” Public market investors want to understand your unit economics at a granular level, see evidence of defensible competitive advantages, understand how you’ll allocate capital, and have confidence in your management team’s ability to execute through market cycles.
Testing this story with pre-IPO investors through structured investor education—think non-deal roadshows conducted 12-18 months before listing—can reveal weaknesses in your narrative and give you time to address them.
Manage Expectations Conservatively
One of the biggest mistakes of the SPAC era was over-promising on growth and profitability trajectories. Companies projected hockey-stick growth that never materialized, destroying credibility and shareholder value.
The companies that will succeed in 2026 will be those that guide conservatively and consistently beat their own projections. Sandbagging should be avoided—investors can spot it and penalize you for it—but realistic planning that accounts for macroeconomic headwinds and competitive challenges will serve you better than blue-sky scenarios.
Looking Forward: Southeast Asia’s Moment
If 2021 was the frothy champagne era and 2024 was the sobering hangover, then 2026 represents something different—maturity, discipline, and the genuine transformation of Southeast Asian tech companies from venture-backed startups to sustainable public companies.
The region’s fundamental strengths remain intact: Southeast Asia’s strong consumer base, growing middle class, and strategic importance in sectors like real estate, healthcare, and renewable energy remain attractive to investors. ASEAN has already delivered a five-fold expansion in economic output this century, and the digital transformation is still in relatively early innings.
What’s changed is the understanding of what it takes to succeed as a public company. The discipline being instilled through the current IPO preparation process—the governance overhauls, the financial rigor, the strategic clarity—will serve these companies well beyond their listing dates.
Will 2026 mark the revival of Southeast Asia’s IPO hopefuls? The data suggests yes, but with an important caveat: it won’t be a revival of the 2021 model. It will be the emergence of something better—more sustainable, more honest about challenges, more realistic about valuations, and more committed to delivering long-term value rather than short-term excitement.
For investors who can navigate this landscape with sophistication, who can distinguish between genuinely transformative companies and those merely riding a cyclical upturn, the opportunities could be substantial. For the broader Southeast Asian tech ecosystem, this moment represents a coming-of-age—the transition from a region of promising startups to a mature market of public technology companies that can compete on the global stage.
The quiet preparation happening now in boardrooms and audit committees across Southeast Asia matters more than any single IPO. It represents the infrastructure—not physical infrastructure, but the governance, financial discipline, and strategic clarity—upon which decades of public market success can be built.
2026 won’t be the end of Southeast Asia’s IPO story. If the preparation is done right, it will be the beginning of a much longer and more sustainable chapter.
Sources Cited:
- Deloitte Southeast Asia (2024, 2025). “Southeast Asian IPO Market Reports”
- Asian Development Bank (2025). “Asian Development Outlook”
- International Monetary Fund (2025). “ASEAN Regional Economic Outlook”
- MAGNiTT (2024). “Southeast Asia Venture Capital Landscape”
- DealStreetAsia (2024, 2025). “DATA VANTAGE Reports”
- World Bank (2025). “Thailand Economic Monitor”
- East Ventures (2025). “Building a Vibrant IPO Ecosystem in Southeast Asia”
- PwC (2024). “Global IPO Trends”
- Golden Gate Ventures & INSEAD (2024). “Southeast Asia Exit Report”
- Tech Collective (2025). Various industry analyses
- World Economic Forum (2025). “ASEAN Digital Economy Report”
- GSMA Intelligence (2025). “Digital Nations 2025: ASEAN Connectivity”
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


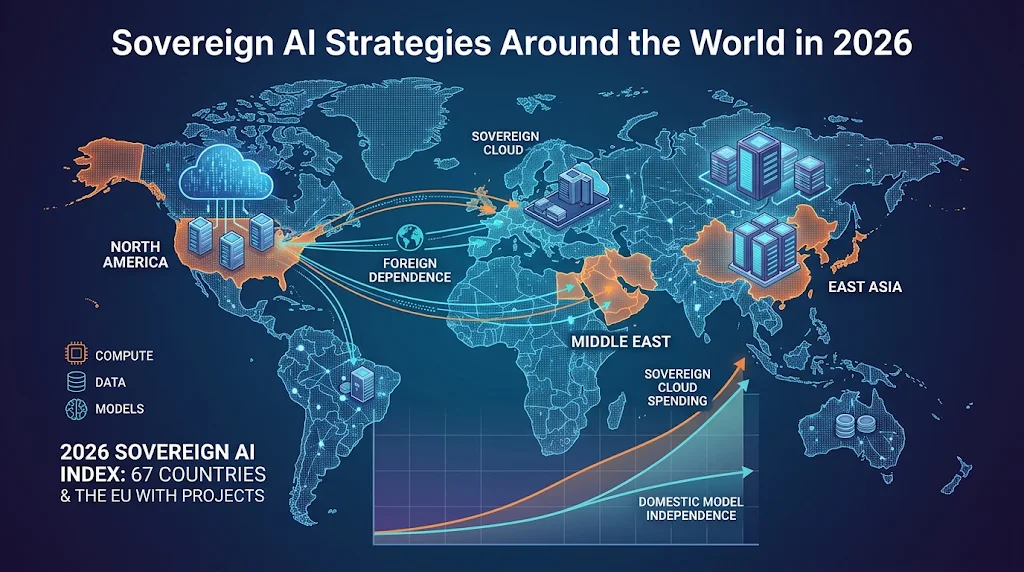
Governments are spending heavily to build domestic AI capacity, from data centers and compute clusters to national language models. The Center for a New American Security’s Sovereign AI Index tracked 67 countries and the European Union with projects by mid-2026, and it found that most of the disclosed investment is concentrated in the Middle East and East Asia. The core tension is that most sovereign projects still rely on American or foreign technology providers.
Key Takeaways
- The CNAS Sovereign AI Index counted 67 countries and the European Union with sovereign AI projects by mid-2026, according to its August 2026 update.
- The Middle East and East Asia account for more than 80% of tracked, publicly disclosed sovereign AI investment, per the CNAS index.
- Infrastructure now dominates new projects: about 80% of projects launched in the first half of 2026 focused on infrastructure, up from 62% in the prior six months.
- Gartner expects China and North America to lead sovereign cloud infrastructure spending in 2026, at roughly $47 billion and $16 billion, respectively, and Europe to surpass North America in 2027.
- Most sovereign projects still depend heavily on foreign providers, often American ones, which limits the autonomy they promise.
What Sovereign AI Means
There is no single definition, which complicates comparisons. The CNAS index treats a sovereign AI project as a government-backed initiative tied to national strategic interests and backed by material public investment in domestic capabilities. Other analysts use the term more broadly to include regulatory control, data localization, and domestic model development.
In practice, governments pursue three layers of capability:
- Compute: data centers, GPUs, and sovereign cloud platforms
- Data: national datasets for training and public-sector use
- Models: domestic foundation models, often tuned to local languages and laws
According to the CNAS index, compute and infrastructure dominate, while data projects remain the smallest category, accounting for about 5% of new projects in the first half of 2026.
Who Is Spending
Spending is highly concentrated. The CNAS index reports that about 40% of tracked countries back only a single project, and that a few large national commitments account for much of the total.
Several examples illustrate scale:
- India: Adani Group announced plans in February 2026 to invest $100 billion in sovereign AI infrastructure by 2035, which it said could contribute to a broader $250 billion ecosystem in the country, per BusinessToday. This is a private commitment, not a government budget figure.
- South Korea: Reports describe a 2026 national AI budget of about 9.9 trillion won, roughly $7.1 billion, across dozens of ministries. This figure comes from a secondary source, so confirm it against official government releases before publication.
- United States: The Stargate project, announced in January 2025 by OpenAI, SoftBank, and Oracle, has a stated commitment of $500 billion over four years. It is largely private rather than public investment.
- Gulf states: Investment in the Middle East is among the largest by disclosed value, per the CNAS index, which accounts for much of the regional concentration.
Stanford’s 2026 AI Index found that national AI strategies are expanding fastest among countries that had no formal AI policy five years ago, and that U.S. public investment in AI remains modest relative to private spending.
The Sovereignty Paradox
Most countries pursuing sovereign AI rely on foreign technology. The CNAS index found that foreign companies, overwhelmingly American, remain embedded in more than 170 national infrastructure and model projects. Many sovereign data centers run on U.S.-designed chips, use American cloud software, or depend on American model architectures.
This creates a paradox. Governments want independence from foreign dependence, yet building independent capability is expensive and slow. Gartner has warned that sovereign AI strategies could lock countries into region-specific platforms: it predicted in January 2026 that 35% of countries would be locked into such platforms by 2027, according to its press release. The paradox is that regional independence can create its own dependencies.
Gartner also projected that nations building a sovereign AI stack would need to spend at least 1% of GDP on AI infrastructure by 2029. For smaller economies, that is a significant commitment.
Sovereign Cloud Is the Fastest-Growing Piece
Sovereign cloud, which keeps data and processing within national borders under local control, is one of the clearest growth areas. Gartner projected 2026 sovereign cloud infrastructure-as-a-service spending of about $47 billion in China and $16 billion in North America, with Europe expected to surpass North America in 2027. The European shift reflects a move away from U.S.-based cloud providers, driven by regulatory and geopolitical concerns.
Why Some Countries Are Building Anyway
The motivations are mixed. Governments cite economic competitiveness, national security, data protection, and the desire to shape local AI use. Some want to retain talent and attract AI companies. Others want to avoid being dependent on a single supplier if export controls or geopolitics disrupt access to chips and cloud services.
Cost is the main limit. As one industry analysis put it, the level of investment required is beyond the reach of most countries, which creates an asymmetry in the global AI landscape. Many countries will rely on partnerships rather than fully independent stacks.
Trade-Offs and Risks
Sovereign strategies carry real trade-offs:
- Capability gap. Domestic models may trail frontier systems, requiring governments to accept lower performance for control.
- Duplication. Multiple countries building similar infrastructure can waste capital if utilization is low.
- Supplier dependence. Chips, networking, and software often come from a small set of firms, limiting independence.
- Energy and land. Like the data center backlash in the U.S., sovereign projects face power and local-approval constraints.
- Fiscal risk. Public money committed to AI infrastructure must compete with healthcare, education, and defense budgets.
What to Watch
- Whether sovereign projects shift from announcements to operating capacity, which CNAS identifies as a key test
- Growth in sub-national sovereign AI projects, which CNAS reports have risen rapidly in 2026
- European sovereign cloud procurement and any move away from U.S. providers
- Export control changes that could affect chip access for national projects
- Gartner and CNAS updates on sovereign spending and lock-in patterns
Frequently Asked Questions
What is sovereign AI? Sovereign AI refers to government-backed efforts to build or control AI infrastructure, data, and models within national borders, often to reduce dependence on foreign providers.
Which countries are leading? By disclosed investment, the Middle East and East Asia lead, according to the CNAS Sovereign AI Index. Specific country rankings depend on how projects are counted.
How much are countries spending on sovereign AI? Estimates vary widely depending on definition. Gartner projects sovereign cloud IaaS spending of about $47 billion in China and $16 billion in North America in 2026, while private commitments such as Adani’s $100 billion plan add to the total.
Do sovereign AI projects use American technology? Often, yes. The CNAS index found that foreign companies, mostly American, remain embedded in more than 170 projects.
Is sovereign AI a good investment for governments? It depends on the country. Costs are high, and returns depend on whether infrastructure is used productively. Governments that tie investment to local skills and research tend to get more value.
What is the risk of sovereign AI? Duplication, supplier dependence, underused capacity, and fiscal strain are the main risks. Some projects may also fall short of their stated independence goals.
Conclusion: Independence Is Expensive
Sovereign AI is becoming a central feature of global technology policy in 2026, but true independence is expensive and hard to achieve. Most countries are building compute with foreign components, and some will end up depending on new regional platforms. Readers should judge sovereign strategies by whether they deliver working capacity, skills, and reduced vulnerability, not just by announced totals.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
AI
PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand
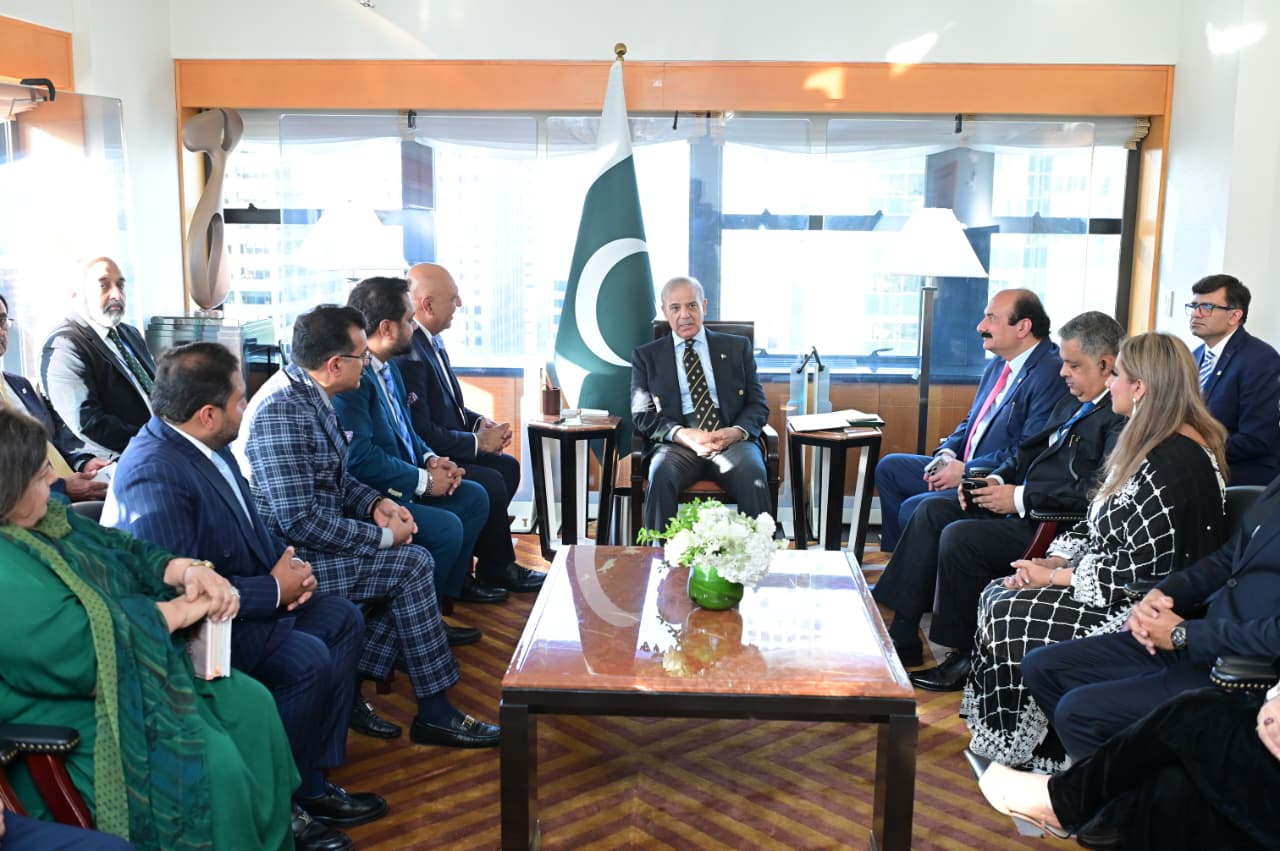
NEW YORK, September 24, 2026 — Prime Minister Muhammad Shehbaz Sharif has invited Pakistani business leaders and professionals based in the United States to invest in Pakistan, highlighting government measures aimed at improving the business environment and encouraging investment.
The invitation came during meetings with Pakistani-American business personalities and professionals working across information technology, artificial intelligence, automobiles, energy, construction and other sectors.
According to the Associated Press of Pakistan (APP), the prime minister said the government was working to create a conducive environment for investment and business activity. He also pointed to reforms at the Federal Board of Revenue (FBR) and measures intended to promote innovation in agriculture.
But the latest appeal to the Pakistani-American business community comes against a broader backdrop: Pakistan is seeking to attract more private investment, expand exports and turn improving macroeconomic conditions into sustained economic activity.
Why Pakistani-American Investors Are Being Targeted
The Pakistani diaspora represents an important source of capital, business expertise and international commercial connections.
Pakistan’s remittance flows demonstrate the economic significance of its overseas population. World Bank data show that Pakistan received approximately $40.48 billion in personal remittances in 2025, equivalent to around 9.9% of GDP.
The State Bank of Pakistan also reported workers’ remittances of approximately $3.66 billion in August 2026, with the monthly series showing substantial inflows throughout 2026.
Investment, however, differs from remittances: it involves deploying capital into businesses, projects or financial assets with the expectation of returns. That distinction makes the government’s effort to attract diaspora entrepreneurs particularly relevant.
IT and AI Among the Sectors in Focus
The technology sector is one of the most significant areas highlighted by the government.
The September 24 meeting included Pakistani-American professionals associated with IT and artificial intelligence, alongside representatives from traditional sectors such as automobiles, energy and construction.
Pakistan’s broader investment framework identifies services, including IT and telecommunications, as areas open to foreign investment. The Board of Investment says Pakistan maintains a liberal investment regime and has mechanisms designed to facilitate local and foreign investors.
For Pakistani-American technology entrepreneurs, potential areas include:
- Software and SaaS businesses
- Artificial intelligence
- IT-enabled services
- Fintech
- Digital infrastructure
- Business-process outsourcing
- Export-oriented technology companies
- Technology startups and venture investment
The attraction for diaspora entrepreneurs is not necessarily limited to providing capital. Entrepreneurs with operations in the United States can potentially bring technology, management expertise, international customers, investment networks and access to global markets.
Agriculture Is Another Priority
Agriculture was also specifically mentioned during the prime minister’s meetings.
APP reported that Shehbaz Sharif said the government was taking measures to promote innovation in agriculture.
That creates potential investment themes around:
- Agri-processing
- Agricultural technology
- Cold-chain infrastructure
- Food processing
- Irrigation technology
- Storage and logistics
- Export-oriented agriculture
- Livestock and dairy
- Farm mechanization
For investors, the distinction between producing agricultural commodities and investing in higher-value processing and supply-chain infrastructure can be particularly important because value-added businesses can connect domestic production with international markets.
What Pakistan’s Investment Framework Offers Foreign Investors
Pakistan’s Board of Investment states that the country follows a liberal investment regime and that its mandate includes promoting, encouraging and facilitating both local and foreign investment.
The Board’s investment information also states that foreign investors can have 100% equity ownership in many areas, although restrictions or specific rules apply to certain sectors.
The government’s Investment Policy 2023 also emphasizes investor protection, investment promotion and expanding Pakistan’s investment-promotion presence abroad, including in the United States.
That policy framework provides important context for the prime minister’s latest appeal to Pakistani-American businesses.
Pakistan Has Also Introduced a New Long-Term Residency Route for Investors
Another development relevant to international investors is Pakistan’s Long-Term Residency (LTR) framework.
According to the Board of Investment, the Foreigners (Long Term Residency) Order, 2025 created a residency-by-investment framework offering five-, seven- and ten-year residency options, subject to eligibility and investment requirements. The BOI says the minimum investment requirement is $50,000, to be materialized within one year through authorized banking channels.
The scheme is separate from the government’s broader investment-promotion policies, but it illustrates the effort to create additional mechanisms for attracting international capital and entrepreneurs.
The U.S.-Pakistan Economic Relationship Adds Another Layer
The appeal to Pakistani-American businesses also comes while economic engagement between Pakistan and the United States remains an important part of Pakistan’s external economic strategy.
In July 2026, Reuters reported that Pakistan had requested a proposed $10 billion U.S. exchange stabilization facility, while discussions were also taking place with U.S. financial institutions including the Export-Import Bank and the U.S. International Development Finance Corporation.
More recently, Reuters reported that Pakistan expected a decision from the United States on the proposed facility while continuing discussions with U.S. EXIM Bank and the Development Finance Corporation on potential projects.
These developments concern government-to-government and institutional financing rather than Pakistani-American private investment, but together they illustrate the wider economic relationship in which the latest business-community outreach is taking place.
What the Government Says About Investment Facilitation
Pakistan’s Board of Investment describes itself as the interface between international and domestic investors and the public and private sectors. Its investment regime information highlights measures intended to reduce the cost and procedural burden of doing business and to facilitate investment.
The government has also continued promoting the Special Investment Facilitation Council and other mechanisms intended to streamline investment processes.
For an investor considering Pakistan, however, the existence of an investment framework does not remove the need for sector-specific due diligence, regulatory approvals, taxation analysis, foreign-exchange considerations and commercial risk assessment.
What Pakistani-American Investors Should Examine Before Investing
The prime minister’s invitation is a political and economic call for greater investment, but prospective investors still need to evaluate individual opportunities on their own merits.
Key issues include:
1. Regulatory requirements
Investment rules differ according to the sector. The BOI notes that some industries are subject to specific restrictions or approvals.
2. Ownership structure
Foreign ownership can reach 100% in many sectors, but exceptions exist, making a sector-specific review necessary before establishing a company.
3. Profit and capital repatriation
Pakistan’s investment framework provides mechanisms for foreign investors to repatriate eligible profits, dividends and investment proceeds, subject to applicable foreign-exchange procedures.
4. Taxation
Investors should examine federal and provincial taxes, withholding obligations, customs duties and sector-specific incentives before committing capital.
5. Infrastructure and operating costs
An attractive investment proposition depends not only on headline incentives but also on electricity, logistics, labor, financing, connectivity and supply-chain costs.
6. Exit strategy
Investors should establish how capital can be repatriated, shares transferred and profits distributed before entering the market.
Pakistan’s Investment Push Extends Beyond the United States
The latest initiative is part of a wider effort to attract overseas Pakistani capital.
Earlier in September 2026, Economic Affairs Minister Ahad Cheema directed officials to develop a structured mechanism through which overseas Pakistanis could participate in viable infrastructure projects, including potential opportunities involving railways, highways, power, civic infrastructure and airports.
In July, Planning Minister Ahsan Iqbal also invited Pakistani-American entrepreneurs, technologists and financiers in Chicago to bring capital, expertise and global networks to Pakistan’s economic development.
This indicates that the September 24 appeal is not an isolated announcement but part of a broader government effort to engage overseas Pakistanis and international investors.
The Bigger Question: Can Investment Follow the Outreach?
The government’s challenge is to convert investment invitations into bankable projects and completed investments.
That requires more than announcements. Investors typically assess regulatory predictability, taxation, currency convertibility, infrastructure, security, financing costs, market size, contract enforcement and the ability to repatriate returns.
The U.S. State Department’s investment-climate assessment has previously identified challenges in Pakistan including regulatory complexity, intellectual-property concerns, changing taxation policies and security-related investor concerns. At the same time, it noted that U.S. companies operate profitably in several Pakistani sectors and that there are no restrictions specifically targeting U.S. investors.
That combination—investment opportunity alongside identifiable investment risks—is important context when assessing the latest government outreach.
What Comes Next for Pakistani-American Investment
Prime Minister Shehbaz Sharif’s September 24 appeal places Pakistani-American businesses at the center of Pakistan’s effort to attract additional investment.
The sectors discussed—AI, IT, energy, automobiles, construction and agriculture—cover both emerging technologies and established parts of the economy.
Pakistan’s investment framework, expanding diaspora-focused initiatives and continuing U.S.-Pakistan economic engagement could provide additional channels for investment. However, the eventual impact will depend on whether proposed opportunities develop into commercially viable projects and whether investors find the regulatory and economic environment sufficiently predictable.
For Pakistani-American entrepreneurs, the latest message from Islamabad is therefore straightforward: the government wants greater diaspora participation not only through remittances, but also through entrepreneurship, capital, technology and long-term investment.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
WASHINGTON — Newly disclosed federal financial records show that investment accounts belonging to President Donald Trump underwent an aggressive portfolio restructuring in July 2026, logging 1,156 individual securities transactions valued between $79 million and $270 million.
While headline attention has focused on multi-million-dollar sales of artificial intelligence and mega-cap tech leaders—including Microsoft, Amazon, and Meta Platforms—a comprehensive examination of the filings reveals a more complex strategy: a transition driven by automated index rebalancing, defensive fixed-income allocation, and concurrent dip-buying.
Executive Overview: July 2026 Disclosure Breakdown
According to analysis of official filings submitted to the U.S. Office of Government Ethics and reported by CNBC, total purchases across the eight managed accounts exceeded total sales.
| Category | Aggregate Value Range | Key Assets / Companies Involved |
| Total July Transactions | $79 Million – $270 Million | 1,156 total trades logged across 8 accounts |
| Total Purchases | $43.6 Million Minimum | Municipal bonds, short-term ETFs, Broadcom, Nvidia |
| Total Sales | $35.6 Million Minimum | Microsoft, Amazon, Oracle, Meta, Northrop Grumman |
| Primary Liquidation Event | July 20, 2026 | Multi-million dollar trims in $MSFT and$AMZN ($5M–$25M bracket each) |
| Quick Re-Entry Trades | July 23, 2026 | Modest buybacks in $MSFT ($100K–$250K) and$AMZN ($1K–$15K) |
Dissecting the Big Tech Trims: Algorithmic Rebalancing vs. Market Sentiment
The largest individual entries in the September filing occurred on July 20, 2026, when investment managers executed broad sell-offs in major cloud and AI infrastructure vendors.
As reported by Quartz, individual sell orders for Microsoft and Amazon each landed in the $5 million to $25 million filing bracket. Simultaneously, managers offloaded between $1 million and $5 million in Oracle stock, alongside position trims in Meta Platforms, Alphabet, and Nvidia.
However, reporting focused exclusively on liquidations misses the broader picture:
- Simultaneous Accumulation: On the very day managers sold Oracle, they added $500,000 to $1 million in Nvidia, while opening $1 million to $5 million positions in enterprise software giants like Salesforce, Intuit, and Marvell Technology.
- Immediate Re-entry: Just three days after the July 20 sell-off, the accounts repurchased positions in Microsoft ($100,001–$250,000 range) and Amazon ($1,001–$15,000 range).
- Fixed-Income Pivot: Significant capital was rotated into defensive yield assets, including the Vanguard Short-Term Bond Index ETF, State Street SPDR Bloomberg International Treasury Bond ETF, and local government bonds such as Miami-Dade County aviation paper.
Financial analysts noted in coverage by Livemint that these multi-directional trades mirror index-tracking models adjusting for market weightings rather than a deliberate directional bet on the tech sector.
White House Clarification: Automated Model Portfolios
Trading volume of this scale by a sitting U.S. president inevitably draws regulatory and public scrutiny. Addressing the disclosures, White House spokesperson Davis Ingle emphasized that the President maintains no personal involvement in daily trade execution.
“The President’s investment portfolio is managed by independent third-party financial institutions through automated model portfolios benchmarked to broad indices like the Schwab 1000,” White House officials stated. “Trading decisions are algorithmically executed without input, direction, or prior knowledge from the President or his family.”
Unlike past presidential administrations that placed assets into blind trusts or single-index mutual funds, the current arrangement relies on third-party wealth managers utilizing direct indexing models.
Regulatory Scrutiny and Geopolitical Overlap
Despite White House assurances, the timing of specific trades has drawn criticism from Capitol Hill.
On July 20, the same day managers sold $250,000 to $500,000 worth of defense contractor Northrop Grumman, President Trump signed an executive order tightening supply chain mandates for defense suppliers and restricting critical material sourcing from foreign nations.
According to government oversight documents cited by Bloomberg, congressional lawmakers—including Senator Elizabeth Warren—have submitted formal inquiries demanding full transparency regarding the identity of the third-party money managers overseeing the accounts to rule out insider conflicts of interest under U.S. Securities and Exchange Commission rules.
Key Takeaways for Market Observers
- Net Buyer Status: Despite headline sales in Big Tech, Trump’s accounts were overall net buyers in July, adding at least $43.6 million in assets.
- Broad Sector Diversification: Capital moved away from concentrated cloud computing mega-caps into short-duration fixed income, municipal bonds, and specialized semiconductor stocks.
- Systemic Model Management: The rapid buy-sell cycles (such as selling and repurchasing Microsoft within 72 hours) strongly align with algorithmic portfolio rebalancing rather than strategic macroeconomic forecasting.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

Sovereign AI Strategies Around the World in 2026

Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off

Why Is My Social Security Payment Late? What to Check Before Calling SSA

Bitcoin ETF Outflows: Has Institutional Demand Really Turned?

Xbox Nano Controller 2026: $49.99 Price, Features, November Release

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
Why Is My Social Security Payment Late? What to Check Before Calling SSA
Bitcoin ETF Outflows: Has Institutional Demand Really Turned?
Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off
Sovereign AI Strategies Around the World in 2026
-
Digital6 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital6 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China6 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools