Analysis
How the UK’s Earned Settlement Model Will Reshape SME Hiring Plans in 2026 and Beyond

There is a particular kind of policy that arrives dressed as housekeeping but lands like a structural shock. The UK Government’s Earned Settlement consultation, which closed in February 2026 and is now moving toward implementation, is precisely that kind of measure. On its surface, it looks like an orderly recalibration of how migrants earn the right to remain—an administrative tightening after years of critics decrying what they called an “automatic” route to settlement. In practice, it may well constitute the most consequential immigration reform for small and medium-sized enterprises since the Points-Based System replaced free movement in 2021.
Understanding how the UK’s Earned Settlement model will impact hiring plans for SMEs requires more than a quick skim of the policy’s headline numbers. It demands grappling with the cascading economics of talent retention, the geography of UK business, and the uncomfortable truth that the labour migration system has quietly become load-bearing infrastructure for a significant portion of British enterprise.
The Architecture of Earned Settlement: What Has Actually Changed
The old framework was straightforward, if imperfect: five years of lawful residence, largely free of conditions beyond basic compliance, and you qualified for Indefinite Leave to Remain. The new model is something altogether more elaborate—a points-style scoring system layered onto the settlement pathway itself, long after a worker has already navigated visa applications, sponsor licensing, and the cost of entry.
Under Earned Settlement, the baseline ILR qualifying period rises from five to ten years. That doubling is the headline. But the real complexity lies in how the period can be compressed or extended based on a matrix of factors:
- Earnings above £50,270 (roughly the 80th percentile of UK wages): qualifying period reduced by up to five years
- Earnings above £125,140 (the additional-rate tax threshold): reduced by up to seven years, potentially restoring something close to the old timeline
- English proficiency at B2 or C1 (Cambridge/IELTS equivalents): further positive weighting
- National Insurance contributions of £12,570+ per annum for three or more years: additional credit toward earlier settlement
- Use of public funds: penalties of +5 to +10 years added to the baseline
- Occupation classification: workers in medium-skilled roles (RQF Level 3–5—think technicians, associate professionals, skilled tradespeople) face a maximum qualifying period of fifteen years
- Dependants: assessed separately, with their own earnings and contribution matrix
The Home Affairs Committee’s March 2026 report flagged significant concerns about the retroactive dimension: existing visa holders who structured their lives around a five-year pathway to settlement may now find the rules rewritten around them mid-journey. The legal and ethical complexity here is substantial. But it is the economic complexity—particularly for the 1.4 million SMEs that collectively employ around 16 million people in the UK—that has been most conspicuously underexamined.
The SME Cost Equation: Sponsorship Is Now a Much Longer Bet
To understand the Earned Settlement impact on SME hiring, you have to start with what sponsorship already costs before the new model arrived.
A Skilled Worker visa sponsorship licence runs between £536 and £1,476 to obtain. The Certificate of Sponsorship is another £239. The visa application itself, for a worker outside the UK, costs between £610 and £1,235 depending on length and fast-track options. The Immigration Skills Charge—levied annually on the sponsor, not the applicant—runs £364 per year for small businesses or £1,000 per year for medium and large ones. Over a five-year sponsorship, a medium-sized enterprise was therefore paying between £5,000 and £6,500 per sponsored worker in direct costs alone, before accounting for legal advice, HR time, and the compliance infrastructure that a sponsor licence demands.
Now model what happens under Earned Settlement.
For an RQF Level 3–5 worker—a dental technician, a data analyst in a regional firm, an engineering technician at a manufacturing SME—the pathway to ILR extends to fifteen years. The worker remains on Skilled Worker visa extensions, each requiring renewal fees, for potentially a decade and a half. The total direct cost to a medium business for that sponsorship journey rises to somewhere between £15,000 and £22,000 per worker, based on current fee structures and the assumption of three to four visa cycles before settlement eligibility.
That is not a rounding error. For a 50-person SME with five sponsored employees in mid-skilled roles, the aggregate compliance and fee burden over a decade could exceed £100,000—a figure that, for most small businesses, competes directly with equipment investment, workforce development, or export market expansion.
The Migration Observatory at Oxford University has long warned that immigration policy carries disproportionate costs for smaller firms, which lack the in-house legal departments and HR bandwidth of FTSE-listed employers. The Earned Settlement framework, whatever its merits as an integration policy, compounds this structural disadvantage substantially.
The Talent Flight Risk: Why the Best People May Simply Leave
Here is a dynamic that has received almost no serious coverage in the policy debate so far: Earned Settlement does not prevent emigration. It only makes UK settlement more conditional and more distant. And in a world where Australia, Canada, Germany, and the Netherlands are actively competing for the same mid-skilled and specialist workers that UK SMEs rely on, extending the settlement pathway by a decade creates a powerful incentive for exactly the workers SMEs most want to keep.
Consider the mathematics from a worker’s perspective. A Filipino nurse who arrived in the UK in 2022 to take up an RQF Level 5 role in a private care home had a reasonable expectation of ILR by 2027, followed by British citizenship eligibility by 2029. Under retroactive Earned Settlement application—which the consultation strongly implies but has not definitively confirmed—her pathway might now stretch to 2037. Canada’s Express Entry system, by contrast, can offer permanent residency within six to twelve months for applicants with her qualifications and work history.
This is not a hypothetical. The Financial Times has reported extensively on the UK’s intensifying competition with Canada and Australia for international health and care workers. Germany’s new Chancenkarte (Opportunity Card) system is explicitly designed to attract exactly the mid-skilled international workers that the UK’s new policy treats most harshly. The UK, in tightening its settlement route, is simultaneously loosening the golden handcuffs that made long-term commitment here attractive.
For SMEs in social care, hospitality, construction, and technology—sectors where international recruitment is not a supplement to domestic hiring but a structural necessity—this creates a dual retention crisis: attracting workers becomes harder because the settlement offer is less competitive, and retaining workers beyond year three or four becomes harder as alternative permanent residency offers materialise elsewhere.
Sector-Specific Pressures: A Regional Story Nobody Is Telling
The UK ILR changes in 2026 will not be felt evenly across the economy. London firms—particularly in professional services, finance, and tech—sponsor primarily at RQF Level 6 and above, and their workers’ earnings frequently breach the £50,270 threshold that compresses the qualifying period back toward five years. In other words, high-earning workers in high-cost cities are largely insulated from the reform’s sharpest edges.
The pain lands hardest in regional SMEs. A precision engineering firm in Wolverhampton, a food processing operation in Lincolnshire, a care home group in Tyneside—these businesses sponsor at RQF Levels 3–5, pay wages that rarely breach £35,000 to £40,000, and operate in labour markets where domestic recruitment has been functionally exhausted. For them, the fifteen-year qualifying period is not a marginal inconvenience. It is a structural barrier that will, over time, price international talent entirely out of reach.
This has macroeconomic consequences that the policy’s architects appear to have underweighted. The UK’s regional productivity gap—already a defining structural weakness of the British economy—is significantly exacerbated when the SMEs that anchor regional economies face hiring constraints that their London counterparts do not. If mid-skilled Skilled Worker visa settlement changes for SMEs in 2026 push regional businesses toward workforce contraction rather than expansion, the downstream effects on local tax bases, supply chains, and community economic activity could be substantial.
The Office for Budget Responsibility has, in successive forecasts, noted that labour supply is among the primary constraints on UK growth. A policy that systematically reduces the attractiveness of the UK as a long-term destination for mid-skilled workers tightens exactly that constraint, at exactly the moment the economy can least afford it.
The Strategic Pivot: What Smart SMEs Are Already Doing
The firms that will navigate this best are not those that lobby against the policy—that battle is, for now, lost—but those that restructure their workforce strategy around the new environment. Several approaches are emerging among the more forward-thinking SME operators:
1. Wage engineering toward the £50,270 threshold The single most powerful lever within the Earned Settlement matrix is the first earnings threshold. Crossing £50,270 halves the baseline qualifying period. For workers earning £42,000 to £48,000, an SME that moves them to £50,270—often achievable through restructured pay, modest uplifts, or genuine productivity-linked progression—dramatically reduces both the worker’s settlement timeline and, by extension, the employer’s retention risk. This is not generous pay strategy; it is rational workforce economics.
2. Segmented workforce planning by RQF level SMEs that currently mix RQF Level 3–5 and Level 6+ roles in undifferentiated hiring plans need to disaggregate urgently. Roles that can be upskilled or reclassified to Level 6—through qualifications investment, professional registration, or job redesign—carry far more favourable settlement terms. The cost of funding an employee’s professional qualification may be substantially lower than the cumulative retention cost of running a fifteen-year sponsorship.
3. Front-loading compliance infrastructure The Immigration Skills Charge and sponsorship fees are unavoidable, but the compliance burden—the HR administration, the annual monitoring, the legal review—is heavily elastic. SMEs investing now in compliance software, digital right-to-work systems, and HR training will amortise those costs over the extended sponsorship periods that Earned Settlement creates. Those that do not will pay disproportionately in crisis compliance later.
4. Immigration cost as a line item in business planning This sounds elementary, but a striking number of SMEs still treat UK immigration reforms and SME retention costs as ad hoc, reactive expenses rather than forecast items. The new environment demands that sponsors model ten-to-fifteen-year cost trajectories for international hires with the same rigour applied to capital expenditure. Businesses that embed this modelling into their strategic plans will make better decisions about when to sponsor, whom to sponsor, and when to explore domestic alternatives.
The Policy’s Own Logic: Genuine Tension, Not Simple Error
It would be intellectually dishonest to dismiss the Earned Settlement framework as simply punitive or misconceived. Its underlying rationale is coherent, if contested.
The policy’s architects—and the Home Office consultation documents are surprisingly candid about this—are attempting to create genuine integration pathways that reward fiscal contribution and social participation rather than mere physical presence. The linkage of settlement to earnings, English proficiency, and NI contributions has a reasonable integration-policy foundation. Permanent residency should arguably reflect genuine belonging, not just time-serving.
The problem is not the principle. It is the calibration, and the asymmetric application of its costs.
The workers who face the most extended pathways—mid-skilled, moderately paid, often in public-facing or care-sector roles—are frequently those whose integration has been most visible and most socially embedded. They are not abstract economic units cycling through visa categories; they are parents at school gates, members of communities, contributors to local tax bases. Extending their pathway to fifteen years is not an integration measure. It is a disincentive to the very rootedness that integration policy should be encouraging.
Meanwhile, the policy’s most favourable treatment is reserved for high earners—those least likely to need policy incentives to remain in the UK, and least likely to leave for want of a swift settlement route. The perverse outcome is a system that prioritises the settlement of those who need it least and burdens those who need certainty most.
Forward Look: What Comes Next, and What SMEs Must Demand
The Earned Settlement model, even if amended in its implementation phase, represents a durable shift in the political economy of UK immigration. The direction of travel—toward more conditional, contribution-linked settlement—is unlikely to reverse under any plausible near-term government. SMEs must plan for this world, not the previous one.
In the immediate term, the most urgent priority is legal audit: every business with sponsored workers needs to understand, precisely, where each employee sits on the new matrix. What are their projected earnings trajectories? Do they have dependent claims in progress? Are their occupation codes classified at RQF Level 3–5 or above? The answers determine not just settlement timelines but retention risk profiles.
In the medium term, the trade associations that serve UK SMEs—the Federation of Small Businesses, the CBI, the British Chambers of Commerce—need to pivot from general immigration commentary to highly specific technical engagement with the Home Office’s implementation process. The consultation has closed, but the secondary legislation and guidance that give this policy its operational teeth are still being written. Detailed business impact evidence, submitted through proper parliamentary and regulatory channels, can still shape those details.
And in the long term, the UK needs a frank national conversation about what kind of economy it wants to be. A country that educates and trains only some of the workers it needs, then makes long-term residence for the rest conditional, uncertain, and expensive, is not pursuing a coherent productivity strategy. It is managing political optics at the cost of economic coherence.
The UK’s small businesses—those 1.4 million enterprises that in many ways are the connective tissue of the real economy—did not design this policy and cannot repeal it. But they can adapt to it, challenge its worst excesses through legitimate advocacy, and insist that policymakers reckon honestly with the costs they are imposing. That insistence, forcefully expressed and backed by data, is how bad calibration sometimes becomes better policy.
The earned settlement of a sound immigration framework, it turns out, requires the same continuous effort as the earned settlement it regulates.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead.
Quick answer: India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
On November 6, 2026, Reuters reported that the Nifty 50 was up about 0.51% while the Nikkei and Kospi suffered steep declines. The immediate explanation was not that India had escaped global financial conditions. A pullback in crude prices, an improvement in foreign portfolio flows and a shift away from AI-heavy exposures created a comparatively favorable mix for Indian equities.
Foreign investors reportedly bought about 150 billion rupees of Indian shares on November 5—the largest single-day net purchase in nearly six years. That is an important flow event, but a single day of buying is not the same as a durable change in ownership or earnings expectations.
Why cheaper oil matters to India
India imports substantial crude oil, so a sustained fall in its import price can reduce pressure on the trade balance and inflation, subject to the rupee, tax policy and refinery margins. It can improve sentiment toward transport, consumption and rate-sensitive stocks. But if oil falls because global demand is collapsing, weaker exports and risk appetite may offset part of that benefit.
The World Bank expects commodity conditions to remain volatile. Investors should therefore distinguish a temporary crude-price dip from a more structural improvement in India’s energy terms of trade.
Foreign buying is a signal, not a guarantee
Global portfolio managers can rapidly shift country weights when a crowded trade sells off. India may attract allocations because of domestic demand and different index composition, but flows can reverse if currency risk rises or earnings disappoint. The market’s resilience should be judged by a series of sessions and broad participation, not one spectacular inflow.
Domestic institutional investors are an additional source of demand. When foreign and local investors take opposite sides, the effect on the index depends on sector weights, liquidity and which large companies are being traded.
The valuation question remains
An index can grow while being expensive. To assess the Nifty 50, consider forward earnings multiples, historical valuation ranges, earnings revisions and expected return on equity. A lofty multiple can be justified by robust profit growth, but its downside increases if expectations are not met. Investors should avoid comparing India’s headline P/E mechanically with markets that have very different sector mixes.
Separate earnings growth driven by real volumes, pricing and margins from one-off gains, currency translation and financing effects. The stronger investment case is one in which earnings breadth improves rather than relying on a small group of index heavyweights.
Banks and IT will determine breadth
Private banks react to loan growth, deposit pricing, asset quality and regulation. IT services companies face technology spending cycles, contracts, exchange rates and hiring demand. The same global AI shock that hurts expensive chip makers can either help IT services through workflow demand or hurt them if customers cut budgets.
Small- and mid-cap shares have different liquidity and valuation risks from the Nifty 50. A headline benchmark recovery with weak market breadth is a weaker signal than simultaneous improvement across several sectors.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | Reuters Nov 6 India markets |
| Interpretive opportunity | Oil versus foreign inflows |
| Secondary question | Sector-level breadth |
| Next verification | Update the closing index level, foreign institutional flows and USD/INR before posting. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
Capital inflows and domestic profits are separate. Foreign fund flows can move prices before the underlying corporate earnings outlook improves. Analysts should identify which signal they are discussing and why it matters. In this article’s subject—Nifty 50 today outlook—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
Headline index gains can coexist with weak breadth. If a handful of large companies drives a rally while smaller shares fall, the apparent strength is less diverse than the benchmark return suggests. Update the closing index level, foreign institutional flows and USD/INR before posting. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Oil versus foreign inflows. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Sector-level breadth. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Risk of mistaking flows for earnings. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
Three tests for the Nifty rally
Foreign inflows meet genuine earnings strength. The best case combines lower sustained energy import costs, corporate profit growth and foreign portfolio confidence. Banks would demonstrate healthy credit demand without deterioration in loan quality, while domestic consumption would support margins. The critical evidence would be several reporting periods of earnings progress, not the November 5 flow spike by itself.
A commodity or currency reversal. If crude rises again or the rupee weakens sharply, inflation expectations and foreign returns could deteriorate. Expensive equity valuations may then amplify selling even in companies with acceptable operating results. Risk is especially pronounced when a market’s recent strength rests on a narrow set of very large stocks or short-lived portfolio rotation.
The market pauses while fundamentals catch up. A long consolidation would not necessarily invalidate India’s structural investment case. It could allow earnings to grow into valuations while global investors digest the AI sell-off. Examine the direction of consensus earnings revisions, financial-sector profitability and market breadth before treating each daily Nifty movement as a turning point.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
A final distinction worth checking
India’s apparent resilience also needs sector and currency discipline. An investor who buys the Nifty in rupees but measures wealth in dollars faces both equity and foreign-exchange movements. A multinational technology exporter may respond differently from a domestic lender when the rupee or U.S. spending changes. Index breadth, banking-sector credit costs and the earnings trajectory of large consumer companies should be placed beside the November foreign-flow figures. Without this context, a sharp positive session can be mistaken for a lasting improvement in risk-adjusted returns.
Questions readers are asking
Why was Nifty stronger than Nikkei and Kospi?
Reuters cited falling oil, foreign buying and a rotation away from heavily AI-linked markets.
Is the Nifty 50 an AI index?
No. It is a diversified large-company Indian equity index with major financial, consumption, industrial and technology exposures.
Should a one-day rise be treated as a breakout?
No. Confirm trends with earnings, breadth, flows and repeated trading sessions.
What can reverse the rally?
Renewed oil inflation, rupee weakness, expensive valuations, weak earnings and abrupt foreign selling.
The judgment
India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead. The most responsible conclusion is conditional: Update the closing index level, foreign institutional flows and USD/INR before posting. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
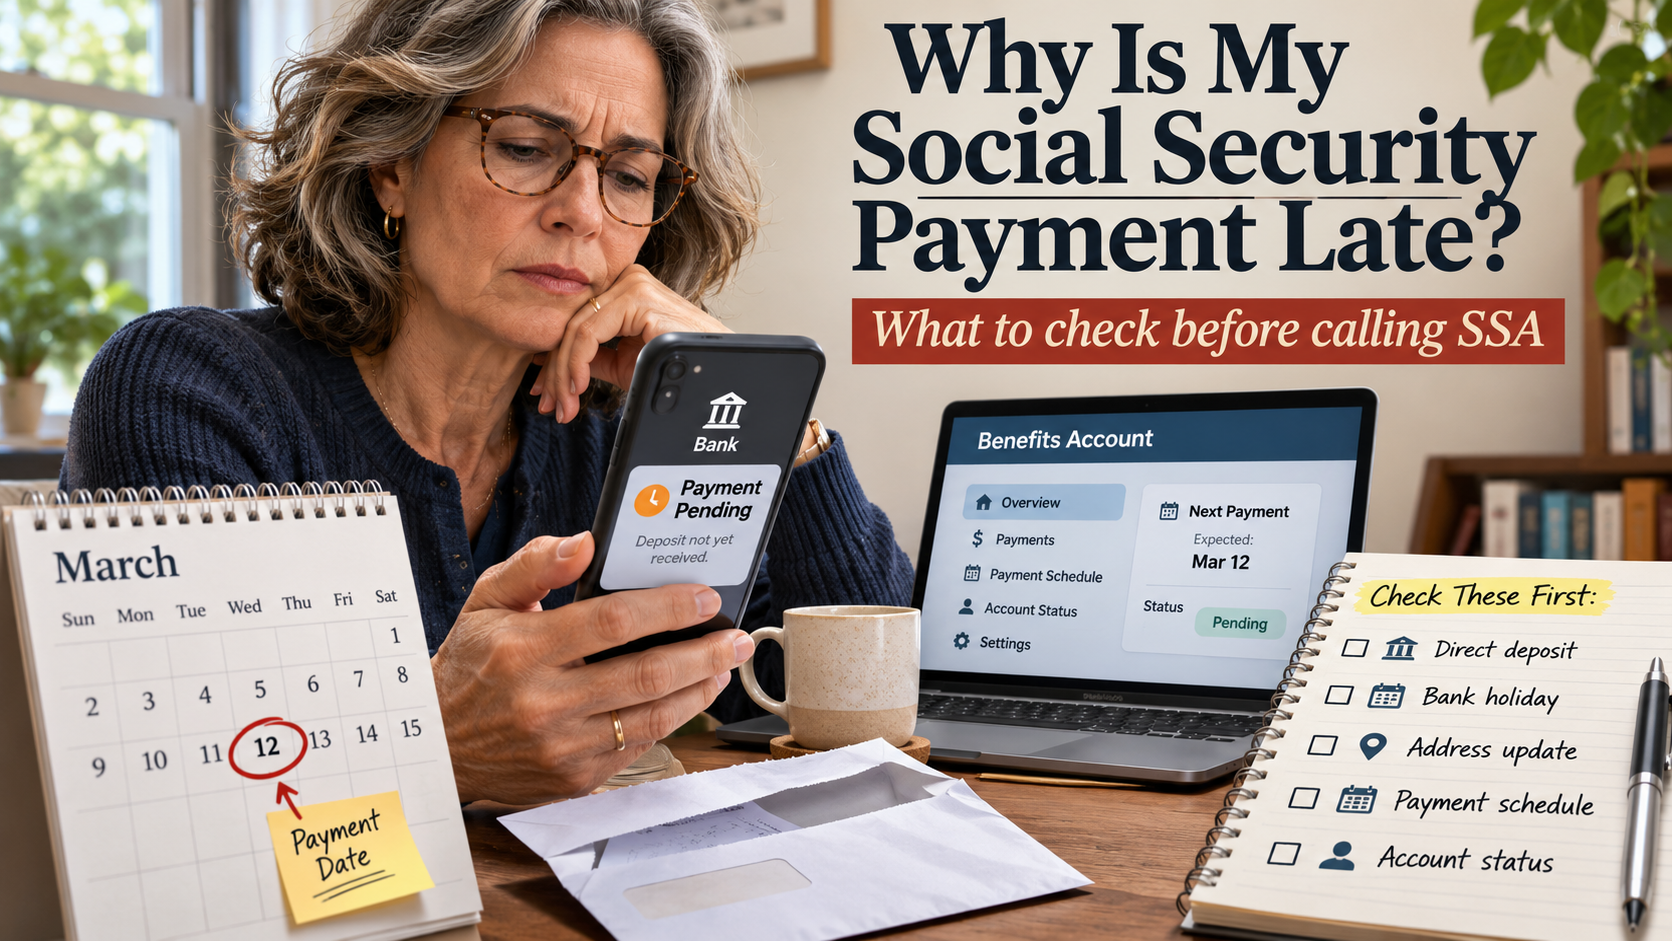
Quick answer: If your Social Security or SSI deposit has not appeared, first confirm the scheduled payment date for your program, then check with your bank or financial institution. The Social Security Administration’s missing-payment FAQ specifically says to contact your bank first for an electronic payment that does not arrive as scheduled. If the money remains missing, call SSA at 1-800-772-1213 or contact a local Social Security office. Do not pay a third party to ‘release’ your benefits.
A delayed deposit can be frightening when it is meant to cover rent, food, medicine or electricity. But the timing problem may have several explanations, and not all mean that the government has stopped the benefit. The most useful response is to determine whether the payment is not yet due, issued but not posted, sent to the wrong account, withheld after an eligibility change, or truly missing. Those categories lead to different next steps.
Step one: make sure today is really your payment date
The most common source of confusion is assuming every Social Security recipient is paid on the third of the month. In reality, the SSA’s published payment rules place most retirement, disability and survivor beneficiaries on one of three Wednesdays, generally based on the relevant birth-date category. Certain people who started benefits before May 1997, and some who receive SSI and Social Security together, have special schedules.
| Recipient category | Ordinary schedule | What to verify |
|---|---|---|
| SSI | First of the month, adjusted for weekends/holidays | Benefit month versus bank deposit date |
| Certain long-standing or dual beneficiaries | Third of the month, subject to adjustments | Whether your award follows the special cycle |
| Regular Social Security, birth date 1–10 | Second Wednesday | Holiday shifts and relevant birth date |
| Regular Social Security, birth date 11–20 | Third Wednesday | Correct calendar month |
| Regular Social Security, birth date 21–31 | Fourth Wednesday | Correct calendar month |
Consult the official benefit calendar rather than a social-media image. A chart that mechanically copies weekday patterns without considering federal holidays can misstate a particular month’s deposit date. For example, the first November 2026 Wednesday cohort was scheduled for November 10 rather than Veterans Day, November 11, under SSA’s holiday adjustment.
Step two: check holiday and weekend adjustments
When a normal payment date falls on a weekend or legal public holiday, Social Security generally issues the payment on the preceding business day. The agency’s holiday FAQ explains the principle. Consequently, a payment may show up earlier than a generic calendar suggests rather than later.
The November 2026 SSI example is instructive. Because November 1 fell on a Sunday, the SSI payment for the November benefit month was scheduled for October 30. Someone searching the bank statement only for a transaction dated November might think a payment is missing even though it arrived at the end of October. That is a question of benefit month versus calendar posting date, not necessarily entitlement.
Different banks may display transaction descriptions and posting times differently. A pending payment, an available balance and a settled transaction are not always the same entry. Use the statement details, not a push notification alone, when checking whether money arrived.
Step three: ask your bank whether a payment was received
SSA’s official advice is clear: if an electronic payment did not arrive on its scheduled date, contact your bank or financial institution first. The institution may be experiencing a delay in posting a deposit it has received. Ask whether there is a pending government benefit payment, whether there is a hold or account problem, and whether the institution has returned a transaction.
It helps to have the scheduled pay date and the last successful benefit transaction on hand. Do not assume the bank can reveal confidential SSA processing information; the bank can explain what its own systems show. If the bank sees no payment, tell SSA that you have already checked. This avoids repeatedly being sent back to the same first troubleshooting step.
If your bank account was recently closed or changed, the payment could have been rejected or returned. The SSA direct-deposit update FAQ describes how recipients can update relevant information, with different options for Social Security versus SSI. Never email complete bank details to an unsolicited address or disclose credentials to someone who calls unexpectedly.
Step four: use SSA’s official missing-payment reporting channel
If the bank cannot resolve the problem and the money is genuinely missing, contact the Social Security Administration. The missing-payment FAQ gives the number 1-800-772-1213 and the TTY line 1-800-325-0778, along with the option to contact a local office. SSA says it will review a qualifying missing-payment report and replace payment if it is due.
When contacting the agency, prepare the benefit type, scheduled pay date, the payment amount you expected, a brief description of what the bank told you and whether you changed accounts. You may need to verify your identity through an official process. The purpose is to give the representative enough information to investigate without sharing sensitive details through insecure channels.
A key distinction is between a payment the agency issued but you did not receive and a payment the agency has not authorized because of a change in eligibility or other adjudicated matter. The remedy for an issued-and-lost deposit is not necessarily the same as the appeal or correction process for a change in benefits.
What if my benefit amount changed rather than disappeared?
A smaller payment can feel like a missing payment when you budget a fixed amount. But Social Security deposits can reflect Medicare premium deductions, tax withholding, repayment of overpayments, adjustments to benefits and other legally applicable changes. SSI payments can also change with income, resources or living arrangements.
Check your most recent award or adjustment notice in your secure my Social Security account if your benefit type permits the relevant online service. Compare the gross entitlement with the net bank deposit. If the gross benefit has changed, ask what notice or determination supports the new amount. If only deductions changed, identify each one before assuming the benefit was reduced arbitrarily.
A person who receives both Social Security and SSI should check each benefit independently. For example, an increase in countable Social Security income may affect the SSI component under means-testing rules. Two deposits can move in different directions without there being a computer error. The SSA overview of SSI explains that income and living circumstances can change payment amounts.
What if the deposit goes to an old bank account?
Contact both your bank and SSA through verified channels. An account closure or change can cause a government deposit to be returned, which may require a reissue after the information is corrected. Do not assume transferring your ordinary paycheck to a new account also updates the Social Security benefit instructions.
The SSA’s direct deposit guidance notes that many retirement, survivors and disability recipients can use their personal online account to change banking information. The same online self-service functionality is not available for all SSI users, who may need to call or visit an office. That difference matters if an article promises one-click bank changes to everyone.
Before submitting a change, review the routing and account number carefully on a legitimate banking document. A single incorrect digit can cause a failure that takes time to investigate. If someone pressures you to reroute a benefit into an account that is not yours, treat that as a fraud warning and contact SSA directly.
How long should I wait before reporting a late payment?
The practical answer is: follow the agency’s current missing-payment instructions. The SSA FAQ asks electronic-payment recipients to contact their bank on the scheduled date if the payment is missing, then reach SSA if necessary. It does not instruct everyone to wait an arbitrary three or five business days before making any inquiry. If a new claim is involved, different processing and notification timelines may apply.
If the missing payment creates urgent hardship, explain that when you contact the agency. An inquiry may not produce an immediate replacement, but a clear description helps the agency understand the consequences. Seek local emergency assistance if you cannot obtain essentials while the problem is investigated; do not turn to a supposed ‘SSA release fee’ offered by a stranger.
Can scams look like payment problems?
Yes. Fraudsters often use worries about a missing deposit to lure victims into clicking links or revealing identification numbers, one-time passcodes and bank details. They may falsely claim a payment is frozen pending a small fee. Official government sites, including SSA’s account portal, should be accessed by typing the address directly or using a saved trusted bookmark.
SSA does not require you to pay a social-media account or intermediary to speed up a routine missing-payment report. Avoid handing over your entire banking login to anyone promising a quicker resolution. Preserve screenshots of suspicious messages if you need to report them, but do not forward sensitive attachments to unknown addresses.
A payment-troubleshooting checklist
Before making the call, write down these five answers: (1) Which program pays you? (2) What is the scheduled date according to SSA? (3) Did the calendar move that date because of a holiday? (4) What does your bank show? (5) Has your address, account or benefit entitlement changed? The sequence stops a simple calendar adjustment from escalating into an unnecessary dispute, while making genuinely missing payments easier to explain.
Keep copies of formal notices and bank transaction entries, but redact sensitive personal numbers if seeking help from a third party. A caregiver assisting another person should also follow SSA’s authorization rules and avoid impersonating the beneficiary during an inquiry.
Frequently asked questions
Why has my Social Security payment not arrived today?
It may not be your scheduled date, the bank may not have posted the payment yet, or SSA may need to review a bank-account or entitlement issue. Verify the schedule, then contact the bank and SSA if needed.
Who should I call first for a missing direct deposit?
SSA’s FAQ recommends contacting the bank first, followed by SSA at 1-800-772-1213 if the problem remains unresolved.
Can SSI be paid in the previous month?
Yes. If the first falls on a weekend or holiday, the monthly SSI payment may arrive on the prior business day, as happened for November 2026.
Does a smaller deposit mean SSA stopped my benefits?
Not necessarily. A deduction or an eligibility-related adjustment can change the net payment. Review notices and distinguish the gross award from the deposited amount.
Can I change my direct deposit online?
Many retirement, survivors and disability beneficiaries can, but online options differ for SSI. Follow SSA’s official instructions.
Bottom line
When a Social Security payment seems late, a measured sequence is more effective than panic or rumors: confirm the official date, check the bank’s posting, inspect notices and then report the problem through SSA. A correct diagnosis protects both your household budget and your personal information. A missing deposit deserves prompt attention, but it should not be confused with a benefit that was issued on a different calendar date.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
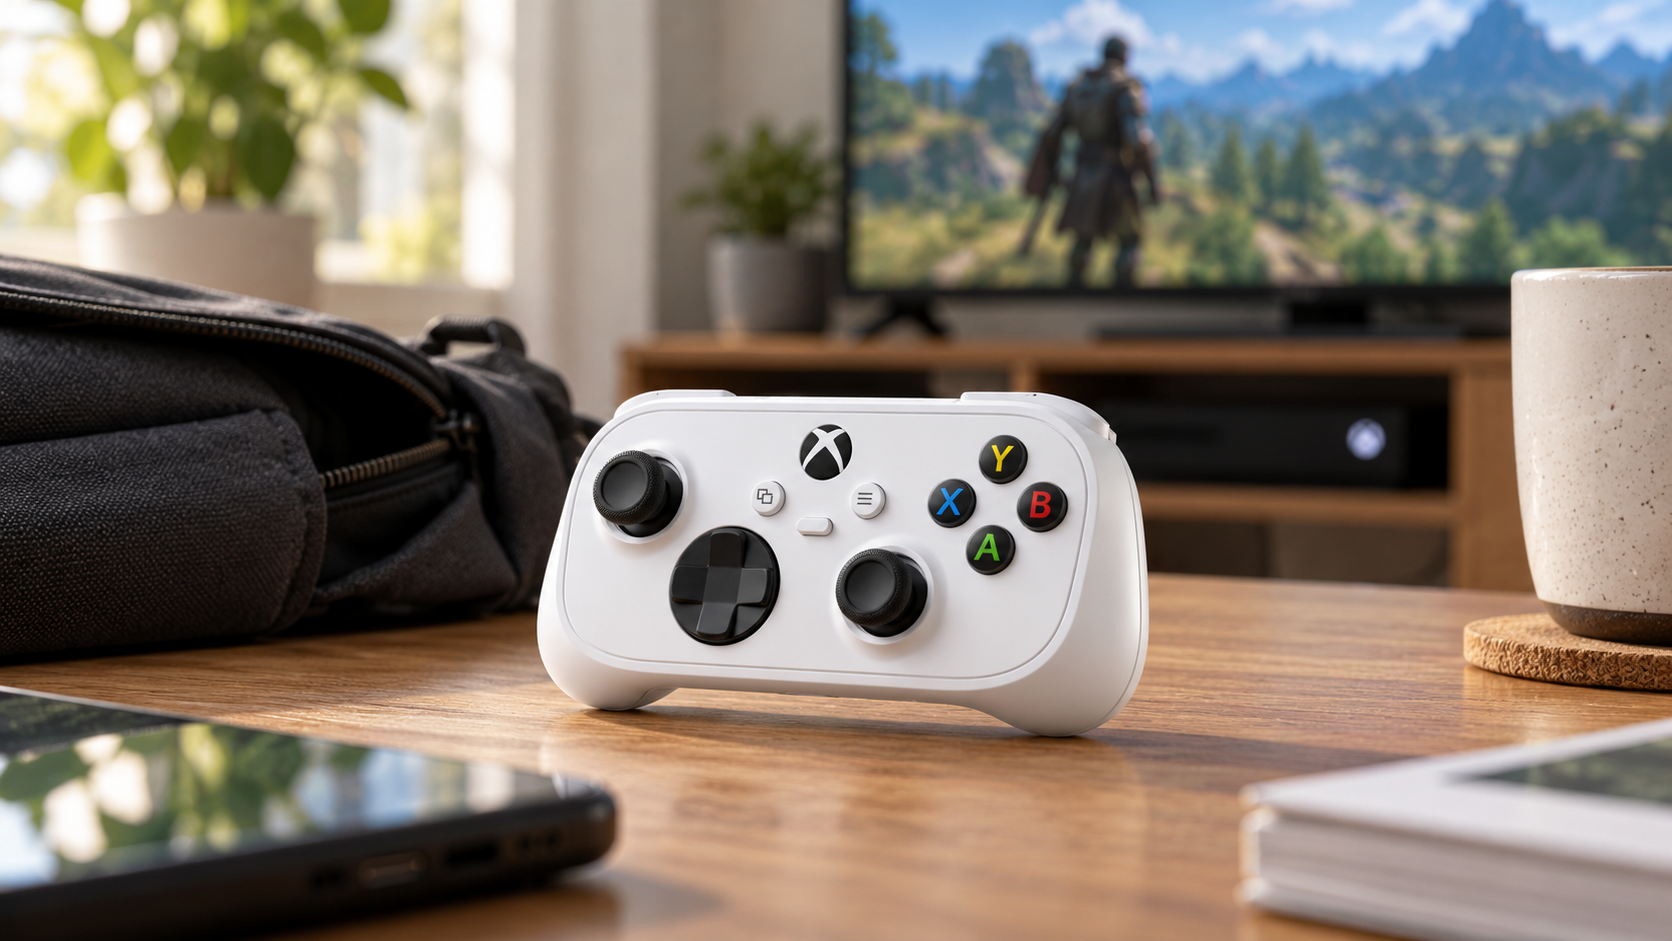
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. For primary-source background, consult Xbox Wire official announcement; Xbox official specification page; Microsoft Store US. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What Microsoft actually announced
The Xbox Wire announcement places the controller at a little over five inches long and approximately 3.5 ounces. Microsoft says it retains 18 standard gameplay inputs despite the smaller chassis. Its list price is $49.99 USD, though local prices and availability differ. It also reports a rechargeable internal battery and a programmable Action Button for tasks such as capturing screenshots or gameplay. This is a real official product launch, not a rumor based on leaked images. Product listings and availability should be checked for the buyer’s country.
Who benefits from a smaller controller
Small-hand ergonomics may be useful for some adults and younger players, but one size does not fit everyone. Grip diameter, shoulder-button reach, thumbstick placement and hand fatigue can matter more than weight alone. A tiny controller may be convenient in a bag but less comfortable during extended sessions for some users. A good review therefore evaluates real people with different hand sizes rather than calling compactness universally better. For parents, compatibility with age-appropriate games and device setup is part of the purchase decision. A low sticker price does not remove the need for usability testing.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026.
Wireless support and device compatibility
Microsoft says the Nano supports Xbox Wireless with compatible consoles and Bluetooth with supported PCs, mobile devices, tablets and smart TVs. That does not mean every game on every device is compatible. Operating-system support, cloud-play subscription availability and game-specific controller input differ. Players should inspect Microsoft’s compatibility notes before purchase, particularly for smart TVs or mobile games that require touch input. The internal battery uses USB-C charging, but the product page notes that the charging cable may be sold separately. Such minor accessories are relevant to total cost and should be visible in product comparisons.
Battery, Action Button and trade-offs
A built-in rechargeable battery changes ownership convenience compared with controllers that use replaceable cells, but it does not guarantee a particular play time. Battery duration depends on wireless mode, features and conditions. Microsoft has not established every real-world endurance result in the launch announcement, so editors should wait for independent testing before making precise claims. The programmable Action Button could reduce menu navigation for popular tasks, but users should verify exactly which shortcuts are available in supported software. Standard inputs may preserve familiar gameplay while smaller thumbstick travel or grip could affect precision; these are review questions, not proven flaws.
Is $49.99 good value?
Value depends on the buyer’s existing devices, preferred games and ergonomics. Someone who already owns a comfortable full-size controller may gain portability without needing to replace their main controller. A family seeking a second or third controller may prioritize price and consistent wireless pairing. A competitive player might instead favor adjustable controls, wired latency or premium hardware that the Nano does not claim to provide. Compare after-sales warranty, charging accessory costs, import taxes, local support and return rules. The launch is best understood as a compact mainstream option, not a universal upgrade from every other Xbox controller.
Worked example: how to interpret a difficult headline
Two buyers can reach different conclusions at the same price: a traveler wanting a lightweight Bluetooth controller may value the smaller form factor, while someone who plays long racing sessions on a console may prefer a larger grip. A useful review explains this trade-off rather than ranking products solely by price or feature count. Check a local store’s return policy in case the fit is unsuitable. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Official Xbox Nano | Small, $49.99 list price, rechargeable and portable. |
| Full-size standard controller | Potentially different hand fit and battery arrangements. |
| Premium controller | May add advanced customization at a higher price. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- November 2026 retail availability and regional pricing.
- Independent battery-life and ergonomic testing.
- Compatibility changes via software updates.
- Store returns, warranty and accessory requirements.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
Specifications make the Nano controller appealing, but personal hand fit, device compatibility, charging accessories, and return policy determine its value. The editorial differentiator is a use-case comparison rather than a copied feature list or an unsupported claim about measured latency.
Frequently asked questions
What is the Xbox Nano price?
Microsoft lists $49.99 USD before location-specific taxes and differences. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
When does Xbox Nano launch?
Microsoft describes November 2026 availability, with a specific November 4 date on its US store listing. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it have all the standard buttons?
Microsoft says it includes 18 standard gameplay inputs. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it work on PC and phones?
It supports Bluetooth on compatible devices; verify software and game compatibility. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

Sovereign AI Strategies Around the World in 2026

Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off

Why Is My Social Security Payment Late? What to Check Before Calling SSA

Bitcoin ETF Outflows: Has Institutional Demand Really Turned?

Xbox Nano Controller 2026: $49.99 Price, Features, November Release

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
Why Is My Social Security Payment Late? What to Check Before Calling SSA
Bitcoin ETF Outflows: Has Institutional Demand Really Turned?
Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off
Sovereign AI Strategies Around the World in 2026
-
Digital6 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital6 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China6 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools