Analysis
Dubai’s Tech Revolution: 15 Startups Reshaping the Middle East’s Business Landscape

How the Desert City Became MENA’s Unicorn Factory—And Why Silicon Valley Should Pay Attention
The morning sun glints off the Burj Khalifa as Tabby’s co-founder Hosam Arab checks his phone. Another $160 million just landed in the company’s Series E round, pushing valuation to $3.3 billion. It’s not a miracle—it’s Tuesday in Dubai, where billion-dollar startups are becoming as common as sandstorms.
Welcome to the Middle East’s most unlikely tech hub, where fifteen startups are proving that innovation doesn’t require hoodie-clad college dropouts in Palo Alto. With $2.4 billion raised in the first half of 2024 alone and twelve unicorns calling the UAE home, Dubai has quietly built what Saudi Technology Ventures calls “the billion-dollar corridor” of the MENA region.
This isn’t your grandfather’s oil economy. This is something far more disruptive.
Beyond Oil: Dubai’s Economic Metamorphosis
The UAE aims to nurture ten unicorns by 2031, but they’re already halfway there. The transformation from petroleum-dependent economy to tech powerhouse didn’t happen by accident. It required vision, infrastructure, and billions in strategic investment.
The numbers tell a compelling story. In the first half of 2025, UAE startups raised more than $2.1 billion, a 134 percent increase year over year, placing the Emirates ahead of established ecosystems like Japan and Sweden. Dubai accounts for more than 90 percent of this deal flow, cementing its position as the region’s undisputed innovation capital.
What makes Dubai different? Start with government backing that would make any Silicon Valley founder jealous. The Emirates Development Bank offers financing of up to AED 5 million for tech startups, complemented by incubation hubs like in5, Flat6Labs, Astrolabs, and Abu Dhabi’s Hub71. The Mohammed Bin Rashid Innovation Fund provides accelerator placement with mentorship and flexible government-backed loan guarantees.
But money alone doesn’t build unicorns. Dubai’s strategic advantages run deeper: zero capital gains tax, 100 percent foreign ownership in free zones, long-term golden visas for entrepreneurs, and a location that bridges three continents and 2 billion consumers. Add world-class infrastructure, political stability in an often-turbulent region, and aggressive regulatory sandboxes for fintech and emerging tech—suddenly, the exodus from Cairo and beyond makes perfect sense.
The 15 Startups Rewriting MENA’s Future
The Fintech Disruptors
1. Tabby — The MENA Buy-Now-Pay-Later Juggernaut
Tabby reached a $3.3 billion valuation in February 2025 after securing $160 million in Series E funding, making it the most valuable venture capital-backed fintech in the Middle East and North Africa. Founded in 2019 by Hosam Arab, Tabby has grown from a shopping installment service to a comprehensive financial services platform serving over 15 million users across Saudi Arabia, the UAE, and Kuwait.
The company’s trajectory is staggering. Tabby collaborates with over 40,000 brands, including Amazon, Samsung, and Noon, driving approximately $10 billion in annual sales. In December 2023, it secured $700 million in debt financing through a receivables securitization agreement with JP Morgan, demonstrating institutional confidence in its business model.
Tabby’s secret? It tapped into a massive underserved market where credit card penetration remains low and cash still dominates. By offering Shariah-compliant financing and frictionless checkout experiences, Tabby solved a uniquely Middle Eastern problem with globally competitive technology. Now, with an IPO in Saudi Arabia on the horizon, the company is positioning itself as the region’s answer to Affirm and Klarna.
2. Careem — From Ride-Hailing Pioneer to Super App
Before there was Uber in the Middle East, there was Careem. Founded in 2012 by Mudassir Sheikha and Magnus Olsson, Careem became the first unicorn exit in the MENA region when Uber acquired it for $3.1 billion in March 2019, marking the largest technology sector transaction in Middle Eastern history.
Careem has raised $771.7 million over ten rounds, and post-acquisition, it hasn’t stood still. The platform has evolved into a super app incorporating payments, food delivery, grocery services, and even home cleaning and PCR testing. Operating across ten countries with 5,500 employees, Careem processes millions of transactions monthly.
What sets Careem apart isn’t just its ride-hailing technology—it’s cultural adaptation. The company addressed region-specific challenges: female-only driver options in Saudi Arabia, cash payment dominance, areas with no formal addressing systems. This localization strategy proved that understanding your market beats copying Silicon Valley playbooks.
3. YAP — Democratizing Digital Banking
Founded by Marwan Hachem and Anas Zaidan, YAP aims to eliminate the need for multiple bank accounts or various financial apps to manage personal finances. Launched in 2021 in partnership with RAKBank, YAP raised $41 million to expand into new markets and enhance its technology offerings.
In a region where traditional banking often means lengthy paperwork and minimum balance requirements, YAP offers something revolutionary: instant account setup, no minimum balances, spend analytics, and seamless international transfers. The all-in-one money app targets the region’s massive youth population—60 percent of the MENA population is under 30—who expect banking to feel like using Instagram, not visiting a government office.
The E-Commerce Titans
4. Noon — The Amazon of the Middle East
Mohammed Alabbar didn’t build Emaar Properties—creator of the Burj Khalifa—by thinking small. When he launched Noon in 2016 with $1 billion in initial funding and Saudi Arabia’s Public Investment Fund holding 50 percent, the ambition was clear: dominate Middle Eastern e-commerce before Amazon could.
Noon’s most recent valuation was near $10 billion and it has previously raised about $2.7 billion. In December 2024, the company secured an additional $500 million from investors including the PIF, advancing preparation for a potential IPO. Operating an online marketplace, grocery delivery, and food delivery services across Saudi Arabia, the UAE, and Egypt, Noon has become the region’s default e-commerce platform.
The company’s success stems from solving logistics challenges unique to the Gulf: same-day delivery in extreme heat, cash-on-delivery preferences, multilingual customer service, and building trust in a market skeptical of online shopping. Where Amazon struggled with regional nuances, Noon thrived.
5. Dubizzle Group — MENA’s Classifieds King
Founded in 2015, the Dubizzle Group attained unicorn status in 2020 and employs about 5,500 people working in ten different countries. The umbrella corporation owns and operates classified portals including Bayut, Zameen, and OLX across emerging markets, primarily serving the real estate industry.
Dubizzle Group has raised $479 million over six rounds, with its latest Series F securing $200 million in October 2022. The platform has become the go-to marketplace for buying, selling, or renting homes, cars, and household goods across the MENA region.
What makes Dubizzle remarkable is its hyperlocal approach. Rather than imposing a one-size-fits-all model, the group adapts each brand to local market dynamics, regulatory environments, and consumer behaviors. This “glocal” strategy—global technology, local execution—has proven devastatingly effective in fragmented markets.
The Cloud Kitchen Revolutionary
6. Kitopi — Scaling Restaurants at Digital Speed
Kitopi has raised $802.2 million over five rounds, achieving unicorn status at a $1 billion valuation in July 2021. Founded in 2018 by Mohamad Ballout, Saman Darkan, Bader Ataya, and Andy Arenas, Kitopi pioneered the Kitchen-as-a-Service model in the Middle East.
The concept is brilliantly simple: restaurants can open delivery-only locations without capital expenditure or time investment. Kitopi provides the managed infrastructure, cloud kitchens, software, and logistics. A restaurant brand can scale from one location to dozens within 14 days—a proposition that proved irresistible during and after the pandemic.
Operating over 60 cloud kitchens across the UAE, Saudi Arabia, Kuwait, and Bahrain, Kitopi partners with global and regional brands. The company briefly expanded to the United States in 2019 but exited post-pandemic to focus on its Middle Eastern stronghold. With SoftBank among its investors, Kitopi represents the future of food service: asset-light, data-driven, and infinitely scalable.
The Healthtech Innovators
7. Vezeeta — Digitizing Healthcare Access
Dr. Amir Barsoum founded Vezeeta in 2012 with a straightforward mission: make booking a doctor appointment as easy as ordering an Uber. Vezeeta is the digital healthcare platform in MEA that connects patients with healthcare providers, serving millions of patients through data and seamless access.
The platform moved its headquarters from Cairo to Dubai to attract global talent—data scientists, product managers, and engineers essential for scaling. Vezeeta achieved unicorn status and has raised multiple funding rounds, with its Series C bringing in $12 million in late 2018.
With over 200,000 verified reviews, patients can search, compare, and book the best doctors in just one minute across Egypt, Saudi Arabia, Jordan, Lebanon, and the UAE. The platform also provides innovative SaaS solutions to healthcare providers through clinic management software, creating a two-sided marketplace that’s transformed outpatient care in the region.
Vezeeta’s expansion into e-pharmacy and telemedicine during COVID-19 demonstrated the platform’s adaptability. Now eyeing Nigeria and Kenya, the company is exporting its model to other emerging markets facing similar healthcare accessibility challenges.
The Logistics Game-Changers
8. Fetchr — Solving the No-Address Problem
In a region where many streets have no names and buildings lack numbers, traditional package delivery is nearly impossible. Enter Fetchr, founded by Idriss Al Rifai, which uses GPS smartphone location instead of physical addresses to deliver packages.
Fetchr is the third most well-funded tech startup in the UAE, having raised $52 million across four rounds, with its Series B led by US-based New Enterprise Associates. The company ranked number one on Forbes’ Top 100 Startups in the Middle East, testament to solving a problem that stumped global logistics giants.
Fetchr’s algorithm matches couriers with appropriate pick-up and drop-off points, much like ride-hailing apps. In areas with no formal addressing, this GPS-based approach isn’t just innovative—it’s essential. The company operates in the UAE, Saudi Arabia, Egypt, and Bahrain, capitalizing on growing smartphone penetration and the rapidly expanding regional e-commerce industry.
Looking ahead, Fetchr is exploring autonomous drone delivery services, positioned to become a strategic asset for any global player seeking Middle Eastern market dominance. Running entirely on Amazon Web Services, the company represents a potential acquisition target as Amazon expands its regional footprint.
9. SWVL — Democratizing Transportation
SWVL, valued at more than $1.5 billion, was founded in Egypt but moved its main office to Dubai in late 2019. The company ranked second on Forbes Middle East’s The Middle East’s 50 Most-Funded Startups list in 2020 with $92 million in funding.
SWVL operates a private premium alternative to public transportation, enabling riders heading in the same direction to share rides during rush hour for a flat fare. Unlike traditional ride-hailing, SWVL uses fixed routes with designated pick-up and drop-off spots, dramatically reducing costs while maintaining convenience.
The model addresses a massive market gap: millions of daily commuters priced out of individual ride-hailing but demanding better than overcrowded, unreliable public transit. By aggregating demand along popular routes, SWVL achieves efficiency impossible for traditional systems while providing predictability and safety.
The Aviation Powerhouse
10. Vista Global — Private Aviation Without Ownership
Founded in 2004, Vista Global became a unicorn in 2018 and provides comprehensive business flight services globally from its Dubai headquarters. The company raised $600 million in its latest funding round, one of the largest deals in the UAE’s recent history.
Vista integrates a unique portfolio of companies offering asset-free services covering all key aspects of business aviation: guaranteed and on-demand global flight coverage, subscription and membership programs, aircraft leasing and finance, and innovative aviation technology. The premise is compelling: consumers pay only for time spent flying, avoiding asset depreciation and ownership risks.
In a region where private aviation is synonymous with status, Vista democratized access through technology and fractional ownership models. The company’s AI-powered booking software optimizes aircraft utilization, reducing empty-leg flights and passing savings to customers. With sustainability increasingly critical, Vista’s efficiency-driven approach positions it at the intersection of luxury and responsibility.
The AgriTech Pioneer
11. Pure Harvest Smart Farms — Farming in the Desert
Sky Kurtz admits people thought he was crazy when he proposed indoor farming in the Dubai desert in 2017. Eight years later, Pure Harvest Smart Farms has raised $180.5 million in its latest funding round, with total funding reaching $387.1 million, making it one of the largest agri-tech firms in the region.
The UAE imports at least 80 percent of its food—a vulnerability exposed during every global crisis. Pure Harvest’s controlled-environment agriculture addresses this head-on. The company’s farms across the UAE produce over 33 million pounds of food annually, selling to major grocery stores in the region, including Carrefour, Spinney’s, and Waitrose.
Growing tomatoes, leafy greens, strawberries, and berries year-round in temperature-controlled facilities, Pure Harvest has proven that climate doesn’t dictate agricultural viability—technology does. The company’s systems are specifically designed for harsh Middle Eastern conditions, unlike competitors’ solutions built for temperate climates.
Initial funding came from the Mohammed bin Rashid Innovation Fund’s $1.5 million loan, with the Abu Dhabi Investment Office providing grants for expansion. Now eyeing Kuwait, Morocco, and Singapore, Pure Harvest is exporting its model to other food-insecure regions. The company even produces strawberry preserves and tomato sauces from leftover seasonal produce, reducing waste while generating additional revenue.
The PropTech Disruptor
12. Huspy — Turning Mortgages into Celebrations
Founded in 2020, Huspy reimagines the home buying process with a simple premise: getting a mortgage shouldn’t be painful. In less than 12 months, the company became the UAE market leader in digital mortgage solutions.
Using technology and internal expert knowledge, Huspy creates transparent, easy-to-use experiences. In a market where buying property traditionally involved dozens of bank visits, mountains of paperwork, and opaque pricing, Huspy’s digital-first approach feels revolutionary. The platform guides buyers through mortgage options, provides instant pre-approvals, and connects them with the best rates.
The proptech startup is now expanding its vision beyond mortgages to shape an entire category enabling and empowering the ecosystem: homebuyers, sellers, agents, and mortgage brokers throughout the UAE and beyond. In a region experiencing massive real estate growth, Huspy is positioning itself as the essential infrastructure for property transactions.
The E-Commerce Specialists
13. Eyewa — Disrupting Eyewear
Founded by ex-Bain consultants and former Rocket Internet managing directors, Eyewa aims to make eyewear accessible and affordable for everyone in the Middle East and North Africa. The Dubai-based startup offers sunglasses, prescription glasses, blue-light reading glasses, and contact lenses through an online platform that streams the purchasing process.
Building on successful eyewear e-commerce models from Europe, Asia, and the US, Eyewa leverages best-in-class technology to offer the most convenient online experience and disruptive retail store concepts. The company addresses a market where traditional optical stores charge premium prices with limited selection.
By combining virtual try-on technology, home delivery, free returns, and competitive pricing, Eyewa has captured significant market share among the region’s tech-savvy youth. The startup has raised multiple funding rounds and continues expanding its footprint across MENA markets.
14. The Luxury Closet — Circular Luxury Economy
The Luxury Closet specializes in the resale of high-end luxury goods, promoting sustainable consumption by offering a platform for authenticated pre-owned luxury items. In a region known for conspicuous consumption, the startup is pioneering the circular economy concept.
The platform attracts a growing clientele interested in both quality and sustainability. By providing authentication services, competitive pricing, and a curated selection, The Luxury Closet has made pre-owned luxury acceptable—even desirable—in markets traditionally focused on brand-new goods.
With rising awareness about sustainable consumption and the authentic luxury goods market growing globally, The Luxury Closet represents a new approach to retail in the Middle East: responsible, transparent, and technology-enabled.
The AI Powerhouse
15. G42 — The Regional AI Champion
Founded in 2018 and based in Abu Dhabi, G42 achieved unicorn status in 2021 after receiving $800 million from investors including Silver Lake. In April 2024, Microsoft announced it would invest $1.5 billion in G42, with Microsoft’s president Brad Smith joining G42’s board.
G42 is an artificial intelligence development company focused on advanced AI technology to improve life across multiple sectors. The company’s platforms and industry solutions harness the latest scientific research, applying it responsibly from healthcare to government services, finance to aviation.
Subsidiaries include healthtech company M42, the Presight analytics platform, Khazna data centers, and Core42 for cybersecurity and digital services. G42 partnered with OpenAI in October 2023 to develop AI in the UAE and regional markets.
The company’s $10 billion technology investment arm, 42XFund, signals ambitions extending far beyond the Middle East. In 2024, G42 helped launch MGX, an investment firm specializing in AI technologies with plans to raise $25 billion. With Microsoft Azure powering its operations and strategic partnerships with tech giants, G42 represents the UAE’s bet on becoming a global AI hub.
The Investment Equation: Why Capital Flows to Dubai
Follow the money, and you’ll understand the ecosystem. UAE startups raised nearly $2.4 billion in H1 2024, led by G42’s $1.5 billion round. But size isn’t everything—it’s who’s investing and why.
The Investor Landscape
Sovereign wealth funds dominate the cap table. Saudi Arabia’s Public Investment Fund, Abu Dhabi’s Mubadala Investment Company, and Kuwait’s Wafra International Investment Company aren’t passive check-writers—they’re strategic partners with decade-long visions. When PIF backs Noon with $500 million, it’s not seeking quick returns; it’s building regional infrastructure.
International VCs have taken notice. Sequoia Capital India, SoftBank, Wellington Management, Blue Pool Capital, and Silver Lake have all made significant Middle Eastern bets. This isn’t tourism—it’s recognition that the next generation of unicorns might wear kanduras instead of hoodies.
Late-stage deals dominated, taking about $817 million, while seed-stage funding shrank to just $32.7 million. This concentration signals maturity: investors are backing proven scale-ups rather than spreading bets thinly across early-stage startups. It also creates opportunity gaps for seed investors willing to place contrarian bets.
The Strategic Advantage
Unlike Silicon Valley’s geographic luck—elite universities, defense spending, venture capital culture—Dubai manufactured its advantages through policy. Zero corporate tax until recently, streamlined company registration, golden visas for entrepreneurs and investors, and regulatory sandboxes for fintech and emerging tech.
The Dubai International Financial Centre and Abu Dhabi Global Market provide common law jurisdictions within civil law countries, offering international investors familiar legal frameworks. Free zones like Dubai Silicon Oasis and Dubai Internet City offer 100 percent foreign ownership, tax exemptions, and custom regulations.
Most critically, Dubai offers access to high-growth markets. The MENA region’s population will reach 600 million by 2030, with a median age of 25 and rapidly growing internet penetration. These aren’t mature, saturated markets—they’re greenfield opportunities for digital services.
The Challenges Lurking Beneath the Glitter
Honesty demands acknowledging the obstacles. Dubai’s startup ecosystem isn’t perfect, and challenges threaten to constrain growth.
Talent Retention and Brain Drain
The region produces talented engineers and entrepreneurs, but many still seek Silicon Valley credentials before returning. While improving, technical talent depth lags behind established hubs. Visa complexities, despite reforms, still frustrate international recruitment.
Pure Harvest and Vezeeta both cited talent attraction as key drivers for Dubai moves. But moving headquarters is expensive—it’s a symptom of a problem. Until regional universities produce sufficient technical talent and entrepreneurial culture deepens, this constraint will persist.
Market Fragmentation
“The Middle East” isn’t monolithic. Saudi Arabia, UAE, Egypt, and others have different regulations, languages, payment preferences, and consumer behaviors. Scaling across the region requires navigating political tensions, varying regulatory environments, and cultural sensitivities.
Startups face a choice: dominate one market or spread resources thin. Tabby chose three core markets; others attempt broader expansion and struggle. Regional integration remains more aspiration than reality.
Dependency on Government Support
Nearly every success story includes government backing: sovereign wealth fund investments, development bank loans, regulatory sandboxes, infrastructure projects. This creates vulnerability. Political shifts, budget reallocations, or policy changes could destabilize the ecosystem overnight.
Contrast this with Silicon Valley’s decentralized, private-sector-driven innovation. When governments drive growth, governments can also halt it. The challenge is transitioning to self-sustaining cycles where successful exits fund the next generation—a process that takes decades to establish.
Exit Constraints
Careem’s $3.1 billion acquisition by Uber remains the largest technology sector transaction in Middle Eastern history—and it happened in 2019. Since then, exits have been limited. Public markets remain underdeveloped, with NASDAQ Dubai seeing limited activity. Most acquisitions are regional, limiting valuation potential.
Until viable IPO markets develop and international acquirers view the region as strategic, founders face constrained exit options. This affects fundraising dynamics, employee equity value, and ecosystem recycling of capital and talent.
Cultural and Regulatory Complexity
Despite reforms, doing business in the Middle East requires navigating complex cultural norms, Islamic finance principles, and sometimes unpredictable regulatory environments. Data localization requirements, content regulations, and evolving tech policies create compliance overhead.
For international founders and investors, these frictions add cost and risk. While improving, the region’s reputation for bureaucracy and opacity still deters some capital and talent.
Looking Ahead: The 2025 Outlook
Where does Dubai’s startup ecosystem go from here? Several trends will define the next 24 months.
The IPO Wave
Tabby’s planned Saudi IPO could unlock a wave of public listings. If successful, expect other unicorns to follow. Public markets provide liquidity, validate valuations, and create wealth that recycles into the ecosystem. The Saudi Stock Exchange (Tadawul) and Abu Dhabi Securities Exchange are positioning themselves as regional tech hubs.
AI and Emerging Tech
G42’s Microsoft partnership signals that AI investment is just beginning. Expect significant capital flowing into machine learning, computer vision, natural language processing, and AI applications across industries. The UAE’s strategy of becoming a global AI hub requires continued aggressive investment.
Climate tech and agri-tech will also see growth. Pure Harvest’s success proves that controlled-environment agriculture works in harsh climates. With food security a national priority and climate change accelerating, expect more capital into sustainable agriculture, water technology, and renewable energy.
Regional Consolidation
Markets are fragmenting along national lines—Saudi Arabia building its own ecosystem, Egypt struggling but persisting, Qatar investing in tech. Dubai must consolidate its position as the regional hub while navigating geopolitical complexity.
We’ll likely see more M&A activity as leading startups acquire regional competitors to achieve scale. Vertical integration will accelerate as platforms add adjacent services—e-commerce companies launching fintech, fintech companies offering e-commerce, super apps expanding into everything.
International Expansion
Leading startups will expand beyond MENA. Careem, Tabby, and Pure Harvest already have global ambitions. Expect more startups using Dubai as a launchpad to enter Southeast Asia, Sub-Saharan Africa, and South Asia—regions with similar characteristics and challenges.
This international expansion will attract more foreign capital and talent, further cementing Dubai’s position. Success breeds success; regional wins are nice, but global scale creates generational companies.
The Regulatory Evolution
As the ecosystem matures, expect regulations to tighten. The Wild West phase is ending; consumer protection, data privacy, financial regulation, and content moderation will all see increased scrutiny. How Dubai balances innovation and regulation will determine long-term competitiveness.
Regulatory sandboxes must evolve into permanent frameworks. The UAE’s progressive approach to crypto, fintech, and emerging tech regulation gives it an edge—but this requires continuous adaptation as technologies evolve.
The Verdict: Dawn of a New Tech Power
Twenty years ago, Dubai was known for oil, gold souks, and audacious real estate projects. Today, it’s home to twelve unicorns, $2+ billion in annual startup funding, and a generation of founders building billion-dollar companies.
This transformation reflects vision and execution. Government backing provided infrastructure and capital. Strategic reforms created business-friendly environments. Geographic positioning offered market access. Cultural adaptation allowed technology to solve local problems.
But ultimately, Dubai’s startup success comes down to people. Entrepreneurs like Hosam Arab, Mudassir Sheikha, Sky Kurtz, and thousands of others who saw opportunities where others saw obstacles. Investors who bet on potential rather than certainty. Governments who supported innovation rather than stifling it.
The fifteen startups profiled here represent broader trends: fintech’s rise, e-commerce’s inevitability, healthcare’s digitization, sustainability’s necessity, AI’s transformative potential. They prove that geography doesn’t determine destiny—vision, capital, talent, and execution do.
Is Dubai the next Silicon Valley? Perhaps that’s the wrong question. Silicon Valley is a 70-year-old ecosystem built on specific historical circumstances unlikely to be replicated. Dubai doesn’t need to be Silicon Valley—it needs to be Dubai: a uniquely Middle Eastern innovation hub addressing regional challenges with global technologies.
The challenges are real: talent constraints, market fragmentation, government dependency, limited exit options. But the momentum is undeniable. When sovereign wealth funds worth trillions commit to building tech ecosystems, when Microsoft invests $1.5 billion into regional AI companies, when founders successfully navigate from seed to IPO—the ecosystem becomes self-reinforcing.
For investors seeking emerging market exposure, Dubai offers unmatched opportunity. For entrepreneurs building global companies, it provides capital, talent, and market access. For governments seeking diversification, it demonstrates that economic transformation is possible with commitment and resources.
The desert has always been a place of transformation—where harsh conditions forge resilience, where trade routes connected civilizations, where vision transformed sand into cities. Today, that transformation is technological. And the fifteen startups leading this change are writing the next chapter of Middle Eastern history.
The sun still glints off the Burj Khalifa. But now, it illuminates something more than architectural ambition—it lights up a future where the Middle East isn’t just consuming technology but creating it, not just following global trends but defining them, not just building startups but building the ecosystems that produce the next generation of global giants.
The revolution has only just begun.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead.
Quick answer: India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
On November 6, 2026, Reuters reported that the Nifty 50 was up about 0.51% while the Nikkei and Kospi suffered steep declines. The immediate explanation was not that India had escaped global financial conditions. A pullback in crude prices, an improvement in foreign portfolio flows and a shift away from AI-heavy exposures created a comparatively favorable mix for Indian equities.
Foreign investors reportedly bought about 150 billion rupees of Indian shares on November 5—the largest single-day net purchase in nearly six years. That is an important flow event, but a single day of buying is not the same as a durable change in ownership or earnings expectations.
Why cheaper oil matters to India
India imports substantial crude oil, so a sustained fall in its import price can reduce pressure on the trade balance and inflation, subject to the rupee, tax policy and refinery margins. It can improve sentiment toward transport, consumption and rate-sensitive stocks. But if oil falls because global demand is collapsing, weaker exports and risk appetite may offset part of that benefit.
The World Bank expects commodity conditions to remain volatile. Investors should therefore distinguish a temporary crude-price dip from a more structural improvement in India’s energy terms of trade.
Foreign buying is a signal, not a guarantee
Global portfolio managers can rapidly shift country weights when a crowded trade sells off. India may attract allocations because of domestic demand and different index composition, but flows can reverse if currency risk rises or earnings disappoint. The market’s resilience should be judged by a series of sessions and broad participation, not one spectacular inflow.
Domestic institutional investors are an additional source of demand. When foreign and local investors take opposite sides, the effect on the index depends on sector weights, liquidity and which large companies are being traded.
The valuation question remains
An index can grow while being expensive. To assess the Nifty 50, consider forward earnings multiples, historical valuation ranges, earnings revisions and expected return on equity. A lofty multiple can be justified by robust profit growth, but its downside increases if expectations are not met. Investors should avoid comparing India’s headline P/E mechanically with markets that have very different sector mixes.
Separate earnings growth driven by real volumes, pricing and margins from one-off gains, currency translation and financing effects. The stronger investment case is one in which earnings breadth improves rather than relying on a small group of index heavyweights.
Banks and IT will determine breadth
Private banks react to loan growth, deposit pricing, asset quality and regulation. IT services companies face technology spending cycles, contracts, exchange rates and hiring demand. The same global AI shock that hurts expensive chip makers can either help IT services through workflow demand or hurt them if customers cut budgets.
Small- and mid-cap shares have different liquidity and valuation risks from the Nifty 50. A headline benchmark recovery with weak market breadth is a weaker signal than simultaneous improvement across several sectors.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | Reuters Nov 6 India markets |
| Interpretive opportunity | Oil versus foreign inflows |
| Secondary question | Sector-level breadth |
| Next verification | Update the closing index level, foreign institutional flows and USD/INR before posting. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
Capital inflows and domestic profits are separate. Foreign fund flows can move prices before the underlying corporate earnings outlook improves. Analysts should identify which signal they are discussing and why it matters. In this article’s subject—Nifty 50 today outlook—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
Headline index gains can coexist with weak breadth. If a handful of large companies drives a rally while smaller shares fall, the apparent strength is less diverse than the benchmark return suggests. Update the closing index level, foreign institutional flows and USD/INR before posting. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Oil versus foreign inflows. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Sector-level breadth. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Risk of mistaking flows for earnings. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
Three tests for the Nifty rally
Foreign inflows meet genuine earnings strength. The best case combines lower sustained energy import costs, corporate profit growth and foreign portfolio confidence. Banks would demonstrate healthy credit demand without deterioration in loan quality, while domestic consumption would support margins. The critical evidence would be several reporting periods of earnings progress, not the November 5 flow spike by itself.
A commodity or currency reversal. If crude rises again or the rupee weakens sharply, inflation expectations and foreign returns could deteriorate. Expensive equity valuations may then amplify selling even in companies with acceptable operating results. Risk is especially pronounced when a market’s recent strength rests on a narrow set of very large stocks or short-lived portfolio rotation.
The market pauses while fundamentals catch up. A long consolidation would not necessarily invalidate India’s structural investment case. It could allow earnings to grow into valuations while global investors digest the AI sell-off. Examine the direction of consensus earnings revisions, financial-sector profitability and market breadth before treating each daily Nifty movement as a turning point.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
A final distinction worth checking
India’s apparent resilience also needs sector and currency discipline. An investor who buys the Nifty in rupees but measures wealth in dollars faces both equity and foreign-exchange movements. A multinational technology exporter may respond differently from a domestic lender when the rupee or U.S. spending changes. Index breadth, banking-sector credit costs and the earnings trajectory of large consumer companies should be placed beside the November foreign-flow figures. Without this context, a sharp positive session can be mistaken for a lasting improvement in risk-adjusted returns.
Questions readers are asking
Why was Nifty stronger than Nikkei and Kospi?
Reuters cited falling oil, foreign buying and a rotation away from heavily AI-linked markets.
Is the Nifty 50 an AI index?
No. It is a diversified large-company Indian equity index with major financial, consumption, industrial and technology exposures.
Should a one-day rise be treated as a breakout?
No. Confirm trends with earnings, breadth, flows and repeated trading sessions.
What can reverse the rally?
Renewed oil inflation, rupee weakness, expensive valuations, weak earnings and abrupt foreign selling.
The judgment
India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead. The most responsible conclusion is conditional: Update the closing index level, foreign institutional flows and USD/INR before posting. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
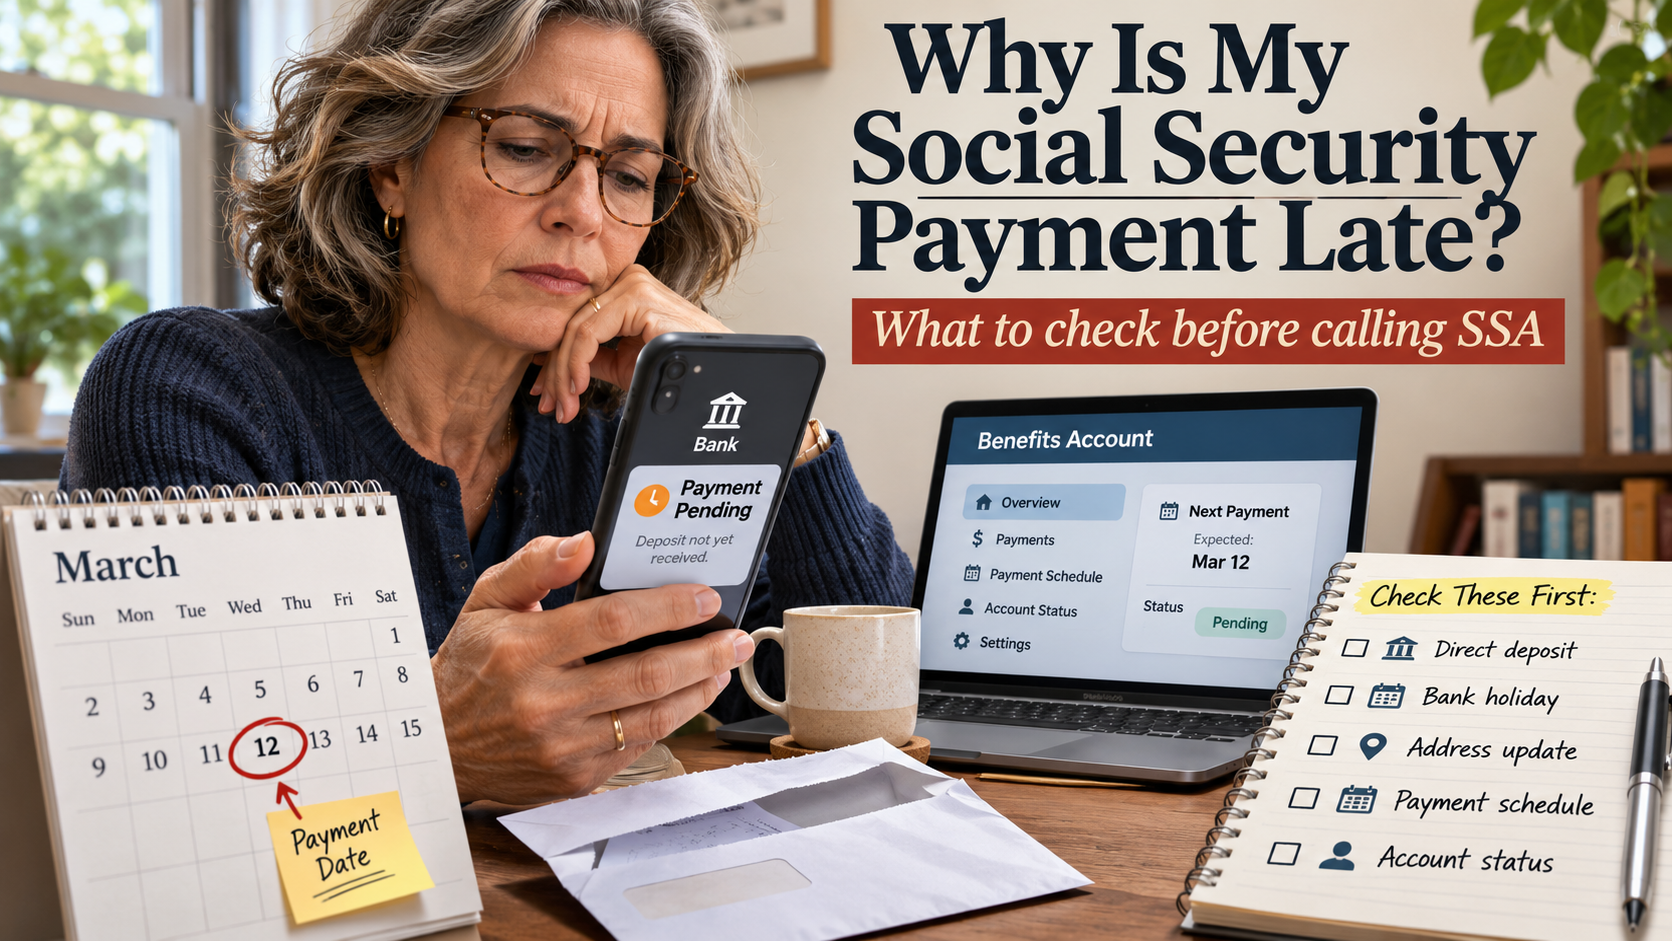
Quick answer: If your Social Security or SSI deposit has not appeared, first confirm the scheduled payment date for your program, then check with your bank or financial institution. The Social Security Administration’s missing-payment FAQ specifically says to contact your bank first for an electronic payment that does not arrive as scheduled. If the money remains missing, call SSA at 1-800-772-1213 or contact a local Social Security office. Do not pay a third party to ‘release’ your benefits.
A delayed deposit can be frightening when it is meant to cover rent, food, medicine or electricity. But the timing problem may have several explanations, and not all mean that the government has stopped the benefit. The most useful response is to determine whether the payment is not yet due, issued but not posted, sent to the wrong account, withheld after an eligibility change, or truly missing. Those categories lead to different next steps.
Step one: make sure today is really your payment date
The most common source of confusion is assuming every Social Security recipient is paid on the third of the month. In reality, the SSA’s published payment rules place most retirement, disability and survivor beneficiaries on one of three Wednesdays, generally based on the relevant birth-date category. Certain people who started benefits before May 1997, and some who receive SSI and Social Security together, have special schedules.
| Recipient category | Ordinary schedule | What to verify |
|---|---|---|
| SSI | First of the month, adjusted for weekends/holidays | Benefit month versus bank deposit date |
| Certain long-standing or dual beneficiaries | Third of the month, subject to adjustments | Whether your award follows the special cycle |
| Regular Social Security, birth date 1–10 | Second Wednesday | Holiday shifts and relevant birth date |
| Regular Social Security, birth date 11–20 | Third Wednesday | Correct calendar month |
| Regular Social Security, birth date 21–31 | Fourth Wednesday | Correct calendar month |
Consult the official benefit calendar rather than a social-media image. A chart that mechanically copies weekday patterns without considering federal holidays can misstate a particular month’s deposit date. For example, the first November 2026 Wednesday cohort was scheduled for November 10 rather than Veterans Day, November 11, under SSA’s holiday adjustment.
Step two: check holiday and weekend adjustments
When a normal payment date falls on a weekend or legal public holiday, Social Security generally issues the payment on the preceding business day. The agency’s holiday FAQ explains the principle. Consequently, a payment may show up earlier than a generic calendar suggests rather than later.
The November 2026 SSI example is instructive. Because November 1 fell on a Sunday, the SSI payment for the November benefit month was scheduled for October 30. Someone searching the bank statement only for a transaction dated November might think a payment is missing even though it arrived at the end of October. That is a question of benefit month versus calendar posting date, not necessarily entitlement.
Different banks may display transaction descriptions and posting times differently. A pending payment, an available balance and a settled transaction are not always the same entry. Use the statement details, not a push notification alone, when checking whether money arrived.
Step three: ask your bank whether a payment was received
SSA’s official advice is clear: if an electronic payment did not arrive on its scheduled date, contact your bank or financial institution first. The institution may be experiencing a delay in posting a deposit it has received. Ask whether there is a pending government benefit payment, whether there is a hold or account problem, and whether the institution has returned a transaction.
It helps to have the scheduled pay date and the last successful benefit transaction on hand. Do not assume the bank can reveal confidential SSA processing information; the bank can explain what its own systems show. If the bank sees no payment, tell SSA that you have already checked. This avoids repeatedly being sent back to the same first troubleshooting step.
If your bank account was recently closed or changed, the payment could have been rejected or returned. The SSA direct-deposit update FAQ describes how recipients can update relevant information, with different options for Social Security versus SSI. Never email complete bank details to an unsolicited address or disclose credentials to someone who calls unexpectedly.
Step four: use SSA’s official missing-payment reporting channel
If the bank cannot resolve the problem and the money is genuinely missing, contact the Social Security Administration. The missing-payment FAQ gives the number 1-800-772-1213 and the TTY line 1-800-325-0778, along with the option to contact a local office. SSA says it will review a qualifying missing-payment report and replace payment if it is due.
When contacting the agency, prepare the benefit type, scheduled pay date, the payment amount you expected, a brief description of what the bank told you and whether you changed accounts. You may need to verify your identity through an official process. The purpose is to give the representative enough information to investigate without sharing sensitive details through insecure channels.
A key distinction is between a payment the agency issued but you did not receive and a payment the agency has not authorized because of a change in eligibility or other adjudicated matter. The remedy for an issued-and-lost deposit is not necessarily the same as the appeal or correction process for a change in benefits.
What if my benefit amount changed rather than disappeared?
A smaller payment can feel like a missing payment when you budget a fixed amount. But Social Security deposits can reflect Medicare premium deductions, tax withholding, repayment of overpayments, adjustments to benefits and other legally applicable changes. SSI payments can also change with income, resources or living arrangements.
Check your most recent award or adjustment notice in your secure my Social Security account if your benefit type permits the relevant online service. Compare the gross entitlement with the net bank deposit. If the gross benefit has changed, ask what notice or determination supports the new amount. If only deductions changed, identify each one before assuming the benefit was reduced arbitrarily.
A person who receives both Social Security and SSI should check each benefit independently. For example, an increase in countable Social Security income may affect the SSI component under means-testing rules. Two deposits can move in different directions without there being a computer error. The SSA overview of SSI explains that income and living circumstances can change payment amounts.
What if the deposit goes to an old bank account?
Contact both your bank and SSA through verified channels. An account closure or change can cause a government deposit to be returned, which may require a reissue after the information is corrected. Do not assume transferring your ordinary paycheck to a new account also updates the Social Security benefit instructions.
The SSA’s direct deposit guidance notes that many retirement, survivors and disability recipients can use their personal online account to change banking information. The same online self-service functionality is not available for all SSI users, who may need to call or visit an office. That difference matters if an article promises one-click bank changes to everyone.
Before submitting a change, review the routing and account number carefully on a legitimate banking document. A single incorrect digit can cause a failure that takes time to investigate. If someone pressures you to reroute a benefit into an account that is not yours, treat that as a fraud warning and contact SSA directly.
How long should I wait before reporting a late payment?
The practical answer is: follow the agency’s current missing-payment instructions. The SSA FAQ asks electronic-payment recipients to contact their bank on the scheduled date if the payment is missing, then reach SSA if necessary. It does not instruct everyone to wait an arbitrary three or five business days before making any inquiry. If a new claim is involved, different processing and notification timelines may apply.
If the missing payment creates urgent hardship, explain that when you contact the agency. An inquiry may not produce an immediate replacement, but a clear description helps the agency understand the consequences. Seek local emergency assistance if you cannot obtain essentials while the problem is investigated; do not turn to a supposed ‘SSA release fee’ offered by a stranger.
Can scams look like payment problems?
Yes. Fraudsters often use worries about a missing deposit to lure victims into clicking links or revealing identification numbers, one-time passcodes and bank details. They may falsely claim a payment is frozen pending a small fee. Official government sites, including SSA’s account portal, should be accessed by typing the address directly or using a saved trusted bookmark.
SSA does not require you to pay a social-media account or intermediary to speed up a routine missing-payment report. Avoid handing over your entire banking login to anyone promising a quicker resolution. Preserve screenshots of suspicious messages if you need to report them, but do not forward sensitive attachments to unknown addresses.
A payment-troubleshooting checklist
Before making the call, write down these five answers: (1) Which program pays you? (2) What is the scheduled date according to SSA? (3) Did the calendar move that date because of a holiday? (4) What does your bank show? (5) Has your address, account or benefit entitlement changed? The sequence stops a simple calendar adjustment from escalating into an unnecessary dispute, while making genuinely missing payments easier to explain.
Keep copies of formal notices and bank transaction entries, but redact sensitive personal numbers if seeking help from a third party. A caregiver assisting another person should also follow SSA’s authorization rules and avoid impersonating the beneficiary during an inquiry.
Frequently asked questions
Why has my Social Security payment not arrived today?
It may not be your scheduled date, the bank may not have posted the payment yet, or SSA may need to review a bank-account or entitlement issue. Verify the schedule, then contact the bank and SSA if needed.
Who should I call first for a missing direct deposit?
SSA’s FAQ recommends contacting the bank first, followed by SSA at 1-800-772-1213 if the problem remains unresolved.
Can SSI be paid in the previous month?
Yes. If the first falls on a weekend or holiday, the monthly SSI payment may arrive on the prior business day, as happened for November 2026.
Does a smaller deposit mean SSA stopped my benefits?
Not necessarily. A deduction or an eligibility-related adjustment can change the net payment. Review notices and distinguish the gross award from the deposited amount.
Can I change my direct deposit online?
Many retirement, survivors and disability beneficiaries can, but online options differ for SSI. Follow SSA’s official instructions.
Bottom line
When a Social Security payment seems late, a measured sequence is more effective than panic or rumors: confirm the official date, check the bank’s posting, inspect notices and then report the problem through SSA. A correct diagnosis protects both your household budget and your personal information. A missing deposit deserves prompt attention, but it should not be confused with a benefit that was issued on a different calendar date.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
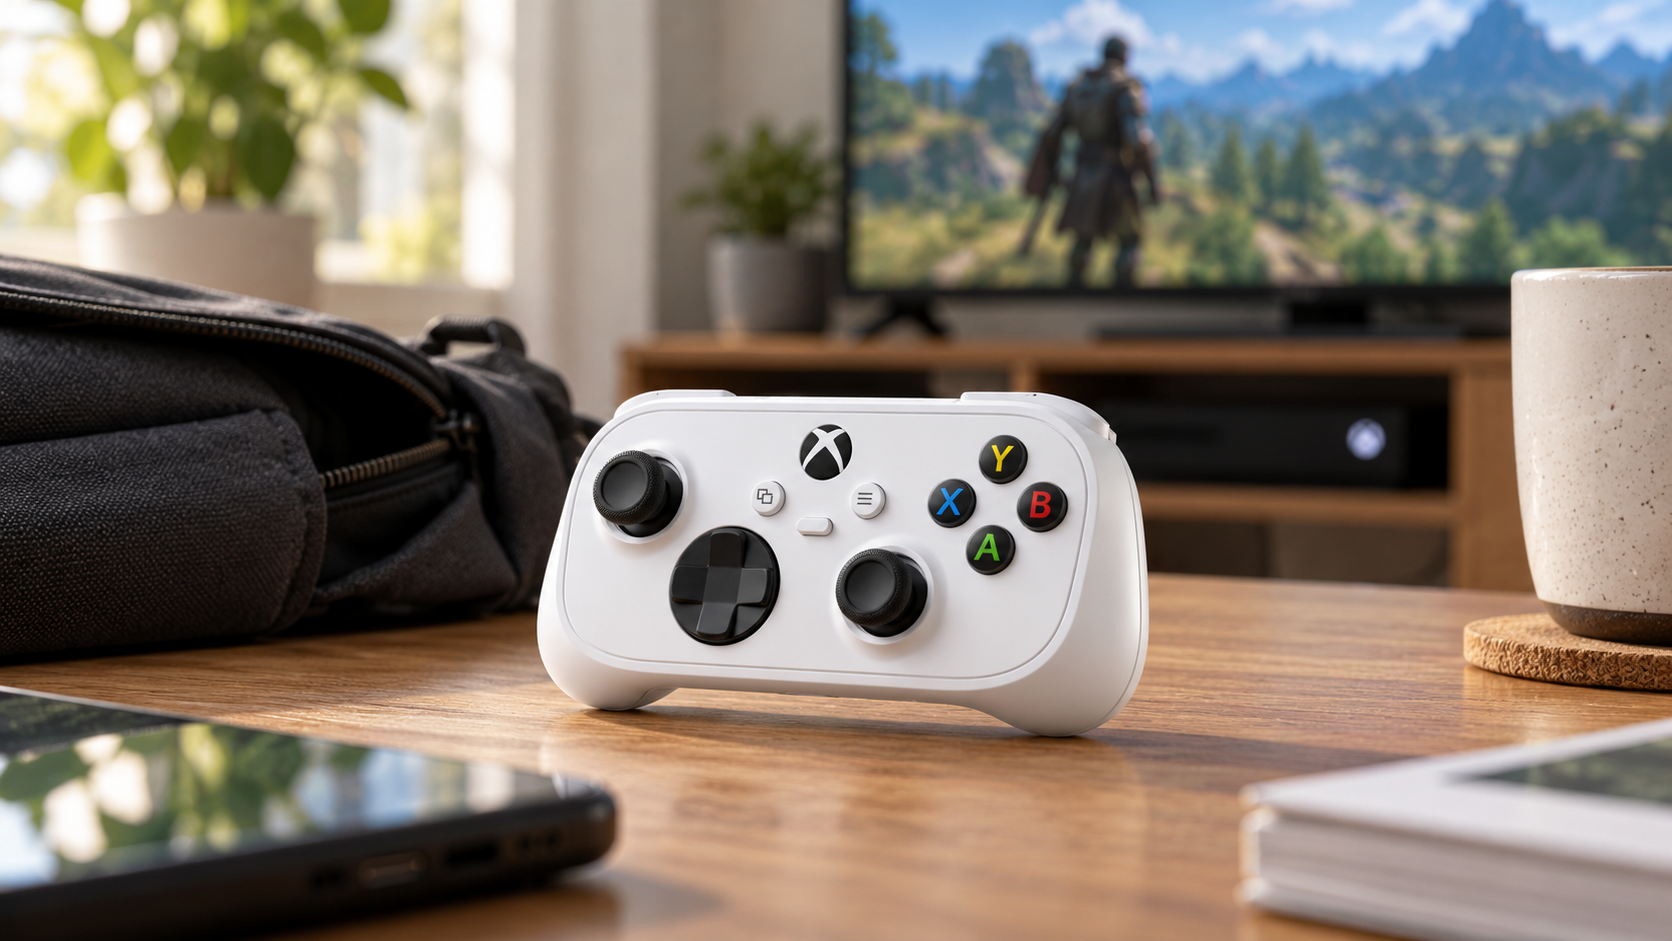
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. For primary-source background, consult Xbox Wire official announcement; Xbox official specification page; Microsoft Store US. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What Microsoft actually announced
The Xbox Wire announcement places the controller at a little over five inches long and approximately 3.5 ounces. Microsoft says it retains 18 standard gameplay inputs despite the smaller chassis. Its list price is $49.99 USD, though local prices and availability differ. It also reports a rechargeable internal battery and a programmable Action Button for tasks such as capturing screenshots or gameplay. This is a real official product launch, not a rumor based on leaked images. Product listings and availability should be checked for the buyer’s country.
Who benefits from a smaller controller
Small-hand ergonomics may be useful for some adults and younger players, but one size does not fit everyone. Grip diameter, shoulder-button reach, thumbstick placement and hand fatigue can matter more than weight alone. A tiny controller may be convenient in a bag but less comfortable during extended sessions for some users. A good review therefore evaluates real people with different hand sizes rather than calling compactness universally better. For parents, compatibility with age-appropriate games and device setup is part of the purchase decision. A low sticker price does not remove the need for usability testing.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026.
Wireless support and device compatibility
Microsoft says the Nano supports Xbox Wireless with compatible consoles and Bluetooth with supported PCs, mobile devices, tablets and smart TVs. That does not mean every game on every device is compatible. Operating-system support, cloud-play subscription availability and game-specific controller input differ. Players should inspect Microsoft’s compatibility notes before purchase, particularly for smart TVs or mobile games that require touch input. The internal battery uses USB-C charging, but the product page notes that the charging cable may be sold separately. Such minor accessories are relevant to total cost and should be visible in product comparisons.
Battery, Action Button and trade-offs
A built-in rechargeable battery changes ownership convenience compared with controllers that use replaceable cells, but it does not guarantee a particular play time. Battery duration depends on wireless mode, features and conditions. Microsoft has not established every real-world endurance result in the launch announcement, so editors should wait for independent testing before making precise claims. The programmable Action Button could reduce menu navigation for popular tasks, but users should verify exactly which shortcuts are available in supported software. Standard inputs may preserve familiar gameplay while smaller thumbstick travel or grip could affect precision; these are review questions, not proven flaws.
Is $49.99 good value?
Value depends on the buyer’s existing devices, preferred games and ergonomics. Someone who already owns a comfortable full-size controller may gain portability without needing to replace their main controller. A family seeking a second or third controller may prioritize price and consistent wireless pairing. A competitive player might instead favor adjustable controls, wired latency or premium hardware that the Nano does not claim to provide. Compare after-sales warranty, charging accessory costs, import taxes, local support and return rules. The launch is best understood as a compact mainstream option, not a universal upgrade from every other Xbox controller.
Worked example: how to interpret a difficult headline
Two buyers can reach different conclusions at the same price: a traveler wanting a lightweight Bluetooth controller may value the smaller form factor, while someone who plays long racing sessions on a console may prefer a larger grip. A useful review explains this trade-off rather than ranking products solely by price or feature count. Check a local store’s return policy in case the fit is unsuitable. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Official Xbox Nano | Small, $49.99 list price, rechargeable and portable. |
| Full-size standard controller | Potentially different hand fit and battery arrangements. |
| Premium controller | May add advanced customization at a higher price. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- November 2026 retail availability and regional pricing.
- Independent battery-life and ergonomic testing.
- Compatibility changes via software updates.
- Store returns, warranty and accessory requirements.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
Specifications make the Nano controller appealing, but personal hand fit, device compatibility, charging accessories, and return policy determine its value. The editorial differentiator is a use-case comparison rather than a copied feature list or an unsupported claim about measured latency.
Frequently asked questions
What is the Xbox Nano price?
Microsoft lists $49.99 USD before location-specific taxes and differences. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
When does Xbox Nano launch?
Microsoft describes November 2026 availability, with a specific November 4 date on its US store listing. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it have all the standard buttons?
Microsoft says it includes 18 standard gameplay inputs. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it work on PC and phones?
It supports Bluetooth on compatible devices; verify software and game compatibility. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

Sovereign AI Strategies Around the World in 2026

Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off

Why Is My Social Security Payment Late? What to Check Before Calling SSA

Bitcoin ETF Outflows: Has Institutional Demand Really Turned?

Xbox Nano Controller 2026: $49.99 Price, Features, November Release

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
Why Is My Social Security Payment Late? What to Check Before Calling SSA
Bitcoin ETF Outflows: Has Institutional Demand Really Turned?
Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off
Sovereign AI Strategies Around the World in 2026
-
Digital6 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital6 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China6 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools