AI
The Groq Deal: How a $20 Billion AI Chip Acquisition Rewrites the Geopolitics of Machine Intelligence

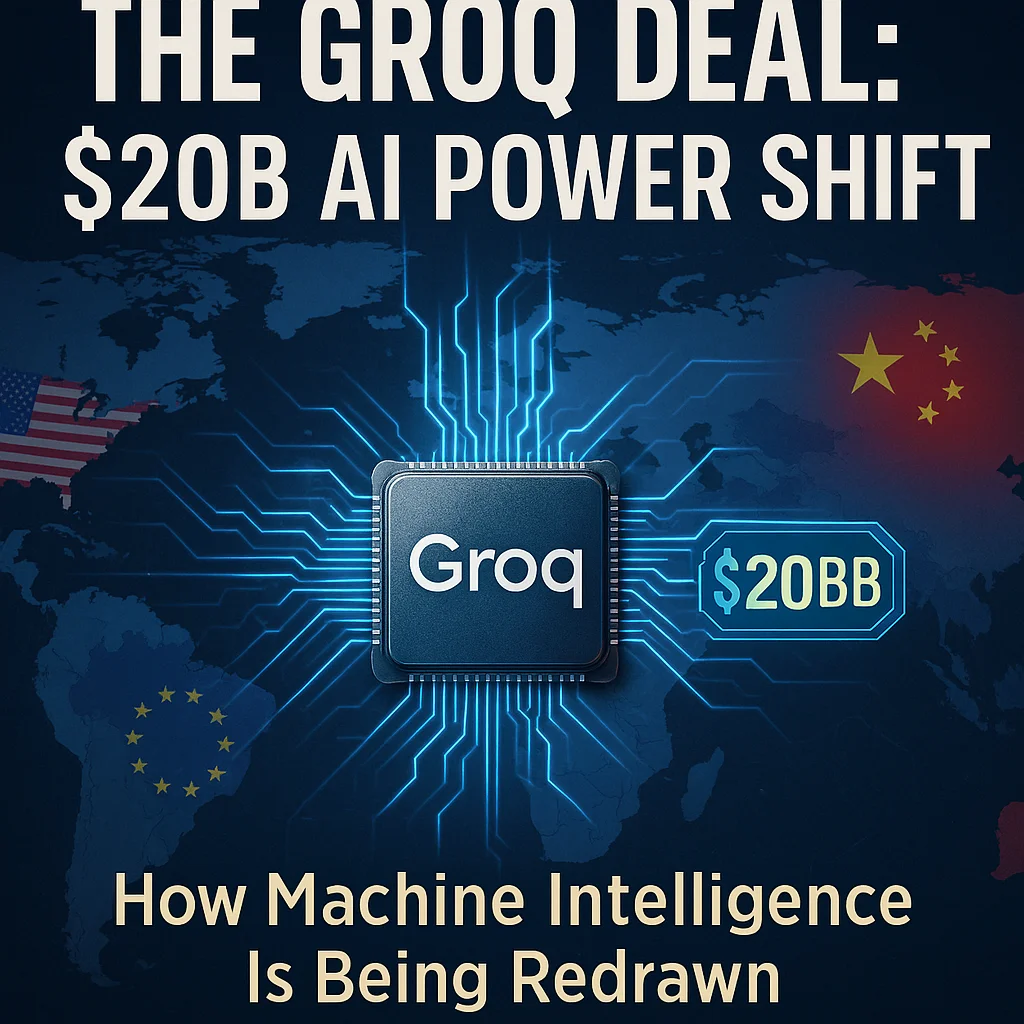
When Nvidia announced its $20 billion licensing agreement with AI chip startup Groq on Christmas Eve 2025, the move initially appeared to be another Silicon Valley acquisition story. But this transaction represents something far more consequential—a watershed moment in the technological competition that will define the 21st century balance of power.
The deal, structured as a non-exclusive licensing agreement with key personnel transfers rather than a traditional acquisition, marks Nvidia’s largest transaction ever and signals a profound shift in how advanced nations approach AI infrastructure as strategic capability. For policymakers in Washington, Brussels, and Beijing, the message is unmistakable: the race to control inference computing—the deployment stage where AI systems actually serve users—has become inseparable from questions of economic competitiveness and national security.
The Groq Innovation and Why It Matters
Founded in 2016 by Jonathan Ross, a former Google engineer who helped create the Tensor Processing Unit, Groq emerged with a radically different approach to AI computing. While Nvidia’s dominance rests on Graphics Processing Units optimized for training massive AI models, Groq developed the Language Processing Unit specifically engineered for inference—the moment when a trained AI responds to user queries.
The technical distinction matters immensely. Groq’s LPU architecture achieves inference speeds reportedly ten times faster than traditional GPUs while consuming one-tenth the energy. The company demonstrated this capability dramatically by becoming the first API provider to break 100 tokens per second while running Meta’s Llama2-70B model. In the AI economy, where milliseconds of latency determine user experience and energy costs shape profitability, these performance gains translate directly into competitive advantage.
Groq’s approach relies on deterministic processing architecture, using on-chip SRAM memory rather than the high-bandwidth memory that constrains global chip supply. This design allows precise control over computational timing, eliminating the unpredictable delays that plague conventional processors. The result is a chip that can serve chatbot responses, analyze medical images, or process autonomous vehicle sensor data with unprecedented speed and efficiency.
By September 2024, Groq had raised $750 million at a $6.9 billion valuation and was serving more than 2 million developers through its GroqCloud platform—nearly sixfold growth in a single year. The company projected $500 million in revenue for 2024, remarkable for a hardware startup operating in Nvidia’s shadow.
Nvidia’s Strategic Calculus
For Nvidia, which commands between 70% and 95% of the AI accelerator market according to Mizuho Securities estimates, the Groq acquisition reveals both strength and vulnerability. The company’s flagship H100 and newer H200 chips dominate AI model training, the computationally intensive process of teaching neural networks. This dominance has propelled Nvidia to a $3.65 trillion market valuation and generated over $80 billion in data center revenue in 2024 alone.
Yet training represents only half of the AI computing lifecycle. As models move from development to deployment, the economics shift dramatically. Training is where companies spend capital; inference is where they generate revenue. An AI model might be trained once over weeks or months, but it performs inference billions of times serving users. As OpenAI’s ChatGPT, Google’s Gemini, and Anthropic’s Claude scale to hundreds of millions of users, inference computing becomes the primary cost driver.
Industry analysts estimate that inference accounted for approximately 40% of Nvidia’s data center revenue in 2024. But this market faces far more competition than training, where Nvidia’s CUDA software ecosystem creates powerful switching costs. Companies including AMD, Intel, and startups like Cerebras Systems are actively developing specialized inference accelerators. Tech giants such as Google, Amazon, and Microsoft are designing custom chips to reduce dependence on Nvidia hardware.
The competitive landscape is intensifying. Google’s sixth-generation Tensor Processing Units and new Trillium chips target inference workloads. Microsoft’s Maia and Cobalt processors aim to optimize its Azure cloud infrastructure. Amazon’s Inferentia chips power AWS inference services. Meta has developed its own inference accelerators for internal use.
Against this backdrop, Groq represented both a threat and an opportunity. The startup’s technology demonstrated that specialized inference architectures could challenge GPU-based approaches on performance and efficiency. Groq’s rapid customer growth showed that developers would embrace alternatives when they delivered measurable advantages. Left independent, Groq might have evolved into a significant competitor. Integrated into Nvidia’s portfolio, the LPU architecture extends Nvidia’s reach into inference-optimized computing while neutralizing a potential rival.
CEO Jensen Huang’s internal memo to employees framed the acquisition explicitly: “We plan to integrate Groq’s low-latency processors into the Nvidia AI factory architecture, extending the platform to serve an even broader range of AI inference and real-time workloads.” The message signals Nvidia’s recognition that maintaining its AI infrastructure leadership requires excellence across both training and inference.
The Geopolitical Dimension: AI Chips as Strategic Assets
The Groq transaction unfolds against the most aggressive technology export control regime in modern history. Since October 2022, the United States has systematically restricted China’s access to advanced computing hardware and semiconductor manufacturing equipment. These controls, refined and expanded multiple times, aim to slow China’s AI development by denying access to the chips that make frontier AI possible.
The global AI chip market, valued at approximately $84 billion in 2025, is projected to reach between $459 billion and $565 billion by 2032, representing compound annual growth rates of 27% or higher. This explosive expansion reflects AI’s transformation from experimental technology to core economic infrastructure. Countries that control advanced chip design and manufacturing will shape how artificial intelligence develops and who benefits from its deployment.
China has responded to export restrictions with unprecedented investment in semiconductor self-sufficiency. Beijing’s Made in China 2025 initiative and successive Five-Year Plans have channeled tens of billions of dollars into domestic chip companies including Huawei HiSilicon, Cambricon Technologies, and Semiconductor Manufacturing International Corporation. Despite these efforts, China remains the world’s largest chip importer and continues to struggle producing the most advanced processors.
The effectiveness of export controls remains contested. Controls have demonstrably slowed China’s chipmaking capability by blocking access to extreme ultraviolet lithography tools essential for cutting-edge production. SMIC, China’s leading foundry, would likely have become the second-largest producer of advanced AI chips had it acquired EUV equipment as planned in 2019. Instead, Chinese manufacturers remain multiple technology generations behind Taiwan’s TSMC and South Korea’s Samsung.
Yet controls have not prevented Chinese AI developers from producing competitive models. DeepSeek’s release of the R1 model in early 2025 demonstrated that Chinese researchers could achieve performance comparable to American frontier systems despite hardware constraints. The development suggests that algorithmic innovation and efficient training techniques can partially compensate for inferior computing infrastructure.
The situation creates a complex strategic calculus. Export controls buy time for the United States and its allies to maintain AI leadership, but they simultaneously accelerate China’s drive toward technological independence. They protect American competitive advantage today while potentially strengthening Chinese capabilities tomorrow. This dynamic explains why the Trump administration’s December 2025 decision to conditionally allow H200 chip sales to approved Chinese buyers sparked immediate controversy.
The Inference Market as New Battleground
Within this geopolitical context, Groq’s specialized inference technology takes on strategic significance beyond its commercial value. Inference computing will increasingly determine which countries can deploy AI at scale, who controls the infrastructure that serves billions of users, and whose technological ecosystem becomes the global standard.
Consider the arithmetic. Training GPT-4 reportedly required approximately 25,000 Nvidia A100 GPUs running for roughly 100 days at an estimated cost exceeding $100 million. Yet serving that model to users requires far greater computational resources over time. Microsoft’s integration of GPT-4 into Bing search reportedly necessitated substantial infrastructure expansion. Google’s Gemini deployment across Gmail, Docs, and other services demands massive inference computing capacity. Alibaba and ByteDance face similar challenges deploying Qwen and other large language models to Chinese users.
The country that produces the most efficient, cost-effective inference chips will capture a disproportionate share of the AI economy’s value creation. Cloud providers will optimize around those chips. Software developers will design applications to leverage them. Users will gravitate toward services that offer superior performance and responsiveness.
Nvidia’s acquisition of Groq ensures that American companies maintain leadership in both AI training and inference. It prevents Chinese firms from licensing or acquiring Groq’s LPU technology, which could have accelerated China’s ability to deploy AI at scale. The deal effectively extends export controls through market consolidation—a form of private sector national security policy executed through commercial transactions.
This pattern is becoming familiar. In September 2025, Nvidia conducted a similar transaction with Enfabrica, spending over $900 million to hire the AI hardware startup’s CEO and license its technology. Other tech giants have pursued comparable deals. Microsoft’s hiring of Inflection AI’s leadership team came through a $650 million licensing agreement. Meta’s acquisition of key Scale AI personnel reportedly cost $15 billion. Amazon hired founders from Adept AI in a similar arrangement.
These “reverse acquihires” allow tech companies to acquire talent and intellectual property while avoiding the antitrust scrutiny traditional acquisitions attract. They also serve strategic technology policy objectives by keeping critical capabilities within allied ecosystems. As Bernstein analyst Stacy Rasgon noted regarding the Groq deal, structuring it as a non-exclusive license “may keep the fiction of competition alive” while achieving consolidation in practice.
The Trump Administration’s AI Statecraft
The timing of the Groq acquisition coincides with significant shifts in U.S. technology policy under the Trump administration. President Trump’s relationships with major tech CEOs, including Nvidia’s Jensen Huang, have become important channels for technology diplomacy. Trump has framed AI leadership as central to maintaining American global preeminence while simultaneously pursuing pragmatic engagement with China where commercial interests align.
The administration’s December 2025 decision to allow conditional exports of Nvidia’s H200 chips to approved Chinese buyers illustrates this complex approach. The policy permits sales to vetted end users while imposing a 25% revenue fee payable to the U.S. government. Proponents argue the controlled channel generates revenue while maintaining oversight. Critics contend it weakens strategic restrictions and potentially enables Chinese AI capabilities that could be used for military applications or surveillance.
Senator Elizabeth Warren and other lawmakers questioned whether the timing coordinated with Justice Department prosecution of illegal chip smuggling operations, suggesting possible political interference in enforcement. The White House drew distinctions between licensed exports to known buyers and illicit shipments to unknown parties, but the debate reflects deeper tensions about balancing economic interests against security concerns.
China’s reported consideration of its own limits on H200 chips adds another dimension. Beijing has increasingly deployed its domestic market access as leverage in technology negotiations. The country’s antitrust investigation into Nvidia for alleged violations during its 2020 Mellanox acquisition demonstrates China’s willingness to use regulatory tools as countermeasures against American restrictions.
These dynamics create an unstable equilibrium. Neither the United States nor China benefits from complete technological decoupling, yet neither trusts the other’s intentions sufficiently to embrace open technology transfer. The result is selective restriction punctuated by tactical accommodation—a pattern likely to characterize U.S.-China technology relations for years to come.
Implications for Allied Coordination
Export controls are only effective with allied cooperation. The Netherlands’ ASML produces the extreme ultraviolet lithography machines essential for cutting-edge chip production. Japan’s Tokyo Electron and other firms manufacture critical semiconductor equipment. South Korea’s Samsung and SK Hynix supply advanced memory chips. Taiwan’s TSMC fabricates most of the world’s leading-edge processors.
The United States has successfully coordinated with key allies on restricting advanced chip technology exports to China. In 2023, Japan and the Netherlands imposed controls similar to American restrictions after extensive negotiations. This alignment creates a more effective technology control regime than unilateral U.S. action could achieve.
Yet allied interests don’t always align perfectly. ASML derived 29% of its revenue from Chinese customers in 2023, creating significant economic incentives against further restrictions. European policymakers worry about triggering Chinese retaliation that could harm their companies while American firms capture market share. South Korean manufacturers fear losing competitiveness if Chinese firms develop alternative suppliers.
The Groq acquisition highlights how market consolidation by American firms can complement export controls. By integrating advanced inference technology into Nvidia’s U.S.-based operations, the deal ensures allied governments control access to these capabilities. This creates options for coordinated technology policy that pure export restrictions cannot achieve.
For European allies investing heavily in semiconductor manufacturing and AI capabilities through the Chips Act and related initiatives, Nvidia’s move sends a clear signal: the United States intends to maintain leadership across the full AI stack. European policymakers must decide whether to develop independent capabilities, deepen integration with American firms, or pursue some combination.
Market Structure and Antitrust Considerations
Nvidia’s consolidation of inference technology alongside its training dominance raises significant competition policy questions. The company’s 70-95% market share in AI accelerators already exceeds levels that would trigger antitrust scrutiny in most contexts. The Groq acquisition further concentrates market power in a sector critical to the broader AI economy.
Structuring the deal as a non-exclusive license rather than a traditional acquisition may help navigate regulatory review. Groq continues operating independently under new CEO Simon Edwards, maintaining its GroqCloud business. This preserves a nominal competitor while effectively transferring key technology and talent to Nvidia.
Yet the economic substance suggests significant consolidation. Groq’s founder and president join Nvidia, likely bringing deep technical knowledge and customer relationships. Nvidia gains rights to LPU intellectual property and can integrate it into product roadmaps. The $20 billion valuation represents nearly three times Groq’s September 2024 funding round valuation, suggesting Nvidia paid a substantial premium to secure these assets.
Competition authorities in the United States, European Union, and other jurisdictions will need to evaluate whether the arrangement harms innovation and consumer welfare. Traditional antitrust analysis might focus on whether Nvidia’s increased market power enables anticompetitive pricing or exclusionary practices. A more forward-looking assessment would consider whether the deal reduces the diversity of technical approaches in AI infrastructure, potentially slowing innovation or creating single points of failure.
The counterargument emphasizes that Nvidia faces intense competition from tech giants developing custom chips and from semiconductor firms including AMD and Intel introducing competitive products. Google, Amazon, Microsoft, and Meta collectively spend tens of billions annually on AI infrastructure and have strong incentives to avoid vendor lock-in. This buyer-side power may constrain Nvidia’s ability to exploit dominant positions.
From a national security perspective, concentration in Nvidia’s hands may be preferable to fragmentation across many smaller firms, some potentially vulnerable to foreign acquisition or influence. A consolidated American champion can more effectively compete with Chinese state-backed alternatives and serve as a reliable partner for allied governments.
The Energy-Infrastructure Nexus
The explosive growth of AI computing creates corresponding demands on energy infrastructure that carry their own geopolitical implications. Data centers housing AI chips consume enormous amounts of electricity for computation and cooling. Nvidia’s most powerful systems require kilowatts of power per chip, and a single large training run can consume electricity equivalent to hundreds of U.S. homes for weeks.
Industry forecasts suggest that AI chip deployment will drive global electricity demand increases comparable to adding entire countries’ worth of consumption. Utilities across North America, Europe, and Asia are racing to upgrade grid infrastructure to support planned hyperscale data center buildouts. The interconnection queue for new data center power connections has grown to record levels, creating bottlenecks that could constrain AI deployment even when chips are available.
This dynamic creates new forms of strategic advantage. Countries with abundant clean energy capacity and existing grid infrastructure can more readily deploy AI at scale. China’s massive investments in renewable energy and nuclear power—building new generation capacity ten times faster than the United States according to some estimates—position it to power extensive AI computing despite chip access limitations.
Groq’s energy efficiency gains take on strategic importance in this context. LPUs consuming one-tenth the power of equivalent GPUs enable deploying AI capabilities with significantly smaller infrastructure footprints. A country or company using Groq-based systems could achieve similar inference throughput with a fraction of the electrical capacity required for GPU-based alternatives.
The chip that wins the inference market may ultimately be determined as much by kilowatt-hours per billion tokens generated as by raw processing speed. Energy-constrained deployments—whether in data centers facing grid limits, edge computing scenarios with restricted power budgets, or mobile applications running on battery power—create opportunities for specialized architectures optimized for efficiency rather than peak performance.
Scenarios for the Next Decade
The confluence of technological innovation, geopolitical competition, and market concentration creates several plausible pathways for how AI chip markets might evolve through 2035.
In an optimistic scenario, Nvidia’s integration of Groq technology accelerates development of increasingly efficient inference systems that make AI deployment more affordable and accessible globally. Competition from tech giants’ custom chips and semiconductor rivals AMD, Intel, and others prevents monopolistic stagnation. Allied coordination on export controls successfully slows adversary AI capabilities while domestic innovation policies strengthen American and European semiconductor ecosystems. Energy infrastructure expands to meet demand without triggering climate or reliability crises. AI benefits diffuse broadly across economies and societies.
A baseline scenario sees continued U.S.-China technological competition without catastrophic conflict. Export controls remain in place with periodic adjustments as technologies evolve. Nvidia maintains dominant but not monopolistic market positions as major customers develop hybrid chip strategies balancing Nvidia hardware with custom alternatives. China achieves partial semiconductor self-sufficiency in trailing-edge technologies while remaining dependent on foreign suppliers for the most advanced chips. The global AI industry fragments into American and Chinese spheres with European and other allies navigating between them. Energy constraints occasionally limit AI deployment but don’t fundamentally block progress.
A pessimistic scenario features escalating technology confrontation between the United States and China, with export controls tightening to near-total bans on advanced chip exports. China responds with aggressive industrial espionage, illicit procurement networks, and potentially military pressure on Taiwan to secure semiconductor supplies. A Taiwan Strait crisis disrupts TSMC production, triggering supply chain chaos across the global economy. Nvidia’s market concentration enables rent extraction that slows AI innovation and deployment. Energy grid limitations become binding constraints on AI scaling. The promised benefits of AI technology fail to materialize for most of the world’s population as capabilities concentrate in wealthy nations and large corporations.
Policy Recommendations
Policymakers navigating these complex dynamics should consider several priorities:
First, maintain flexibility in export control regimes to adapt as technologies evolve. Static restrictions risk becoming either irrelevant as China develops workarounds or excessively broad as American innovation creates new capabilities. Regular review and adjustment based on intelligence assessments and technical developments can help controls achieve security objectives without unnecessarily harming innovation or allied cooperation.
Second, invest comprehensively in domestic semiconductor capabilities beyond export restrictions. The bipartisan CHIPS and Science Act represents important progress, but ensuring American leadership requires sustained commitment to research and development, workforce development, advanced manufacturing, and supporting startup ecosystems. No level of restrictions on competitors can substitute for maintaining innovation advantages through investment.
Third, strengthen allied coordination through multilateral frameworks that align economic interests with security objectives. The U.S.-EU Trade and Technology Council and similar forums provide venues for developing common approaches. Japan, South Korea, Taiwan, and other partners must be integral to technology strategies that acknowledge their central roles in semiconductor supply chains.
Fourth, monitor market concentration carefully through modernized antitrust frameworks suited to technology sectors. While some consolidation may serve strategic objectives, excessive concentration in any firm creates vulnerabilities and potentially slows innovation. Competition authorities should assess both competitive effects and national security implications of major technology transactions.
Fifth, anticipate and plan for energy infrastructure requirements of AI deployment. Grid modernization, clean energy capacity expansion, and efficient computing architectures should receive coordinated policy attention. Countries that solve the energy-AI nexus will gain significant advantages in the technology’s deployment phase.
Sixth, develop clearer principles for technology-security tradeoffs in commercial transactions. The Groq acquisition exemplifies how private sector deals can achieve national security objectives through market mechanisms. Establishing transparent criteria for when such consolidation serves strategic interests versus when it creates unacceptable concentration would help companies and investors navigate uncertain terrain.
Conclusion: The New Geopolitics of Silicon
Nvidia’s $20 billion Groq acquisition represents far more than a business transaction. It marks a defining moment in the emerging order where semiconductor technology and artificial intelligence capabilities have become inseparable from questions of national power, economic competitiveness, and global influence.
The inference computing market that Groq pioneered will shape how AI deploys at scale in the coming decade. The country or coalition that produces the most efficient, cost-effective inference infrastructure will capture disproportionate value from the AI revolution. Users will gravitate toward services built on that infrastructure. Developers will optimize for its capabilities. Standards and ecosystems will form around its architecture.
By bringing Groq’s LPU technology into its portfolio, Nvidia extends American leadership across the full AI computing stack while preventing this crucial capability from migrating to competitors or adversaries. The deal illustrates how market concentration can serve strategic objectives when properly structured, though it also highlights the need for vigilant oversight to prevent monopolistic abuse.
For policymakers, the message is clear: artificial intelligence is not merely a commercial technology but a foundational capability that will determine economic vitality and national security for decades to come. The chips that power AI systems are becoming as strategically significant as nuclear technology, biotechnology, and other dual-use capabilities that require careful management.
The challenge ahead involves maintaining technological leadership through innovation rather than restriction alone, coordinating effectively with allies whose interests may not perfectly align, balancing competition policy with security objectives, and managing the infrastructure requirements that AI deployment demands.
The Groq acquisition will not be the last major consolidation in AI hardware markets. As the technology matures and competition intensifies, we should expect continued market concentration through similar transactions. Whether this concentration serves innovation and broad prosperity or creates concerning dependencies and vulnerabilities will depend significantly on how policymakers shape the regulatory environment and invest in alternatives.
The geopolitics of machine intelligence has entered a new phase. The countries and companies that recognize this reality and act accordingly will shape the 21st century’s technological landscape. Those that fail to adapt will find themselves dependent on others’ infrastructure, standards, and ultimately strategic choices.
In this contest, $20 billion for specialized inference technology is not merely a business expense—it is an investment in technological sovereignty for an AI-powered era. History will judge whether it proves sufficient to maintain American leadership in the defining technology of our time.
Statistical data drawn from: Coherent Market Insights, MarketsandMarkets, IDTechEx, Mizuho Securities, CNBC, Reuters, TechCrunch, and congressional research reports on semiconductor export controls.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


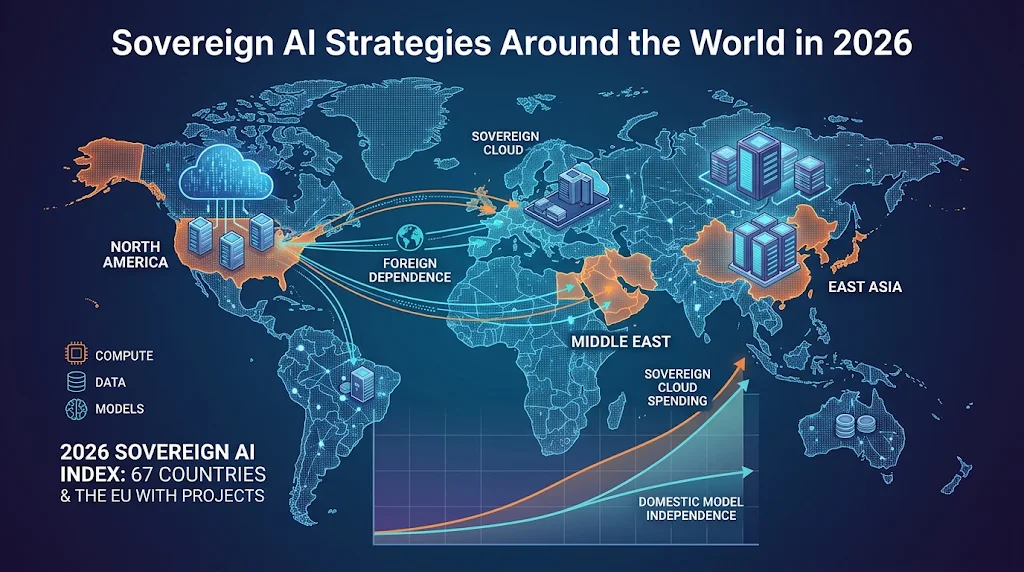
Governments are spending heavily to build domestic AI capacity, from data centers and compute clusters to national language models. The Center for a New American Security’s Sovereign AI Index tracked 67 countries and the European Union with projects by mid-2026, and it found that most of the disclosed investment is concentrated in the Middle East and East Asia. The core tension is that most sovereign projects still rely on American or foreign technology providers.
Key Takeaways
- The CNAS Sovereign AI Index counted 67 countries and the European Union with sovereign AI projects by mid-2026, according to its August 2026 update.
- The Middle East and East Asia account for more than 80% of tracked, publicly disclosed sovereign AI investment, per the CNAS index.
- Infrastructure now dominates new projects: about 80% of projects launched in the first half of 2026 focused on infrastructure, up from 62% in the prior six months.
- Gartner expects China and North America to lead sovereign cloud infrastructure spending in 2026, at roughly $47 billion and $16 billion, respectively, and Europe to surpass North America in 2027.
- Most sovereign projects still depend heavily on foreign providers, often American ones, which limits the autonomy they promise.
What Sovereign AI Means
There is no single definition, which complicates comparisons. The CNAS index treats a sovereign AI project as a government-backed initiative tied to national strategic interests and backed by material public investment in domestic capabilities. Other analysts use the term more broadly to include regulatory control, data localization, and domestic model development.
In practice, governments pursue three layers of capability:
- Compute: data centers, GPUs, and sovereign cloud platforms
- Data: national datasets for training and public-sector use
- Models: domestic foundation models, often tuned to local languages and laws
According to the CNAS index, compute and infrastructure dominate, while data projects remain the smallest category, accounting for about 5% of new projects in the first half of 2026.
Who Is Spending
Spending is highly concentrated. The CNAS index reports that about 40% of tracked countries back only a single project, and that a few large national commitments account for much of the total.
Several examples illustrate scale:
- India: Adani Group announced plans in February 2026 to invest $100 billion in sovereign AI infrastructure by 2035, which it said could contribute to a broader $250 billion ecosystem in the country, per BusinessToday. This is a private commitment, not a government budget figure.
- South Korea: Reports describe a 2026 national AI budget of about 9.9 trillion won, roughly $7.1 billion, across dozens of ministries. This figure comes from a secondary source, so confirm it against official government releases before publication.
- United States: The Stargate project, announced in January 2025 by OpenAI, SoftBank, and Oracle, has a stated commitment of $500 billion over four years. It is largely private rather than public investment.
- Gulf states: Investment in the Middle East is among the largest by disclosed value, per the CNAS index, which accounts for much of the regional concentration.
Stanford’s 2026 AI Index found that national AI strategies are expanding fastest among countries that had no formal AI policy five years ago, and that U.S. public investment in AI remains modest relative to private spending.
The Sovereignty Paradox
Most countries pursuing sovereign AI rely on foreign technology. The CNAS index found that foreign companies, overwhelmingly American, remain embedded in more than 170 national infrastructure and model projects. Many sovereign data centers run on U.S.-designed chips, use American cloud software, or depend on American model architectures.
This creates a paradox. Governments want independence from foreign dependence, yet building independent capability is expensive and slow. Gartner has warned that sovereign AI strategies could lock countries into region-specific platforms: it predicted in January 2026 that 35% of countries would be locked into such platforms by 2027, according to its press release. The paradox is that regional independence can create its own dependencies.
Gartner also projected that nations building a sovereign AI stack would need to spend at least 1% of GDP on AI infrastructure by 2029. For smaller economies, that is a significant commitment.
Sovereign Cloud Is the Fastest-Growing Piece
Sovereign cloud, which keeps data and processing within national borders under local control, is one of the clearest growth areas. Gartner projected 2026 sovereign cloud infrastructure-as-a-service spending of about $47 billion in China and $16 billion in North America, with Europe expected to surpass North America in 2027. The European shift reflects a move away from U.S.-based cloud providers, driven by regulatory and geopolitical concerns.
Why Some Countries Are Building Anyway
The motivations are mixed. Governments cite economic competitiveness, national security, data protection, and the desire to shape local AI use. Some want to retain talent and attract AI companies. Others want to avoid being dependent on a single supplier if export controls or geopolitics disrupt access to chips and cloud services.
Cost is the main limit. As one industry analysis put it, the level of investment required is beyond the reach of most countries, which creates an asymmetry in the global AI landscape. Many countries will rely on partnerships rather than fully independent stacks.
Trade-Offs and Risks
Sovereign strategies carry real trade-offs:
- Capability gap. Domestic models may trail frontier systems, requiring governments to accept lower performance for control.
- Duplication. Multiple countries building similar infrastructure can waste capital if utilization is low.
- Supplier dependence. Chips, networking, and software often come from a small set of firms, limiting independence.
- Energy and land. Like the data center backlash in the U.S., sovereign projects face power and local-approval constraints.
- Fiscal risk. Public money committed to AI infrastructure must compete with healthcare, education, and defense budgets.
What to Watch
- Whether sovereign projects shift from announcements to operating capacity, which CNAS identifies as a key test
- Growth in sub-national sovereign AI projects, which CNAS reports have risen rapidly in 2026
- European sovereign cloud procurement and any move away from U.S. providers
- Export control changes that could affect chip access for national projects
- Gartner and CNAS updates on sovereign spending and lock-in patterns
Frequently Asked Questions
What is sovereign AI? Sovereign AI refers to government-backed efforts to build or control AI infrastructure, data, and models within national borders, often to reduce dependence on foreign providers.
Which countries are leading? By disclosed investment, the Middle East and East Asia lead, according to the CNAS Sovereign AI Index. Specific country rankings depend on how projects are counted.
How much are countries spending on sovereign AI? Estimates vary widely depending on definition. Gartner projects sovereign cloud IaaS spending of about $47 billion in China and $16 billion in North America in 2026, while private commitments such as Adani’s $100 billion plan add to the total.
Do sovereign AI projects use American technology? Often, yes. The CNAS index found that foreign companies, mostly American, remain embedded in more than 170 projects.
Is sovereign AI a good investment for governments? It depends on the country. Costs are high, and returns depend on whether infrastructure is used productively. Governments that tie investment to local skills and research tend to get more value.
What is the risk of sovereign AI? Duplication, supplier dependence, underused capacity, and fiscal strain are the main risks. Some projects may also fall short of their stated independence goals.
Conclusion: Independence Is Expensive
Sovereign AI is becoming a central feature of global technology policy in 2026, but true independence is expensive and hard to achieve. Most countries are building compute with foreign components, and some will end up depending on new regional platforms. Readers should judge sovereign strategies by whether they deliver working capacity, skills, and reduced vulnerability, not just by announced totals.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
AI
PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand
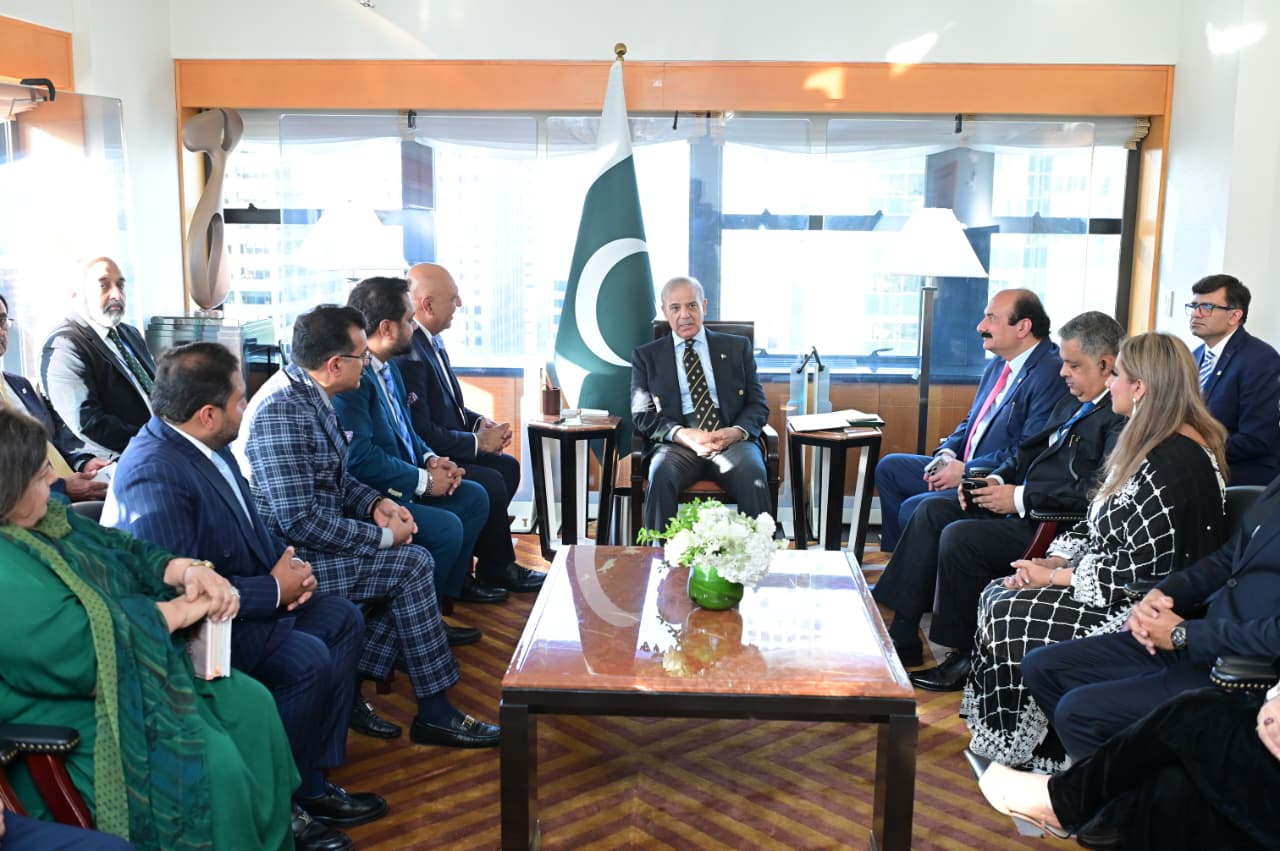
NEW YORK, September 24, 2026 — Prime Minister Muhammad Shehbaz Sharif has invited Pakistani business leaders and professionals based in the United States to invest in Pakistan, highlighting government measures aimed at improving the business environment and encouraging investment.
The invitation came during meetings with Pakistani-American business personalities and professionals working across information technology, artificial intelligence, automobiles, energy, construction and other sectors.
According to the Associated Press of Pakistan (APP), the prime minister said the government was working to create a conducive environment for investment and business activity. He also pointed to reforms at the Federal Board of Revenue (FBR) and measures intended to promote innovation in agriculture.
But the latest appeal to the Pakistani-American business community comes against a broader backdrop: Pakistan is seeking to attract more private investment, expand exports and turn improving macroeconomic conditions into sustained economic activity.
Why Pakistani-American Investors Are Being Targeted
The Pakistani diaspora represents an important source of capital, business expertise and international commercial connections.
Pakistan’s remittance flows demonstrate the economic significance of its overseas population. World Bank data show that Pakistan received approximately $40.48 billion in personal remittances in 2025, equivalent to around 9.9% of GDP.
The State Bank of Pakistan also reported workers’ remittances of approximately $3.66 billion in August 2026, with the monthly series showing substantial inflows throughout 2026.
Investment, however, differs from remittances: it involves deploying capital into businesses, projects or financial assets with the expectation of returns. That distinction makes the government’s effort to attract diaspora entrepreneurs particularly relevant.
IT and AI Among the Sectors in Focus
The technology sector is one of the most significant areas highlighted by the government.
The September 24 meeting included Pakistani-American professionals associated with IT and artificial intelligence, alongside representatives from traditional sectors such as automobiles, energy and construction.
Pakistan’s broader investment framework identifies services, including IT and telecommunications, as areas open to foreign investment. The Board of Investment says Pakistan maintains a liberal investment regime and has mechanisms designed to facilitate local and foreign investors.
For Pakistani-American technology entrepreneurs, potential areas include:
- Software and SaaS businesses
- Artificial intelligence
- IT-enabled services
- Fintech
- Digital infrastructure
- Business-process outsourcing
- Export-oriented technology companies
- Technology startups and venture investment
The attraction for diaspora entrepreneurs is not necessarily limited to providing capital. Entrepreneurs with operations in the United States can potentially bring technology, management expertise, international customers, investment networks and access to global markets.
Agriculture Is Another Priority
Agriculture was also specifically mentioned during the prime minister’s meetings.
APP reported that Shehbaz Sharif said the government was taking measures to promote innovation in agriculture.
That creates potential investment themes around:
- Agri-processing
- Agricultural technology
- Cold-chain infrastructure
- Food processing
- Irrigation technology
- Storage and logistics
- Export-oriented agriculture
- Livestock and dairy
- Farm mechanization
For investors, the distinction between producing agricultural commodities and investing in higher-value processing and supply-chain infrastructure can be particularly important because value-added businesses can connect domestic production with international markets.
What Pakistan’s Investment Framework Offers Foreign Investors
Pakistan’s Board of Investment states that the country follows a liberal investment regime and that its mandate includes promoting, encouraging and facilitating both local and foreign investment.
The Board’s investment information also states that foreign investors can have 100% equity ownership in many areas, although restrictions or specific rules apply to certain sectors.
The government’s Investment Policy 2023 also emphasizes investor protection, investment promotion and expanding Pakistan’s investment-promotion presence abroad, including in the United States.
That policy framework provides important context for the prime minister’s latest appeal to Pakistani-American businesses.
Pakistan Has Also Introduced a New Long-Term Residency Route for Investors
Another development relevant to international investors is Pakistan’s Long-Term Residency (LTR) framework.
According to the Board of Investment, the Foreigners (Long Term Residency) Order, 2025 created a residency-by-investment framework offering five-, seven- and ten-year residency options, subject to eligibility and investment requirements. The BOI says the minimum investment requirement is $50,000, to be materialized within one year through authorized banking channels.
The scheme is separate from the government’s broader investment-promotion policies, but it illustrates the effort to create additional mechanisms for attracting international capital and entrepreneurs.
The U.S.-Pakistan Economic Relationship Adds Another Layer
The appeal to Pakistani-American businesses also comes while economic engagement between Pakistan and the United States remains an important part of Pakistan’s external economic strategy.
In July 2026, Reuters reported that Pakistan had requested a proposed $10 billion U.S. exchange stabilization facility, while discussions were also taking place with U.S. financial institutions including the Export-Import Bank and the U.S. International Development Finance Corporation.
More recently, Reuters reported that Pakistan expected a decision from the United States on the proposed facility while continuing discussions with U.S. EXIM Bank and the Development Finance Corporation on potential projects.
These developments concern government-to-government and institutional financing rather than Pakistani-American private investment, but together they illustrate the wider economic relationship in which the latest business-community outreach is taking place.
What the Government Says About Investment Facilitation
Pakistan’s Board of Investment describes itself as the interface between international and domestic investors and the public and private sectors. Its investment regime information highlights measures intended to reduce the cost and procedural burden of doing business and to facilitate investment.
The government has also continued promoting the Special Investment Facilitation Council and other mechanisms intended to streamline investment processes.
For an investor considering Pakistan, however, the existence of an investment framework does not remove the need for sector-specific due diligence, regulatory approvals, taxation analysis, foreign-exchange considerations and commercial risk assessment.
What Pakistani-American Investors Should Examine Before Investing
The prime minister’s invitation is a political and economic call for greater investment, but prospective investors still need to evaluate individual opportunities on their own merits.
Key issues include:
1. Regulatory requirements
Investment rules differ according to the sector. The BOI notes that some industries are subject to specific restrictions or approvals.
2. Ownership structure
Foreign ownership can reach 100% in many sectors, but exceptions exist, making a sector-specific review necessary before establishing a company.
3. Profit and capital repatriation
Pakistan’s investment framework provides mechanisms for foreign investors to repatriate eligible profits, dividends and investment proceeds, subject to applicable foreign-exchange procedures.
4. Taxation
Investors should examine federal and provincial taxes, withholding obligations, customs duties and sector-specific incentives before committing capital.
5. Infrastructure and operating costs
An attractive investment proposition depends not only on headline incentives but also on electricity, logistics, labor, financing, connectivity and supply-chain costs.
6. Exit strategy
Investors should establish how capital can be repatriated, shares transferred and profits distributed before entering the market.
Pakistan’s Investment Push Extends Beyond the United States
The latest initiative is part of a wider effort to attract overseas Pakistani capital.
Earlier in September 2026, Economic Affairs Minister Ahad Cheema directed officials to develop a structured mechanism through which overseas Pakistanis could participate in viable infrastructure projects, including potential opportunities involving railways, highways, power, civic infrastructure and airports.
In July, Planning Minister Ahsan Iqbal also invited Pakistani-American entrepreneurs, technologists and financiers in Chicago to bring capital, expertise and global networks to Pakistan’s economic development.
This indicates that the September 24 appeal is not an isolated announcement but part of a broader government effort to engage overseas Pakistanis and international investors.
The Bigger Question: Can Investment Follow the Outreach?
The government’s challenge is to convert investment invitations into bankable projects and completed investments.
That requires more than announcements. Investors typically assess regulatory predictability, taxation, currency convertibility, infrastructure, security, financing costs, market size, contract enforcement and the ability to repatriate returns.
The U.S. State Department’s investment-climate assessment has previously identified challenges in Pakistan including regulatory complexity, intellectual-property concerns, changing taxation policies and security-related investor concerns. At the same time, it noted that U.S. companies operate profitably in several Pakistani sectors and that there are no restrictions specifically targeting U.S. investors.
That combination—investment opportunity alongside identifiable investment risks—is important context when assessing the latest government outreach.
What Comes Next for Pakistani-American Investment
Prime Minister Shehbaz Sharif’s September 24 appeal places Pakistani-American businesses at the center of Pakistan’s effort to attract additional investment.
The sectors discussed—AI, IT, energy, automobiles, construction and agriculture—cover both emerging technologies and established parts of the economy.
Pakistan’s investment framework, expanding diaspora-focused initiatives and continuing U.S.-Pakistan economic engagement could provide additional channels for investment. However, the eventual impact will depend on whether proposed opportunities develop into commercially viable projects and whether investors find the regulatory and economic environment sufficiently predictable.
For Pakistani-American entrepreneurs, the latest message from Islamabad is therefore straightforward: the government wants greater diaspora participation not only through remittances, but also through entrepreneurship, capital, technology and long-term investment.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
WASHINGTON — Newly disclosed federal financial records show that investment accounts belonging to President Donald Trump underwent an aggressive portfolio restructuring in July 2026, logging 1,156 individual securities transactions valued between $79 million and $270 million.
While headline attention has focused on multi-million-dollar sales of artificial intelligence and mega-cap tech leaders—including Microsoft, Amazon, and Meta Platforms—a comprehensive examination of the filings reveals a more complex strategy: a transition driven by automated index rebalancing, defensive fixed-income allocation, and concurrent dip-buying.
Executive Overview: July 2026 Disclosure Breakdown
According to analysis of official filings submitted to the U.S. Office of Government Ethics and reported by CNBC, total purchases across the eight managed accounts exceeded total sales.
| Category | Aggregate Value Range | Key Assets / Companies Involved |
| Total July Transactions | $79 Million – $270 Million | 1,156 total trades logged across 8 accounts |
| Total Purchases | $43.6 Million Minimum | Municipal bonds, short-term ETFs, Broadcom, Nvidia |
| Total Sales | $35.6 Million Minimum | Microsoft, Amazon, Oracle, Meta, Northrop Grumman |
| Primary Liquidation Event | July 20, 2026 | Multi-million dollar trims in $MSFT and$AMZN ($5M–$25M bracket each) |
| Quick Re-Entry Trades | July 23, 2026 | Modest buybacks in $MSFT ($100K–$250K) and$AMZN ($1K–$15K) |
Dissecting the Big Tech Trims: Algorithmic Rebalancing vs. Market Sentiment
The largest individual entries in the September filing occurred on July 20, 2026, when investment managers executed broad sell-offs in major cloud and AI infrastructure vendors.
As reported by Quartz, individual sell orders for Microsoft and Amazon each landed in the $5 million to $25 million filing bracket. Simultaneously, managers offloaded between $1 million and $5 million in Oracle stock, alongside position trims in Meta Platforms, Alphabet, and Nvidia.
However, reporting focused exclusively on liquidations misses the broader picture:
- Simultaneous Accumulation: On the very day managers sold Oracle, they added $500,000 to $1 million in Nvidia, while opening $1 million to $5 million positions in enterprise software giants like Salesforce, Intuit, and Marvell Technology.
- Immediate Re-entry: Just three days after the July 20 sell-off, the accounts repurchased positions in Microsoft ($100,001–$250,000 range) and Amazon ($1,001–$15,000 range).
- Fixed-Income Pivot: Significant capital was rotated into defensive yield assets, including the Vanguard Short-Term Bond Index ETF, State Street SPDR Bloomberg International Treasury Bond ETF, and local government bonds such as Miami-Dade County aviation paper.
Financial analysts noted in coverage by Livemint that these multi-directional trades mirror index-tracking models adjusting for market weightings rather than a deliberate directional bet on the tech sector.
White House Clarification: Automated Model Portfolios
Trading volume of this scale by a sitting U.S. president inevitably draws regulatory and public scrutiny. Addressing the disclosures, White House spokesperson Davis Ingle emphasized that the President maintains no personal involvement in daily trade execution.
“The President’s investment portfolio is managed by independent third-party financial institutions through automated model portfolios benchmarked to broad indices like the Schwab 1000,” White House officials stated. “Trading decisions are algorithmically executed without input, direction, or prior knowledge from the President or his family.”
Unlike past presidential administrations that placed assets into blind trusts or single-index mutual funds, the current arrangement relies on third-party wealth managers utilizing direct indexing models.
Regulatory Scrutiny and Geopolitical Overlap
Despite White House assurances, the timing of specific trades has drawn criticism from Capitol Hill.
On July 20, the same day managers sold $250,000 to $500,000 worth of defense contractor Northrop Grumman, President Trump signed an executive order tightening supply chain mandates for defense suppliers and restricting critical material sourcing from foreign nations.
According to government oversight documents cited by Bloomberg, congressional lawmakers—including Senator Elizabeth Warren—have submitted formal inquiries demanding full transparency regarding the identity of the third-party money managers overseeing the accounts to rule out insider conflicts of interest under U.S. Securities and Exchange Commission rules.
Key Takeaways for Market Observers
- Net Buyer Status: Despite headline sales in Big Tech, Trump’s accounts were overall net buyers in July, adding at least $43.6 million in assets.
- Broad Sector Diversification: Capital moved away from concentrated cloud computing mega-caps into short-duration fixed income, municipal bonds, and specialized semiconductor stocks.
- Systemic Model Management: The rapid buy-sell cycles (such as selling and repurchasing Microsoft within 72 hours) strongly align with algorithmic portfolio rebalancing rather than strategic macroeconomic forecasting.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

Sovereign AI Strategies Around the World in 2026

Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off

Why Is My Social Security Payment Late? What to Check Before Calling SSA

Bitcoin ETF Outflows: Has Institutional Demand Really Turned?

Xbox Nano Controller 2026: $49.99 Price, Features, November Release

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
Why Is My Social Security Payment Late? What to Check Before Calling SSA
Bitcoin ETF Outflows: Has Institutional Demand Really Turned?
Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off
Sovereign AI Strategies Around the World in 2026
-
Digital6 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital6 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China6 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools