AI
Top 10 US Stocks Profitable This Week: AI, Oil, and a Market Running on Conviction

The Week Wall Street Ran Two Separate Races
On Monday, May 11, three of America’s most-watched indices — the S&P 500, the Nasdaq Composite, and the Dow Jones Industrial Average — closed simultaneously at record highs. By Friday, the party was over for tech, with Nvidia shedding 4.4% and Intel retreating more than six percent in a single session, as Treasury yields spiked and traders remembered that gravity is still a law. Yet even in that churn, a clear list of winners emerged: companies levered to artificial intelligence infrastructure, geopolitically sensitive energy, and a rearming defence sector. Here are the ten US stocks that mattered most this week — and why.
Context: A Market at an Altitude It’s Never Seen Before
The S&P 500 achieved its seventh consecutive weekly gain as of May 11, with the index sitting at 7,412.84. Information Technology, Communication Services, and Consumer Discretionary led sector performance, while the rally was notably narrow — the equal-weight S&P significantly underperformed its cap-weighted counterpart, pointing to concentration in a handful of mega-cap names. Tradingkey
Underneath that headline number, the macro picture is genuinely complicated. First-quarter 2026 real GDP grew at an annualised rate of 2.0%, driven primarily by business investment in AI-related equipment and software, while consumer spending grew at a slower 1.6% pace. The Federal Open Market Committee held the federal funds rate steady at 3.5% to 3.75% at its April meeting, even as Jerome Powell concluded his tenure on May 15 and Kevin Warsh took over as Fed Chair. Oil is the wild card in the room: Brent crude surged 2.9% to above $104 per barrel on May 11 after President Trump described the US-Iran ceasefire as “on life support,” rekindling inflation fears. Tradingkey + 2
The market, in other words, is running two separate races. One is the AI infrastructure buildout, where capital expenditure is still accelerating. The other is a geopolitical energy trade that is increasingly testing consumer resilience. The ten stocks below sit at the intersection of both.
The Top 10 US Stocks Profitable This Week
These are not predictions. They are a snapshot of where market energy, earnings momentum, and institutional conviction converged during the week of May 12–19, 2026.
1. Rackspace Technology (RXT)
The week’s most dramatic story belongs to a company that was written off as a legacy data-centre casualty two years ago. Rackspace Technology surged over 165% in May on the back of hyperscaler partnerships and AI infrastructure capacity expansion, with strong Q1 results and an upgraded full-year outlook triggering a wave of short-covering and institutional buying. Analysts have upgraded the stock to Buy with price targets above $15. It’s a small-cap proxy on the same AI infrastructure theme powering the giants — but with the volatility that comes with a fraction of their market cap. Tradingkey
2. Nvidia (NVDA)
Nvidia reached its all-time high of $236.54 on May 14, 2026, with a market capitalisation of $5.46 trillion as of this week. Every number that matters is pointed upward. In fiscal year 2026, Nvidia’s revenue hit $215.94 billion — a 65.47% increase year-on-year — with earnings of $120.07 billion. The company reports Q1 fiscal 2027 results on May 20. What Jensen Huang says about the forward demand picture may matter more than the print itself. TradingViewStockAnalysis
3. Alphabet (GOOGL)
Alphabet has been the single biggest engine of the S&P 500’s 2026 rally, contributing 1.27 percentage points to the index’s return — more than 20% of the index’s total gain from one name alone. Google Cloud demand is accelerating, Gemini is gaining traction in the enterprise market, and the market is finally giving Alphabet credit for its custom AI chips — TPUs — as a credible alternative to Nvidia’s GPUs. The stock recently leapfrogged Apple for the number two spot by global market capitalisation. ETF.com
4. Arista Networks (ANET)
Arista reported Q1 2026 revenue of $2.71 billion against a consensus of $2.62 billion, representing 35% year-on-year revenue growth, with net income rising to $1.02 billion from $813.8 million. The company raised its full-year 2026 revenue guidance to $11.5 billion. Microsoft, Meta, Alphabet, and Amazon have guided combined capital expenditure above $320 billion for 2026, and every dollar of that spend on GPU clusters eventually flows through the ethernet switching market that Arista dominates. StockAnalysisGotrade
5. Broadcom (AVGO)
Broadcom sits second only to Alphabet in its contribution to the S&P 500’s 2026 gains, adding 0.6 percentage points from an average index weight of just 2.8%. Its custom AI silicon partnerships with Google, Meta, and other hyperscalers give it a structural position in the AI supply chain that is less visible than Nvidia’s but no less valuable. ETF.com
6. Innodata (INOD)
Innodata posted triple-digit gains in May on the back of AI data annotation contracts with large-language-model developers. It’s a pick-and-shovel play on the one input that every AI model needs before it can generate a single token: high-quality labelled training data. With frontier model labs locked in an arms race, demand for that service isn’t slowing. Tradingkey
7. Fluence Energy (FLNC)
Fluence Energy soared close to 30% in the week after HSBC and Roth Capital both upgraded the stock following fiscal second-quarter EBITDA that topped Wall Street estimates — the stock had already rocketed roughly 40% the prior session. AI data centres are power-hungry at a scale that demands grid-scale battery storage solutions. Fluence, which sells exactly that, is riding the intersection of energy demand and AI infrastructure. CNBC
8. Lockheed Martin (LMT)
Lockheed Martin was among the week’s gainers as renewed US-Iran tension kept WTI crude near $105 per barrel, with markets pricing in increased Pentagon outlays for Middle East uncertainty and sustained great-power competition with China. The company announced a quarterly cash dividend of $3.45 per share with an ex-date of June 1. In a week where growth stocks slid on Friday, LMT offered something that few technology names can: a reason to hold that doesn’t depend on the next earnings beat. Tradingkey
9. RTX Corporation (RTX)
The same geopolitical current lifted RTX. The energy sector was the sole sector to post gains on Friday, May 15, rising 1.6%, while defence names including RTX benefited from the market pricing in higher Pentagon spending tied to Middle East friction and the broader US military posture. RTX’s exposure to both the missile stockpile-replenishment cycle and the commercial aerospace aftermarket gives it two separate earnings engines — a rare structural advantage in an uncertain macro environment. Tradingkey
10. P3 Health Partners (PIII)
The month’s most extreme mover. P3 Health Partners posted the highest monthly gain of any NYSE or Nasdaq stock in May 2026, with a rise of 285%. The managed-care company’s surge is event-driven, tied to Medicare Advantage contract developments and a reassessment of its financial trajectory. It is also exactly the kind of move that attracts momentum traders, which can amplify both the upside and the eventual correction. Stocktitan
The Structural Story Behind the Numbers: Why Are These Stocks Really Moving?
Is the AI stock rally sustainable heading into the second half of 2026?
The AI rally’s staying power ultimately rests on one question: are the hyperscalers getting returns on their capital expenditure, or are they building infrastructure that will take years to monetise? The evidence so far favours optimism — cautiously. With approximately 89% of S&P 500 companies having reported Q1 results, the index showed year-on-year revenue growth of 10.4% and earnings growth of 25.3%. Those are not the numbers of a market hallucinating its own prosperity. Tradingkey
Yet the rally’s narrowness is a legitimate concern. When Alphabet alone accounts for more than a fifth of the S&P 500’s total 2026 return, portfolio concentration has moved from a feature to a risk. The market’s gains have been described by analysts as narrow, with the equal-weight S&P significantly underperforming its cap-weighted version — a sign that broader market participation has not kept pace with mega-cap appreciation. CNBC
Featured snippet answer — What are the top performing US stocks this week? The top performing US stocks for the week of May 12–19, 2026 include Rackspace Technology (RXT), Nvidia (NVDA), Alphabet (GOOGL), Arista Networks (ANET), Broadcom (AVGO), Innodata (INOD), Fluence Energy (FLNC), Lockheed Martin (LMT), RTX Corporation (RTX), and P3 Health Partners (PIII). Their gains are driven by AI infrastructure demand, rising defence spending, and geopolitical oil premiums from the ongoing Iran conflict.
The second structural driver — energy and defence — is less discussed but may prove stickier. The Strait of Hormuz carries roughly 20% of global oil and LNG supply, and geopolitical scenarios around the US-Iran ceasefire have become materially priced into markets, with WTI trading near $105 per barrel. That’s not a trade; it’s a repricing of geopolitical risk that could persist for months. Tradingkey
Implications and Second-Order Effects
The week’s price action carries downstream consequences that go well beyond the tick-by-tick narrative.
First, Nvidia’s May 20 earnings report will function as a referendum on the entire AI supply chain. Consensus estimates for the report point to continued data centre revenue growth exceeding 60%, and a beat-and-raise result would likely sustain the infrastructure buildout trade across chips, networking, and cloud computing names. A miss, or a conservative guide on data centre demand, would reprice not just NVDA but Arista, Broadcom, and the broader semiconductor ecosystem simultaneously. As the TradingKey analysis put it bluntly: every AI trade next week is binary to that print. Tradingkey
Second, the spike in 30-year Treasury yields — which jumped above 5.1% on Friday, May 15, the highest since May 2025 — introduces a genuine valuation headwind for long-duration growth assets. Higher yields compress the present value of future earnings. For companies like Arista and Broadcom, whose valuations embed years of high-growth assumptions, that compression isn’t trivial. The bond market, in other words, is not convinced that the AI story justifies current multiples. CNBC
Third, the energy premium from the Iran situation is starting to attract the attention of recession forecasters. Dan Niles, founder of Niles Investment Management, told CNBC on May 15 that ten of the last twelve recessions were preceded by an oil price spike, and that the Federal Reserve’s ability to cut rates could be compromised by oil’s inflationary effect. Traders now lean toward rate hikes as the Fed’s next move — a reversal of expectations that would represent a significant tightening of financial conditions for the consumer. CNBC
For investors in defence stocks like LMT and RTX, the implications are more favourable. Pentagon budgets tend to expand under geopolitical pressure regardless of the broader economic cycle, and the current administration’s posture toward both Iran and China suggests a multi-year tailwind that doesn’t depend on any single quarter’s earnings surprise.
The Bear Case Deserves a Hearing
Not everyone is reading the rally’s signal the same way.
Michael Burry drew attention this week by comparing the Philadelphia Semiconductor Index’s trajectory — up more than 10% in a single week, with 2026 gains reaching 65% — to the run-up that preceded the technology collapse of March 2000. The comparison is inexact: the current semiconductor cycle is underpinned by real revenue growth rather than projected eyeballs. Still, the pace of the move has concentrated enough wealth in a narrow band of names to make a reversal systemically significant. CNBC
The sceptics also point to the rally’s engine. Alphabet’s outsized contribution to S&P 500 returns is, structurally, the same problem the index had in 2020–21 with a different name at the top. Single-name concentration at the index level means passive investors are more exposed to Alphabet’s fortunes than they may realise — and more exposed to any negative development in the EU’s regulatory approach to Google’s AI integration or its search dominance.
There’s a third concern: the retail investor sentiment data suggests that individual traders have been buying heavily into the top momentum names. The SPDR S&P Retail ETF fell more than 6% across the week of May 12–16, its fourth consecutive weekly decline, as investors grew cautious on the consumer backdrop and discretionary spending. A divergence between the market that Wall Street trades and the economy that Main Street inhabits is not indefinitely sustainable. CNBC
That said, earnings remain the ultimate arbiter. With year-on-year earnings growth across the S&P 500 running at 25.3%, the fundamental case for current valuations is more defensible today than it was in early 2000 — when many of the index’s leaders were pre-revenue concepts dressed up as infrastructure plays. Tradingkey
Closing
The ten stocks that led the market this week are not a random collection of fortunate names. They are a map of where capital is flowing in 2026: into the infrastructure of artificial intelligence, into the energy markets shaped by geopolitical fracture, and into the defence complex of an America that is visibly rearming. Whether that map remains accurate depends on what Nvidia says Wednesday evening, what Kevin Warsh signals about the rate path, and whether WTI can stay above $100 without breaking the consumer who ultimately funds all of it.
The week offered a sharp reminder that the best-performing stocks are rarely the whole story. The energy sole sector that rose on Friday while technology fell was not a coincidence. It was a rotation — provisional, perhaps, but pointed. In markets running at this altitude, what leads one week can lag the next. The investors who’ll do well in the second half of 2026 won’t be the ones who bought the top of the momentum list. They’ll be the ones who understood why each stock was on it.
The rally is still alive. The questions are just getting harder.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


AI
PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand
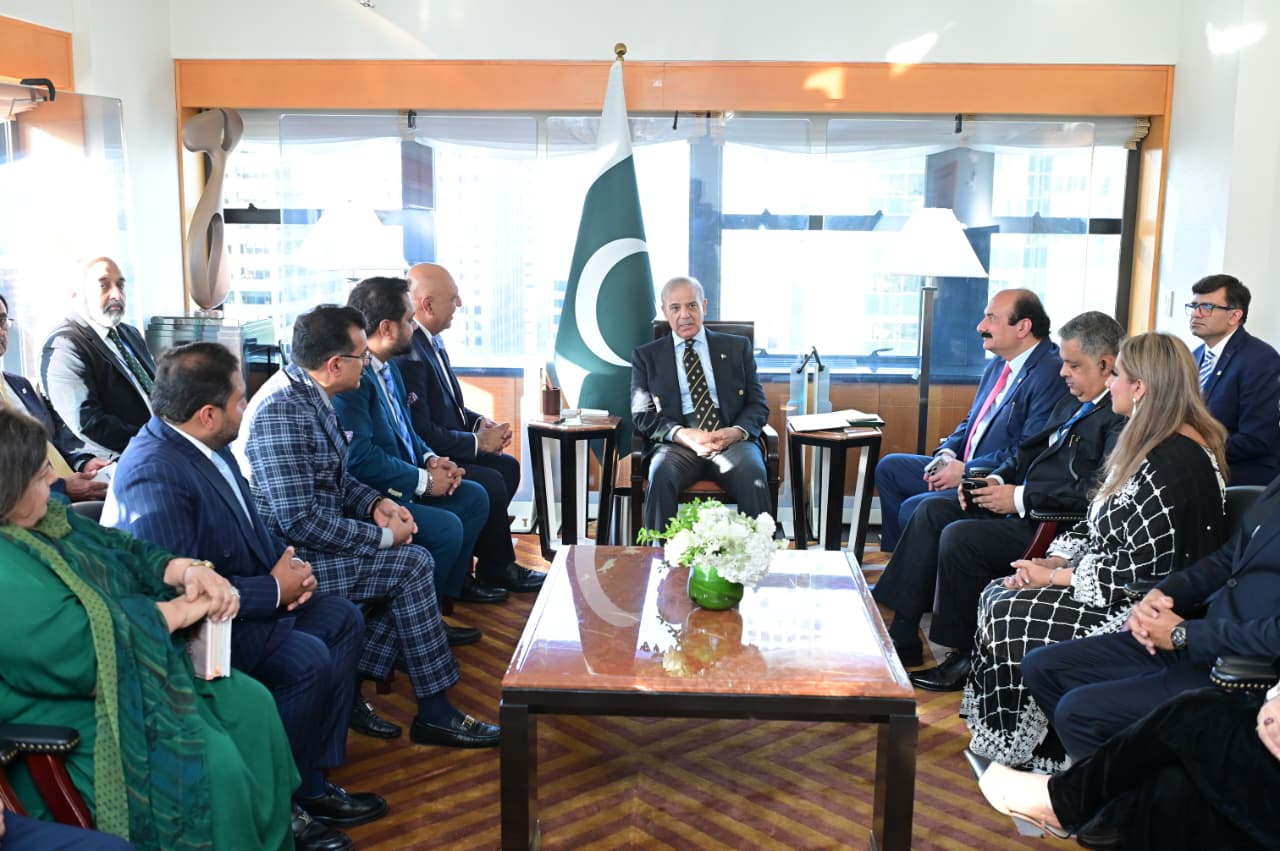
NEW YORK, September 24, 2026 — Prime Minister Muhammad Shehbaz Sharif has invited Pakistani business leaders and professionals based in the United States to invest in Pakistan, highlighting government measures aimed at improving the business environment and encouraging investment.
The invitation came during meetings with Pakistani-American business personalities and professionals working across information technology, artificial intelligence, automobiles, energy, construction and other sectors.
According to the Associated Press of Pakistan (APP), the prime minister said the government was working to create a conducive environment for investment and business activity. He also pointed to reforms at the Federal Board of Revenue (FBR) and measures intended to promote innovation in agriculture.
But the latest appeal to the Pakistani-American business community comes against a broader backdrop: Pakistan is seeking to attract more private investment, expand exports and turn improving macroeconomic conditions into sustained economic activity.
Why Pakistani-American Investors Are Being Targeted
The Pakistani diaspora represents an important source of capital, business expertise and international commercial connections.
Pakistan’s remittance flows demonstrate the economic significance of its overseas population. World Bank data show that Pakistan received approximately $40.48 billion in personal remittances in 2025, equivalent to around 9.9% of GDP.
The State Bank of Pakistan also reported workers’ remittances of approximately $3.66 billion in August 2026, with the monthly series showing substantial inflows throughout 2026.
Investment, however, differs from remittances: it involves deploying capital into businesses, projects or financial assets with the expectation of returns. That distinction makes the government’s effort to attract diaspora entrepreneurs particularly relevant.
IT and AI Among the Sectors in Focus
The technology sector is one of the most significant areas highlighted by the government.
The September 24 meeting included Pakistani-American professionals associated with IT and artificial intelligence, alongside representatives from traditional sectors such as automobiles, energy and construction.
Pakistan’s broader investment framework identifies services, including IT and telecommunications, as areas open to foreign investment. The Board of Investment says Pakistan maintains a liberal investment regime and has mechanisms designed to facilitate local and foreign investors.
For Pakistani-American technology entrepreneurs, potential areas include:
- Software and SaaS businesses
- Artificial intelligence
- IT-enabled services
- Fintech
- Digital infrastructure
- Business-process outsourcing
- Export-oriented technology companies
- Technology startups and venture investment
The attraction for diaspora entrepreneurs is not necessarily limited to providing capital. Entrepreneurs with operations in the United States can potentially bring technology, management expertise, international customers, investment networks and access to global markets.
Agriculture Is Another Priority
Agriculture was also specifically mentioned during the prime minister’s meetings.
APP reported that Shehbaz Sharif said the government was taking measures to promote innovation in agriculture.
That creates potential investment themes around:
- Agri-processing
- Agricultural technology
- Cold-chain infrastructure
- Food processing
- Irrigation technology
- Storage and logistics
- Export-oriented agriculture
- Livestock and dairy
- Farm mechanization
For investors, the distinction between producing agricultural commodities and investing in higher-value processing and supply-chain infrastructure can be particularly important because value-added businesses can connect domestic production with international markets.
What Pakistan’s Investment Framework Offers Foreign Investors
Pakistan’s Board of Investment states that the country follows a liberal investment regime and that its mandate includes promoting, encouraging and facilitating both local and foreign investment.
The Board’s investment information also states that foreign investors can have 100% equity ownership in many areas, although restrictions or specific rules apply to certain sectors.
The government’s Investment Policy 2023 also emphasizes investor protection, investment promotion and expanding Pakistan’s investment-promotion presence abroad, including in the United States.
That policy framework provides important context for the prime minister’s latest appeal to Pakistani-American businesses.
Pakistan Has Also Introduced a New Long-Term Residency Route for Investors
Another development relevant to international investors is Pakistan’s Long-Term Residency (LTR) framework.
According to the Board of Investment, the Foreigners (Long Term Residency) Order, 2025 created a residency-by-investment framework offering five-, seven- and ten-year residency options, subject to eligibility and investment requirements. The BOI says the minimum investment requirement is $50,000, to be materialized within one year through authorized banking channels.
The scheme is separate from the government’s broader investment-promotion policies, but it illustrates the effort to create additional mechanisms for attracting international capital and entrepreneurs.
The U.S.-Pakistan Economic Relationship Adds Another Layer
The appeal to Pakistani-American businesses also comes while economic engagement between Pakistan and the United States remains an important part of Pakistan’s external economic strategy.
In July 2026, Reuters reported that Pakistan had requested a proposed $10 billion U.S. exchange stabilization facility, while discussions were also taking place with U.S. financial institutions including the Export-Import Bank and the U.S. International Development Finance Corporation.
More recently, Reuters reported that Pakistan expected a decision from the United States on the proposed facility while continuing discussions with U.S. EXIM Bank and the Development Finance Corporation on potential projects.
These developments concern government-to-government and institutional financing rather than Pakistani-American private investment, but together they illustrate the wider economic relationship in which the latest business-community outreach is taking place.
What the Government Says About Investment Facilitation
Pakistan’s Board of Investment describes itself as the interface between international and domestic investors and the public and private sectors. Its investment regime information highlights measures intended to reduce the cost and procedural burden of doing business and to facilitate investment.
The government has also continued promoting the Special Investment Facilitation Council and other mechanisms intended to streamline investment processes.
For an investor considering Pakistan, however, the existence of an investment framework does not remove the need for sector-specific due diligence, regulatory approvals, taxation analysis, foreign-exchange considerations and commercial risk assessment.
What Pakistani-American Investors Should Examine Before Investing
The prime minister’s invitation is a political and economic call for greater investment, but prospective investors still need to evaluate individual opportunities on their own merits.
Key issues include:
1. Regulatory requirements
Investment rules differ according to the sector. The BOI notes that some industries are subject to specific restrictions or approvals.
2. Ownership structure
Foreign ownership can reach 100% in many sectors, but exceptions exist, making a sector-specific review necessary before establishing a company.
3. Profit and capital repatriation
Pakistan’s investment framework provides mechanisms for foreign investors to repatriate eligible profits, dividends and investment proceeds, subject to applicable foreign-exchange procedures.
4. Taxation
Investors should examine federal and provincial taxes, withholding obligations, customs duties and sector-specific incentives before committing capital.
5. Infrastructure and operating costs
An attractive investment proposition depends not only on headline incentives but also on electricity, logistics, labor, financing, connectivity and supply-chain costs.
6. Exit strategy
Investors should establish how capital can be repatriated, shares transferred and profits distributed before entering the market.
Pakistan’s Investment Push Extends Beyond the United States
The latest initiative is part of a wider effort to attract overseas Pakistani capital.
Earlier in September 2026, Economic Affairs Minister Ahad Cheema directed officials to develop a structured mechanism through which overseas Pakistanis could participate in viable infrastructure projects, including potential opportunities involving railways, highways, power, civic infrastructure and airports.
In July, Planning Minister Ahsan Iqbal also invited Pakistani-American entrepreneurs, technologists and financiers in Chicago to bring capital, expertise and global networks to Pakistan’s economic development.
This indicates that the September 24 appeal is not an isolated announcement but part of a broader government effort to engage overseas Pakistanis and international investors.
The Bigger Question: Can Investment Follow the Outreach?
The government’s challenge is to convert investment invitations into bankable projects and completed investments.
That requires more than announcements. Investors typically assess regulatory predictability, taxation, currency convertibility, infrastructure, security, financing costs, market size, contract enforcement and the ability to repatriate returns.
The U.S. State Department’s investment-climate assessment has previously identified challenges in Pakistan including regulatory complexity, intellectual-property concerns, changing taxation policies and security-related investor concerns. At the same time, it noted that U.S. companies operate profitably in several Pakistani sectors and that there are no restrictions specifically targeting U.S. investors.
That combination—investment opportunity alongside identifiable investment risks—is important context when assessing the latest government outreach.
What Comes Next for Pakistani-American Investment
Prime Minister Shehbaz Sharif’s September 24 appeal places Pakistani-American businesses at the center of Pakistan’s effort to attract additional investment.
The sectors discussed—AI, IT, energy, automobiles, construction and agriculture—cover both emerging technologies and established parts of the economy.
Pakistan’s investment framework, expanding diaspora-focused initiatives and continuing U.S.-Pakistan economic engagement could provide additional channels for investment. However, the eventual impact will depend on whether proposed opportunities develop into commercially viable projects and whether investors find the regulatory and economic environment sufficiently predictable.
For Pakistani-American entrepreneurs, the latest message from Islamabad is therefore straightforward: the government wants greater diaspora participation not only through remittances, but also through entrepreneurship, capital, technology and long-term investment.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
WASHINGTON — Newly disclosed federal financial records show that investment accounts belonging to President Donald Trump underwent an aggressive portfolio restructuring in July 2026, logging 1,156 individual securities transactions valued between $79 million and $270 million.
While headline attention has focused on multi-million-dollar sales of artificial intelligence and mega-cap tech leaders—including Microsoft, Amazon, and Meta Platforms—a comprehensive examination of the filings reveals a more complex strategy: a transition driven by automated index rebalancing, defensive fixed-income allocation, and concurrent dip-buying.
Executive Overview: July 2026 Disclosure Breakdown
According to analysis of official filings submitted to the U.S. Office of Government Ethics and reported by CNBC, total purchases across the eight managed accounts exceeded total sales.
| Category | Aggregate Value Range | Key Assets / Companies Involved |
| Total July Transactions | $79 Million – $270 Million | 1,156 total trades logged across 8 accounts |
| Total Purchases | $43.6 Million Minimum | Municipal bonds, short-term ETFs, Broadcom, Nvidia |
| Total Sales | $35.6 Million Minimum | Microsoft, Amazon, Oracle, Meta, Northrop Grumman |
| Primary Liquidation Event | July 20, 2026 | Multi-million dollar trims in $MSFT and$AMZN ($5M–$25M bracket each) |
| Quick Re-Entry Trades | July 23, 2026 | Modest buybacks in $MSFT ($100K–$250K) and$AMZN ($1K–$15K) |
Dissecting the Big Tech Trims: Algorithmic Rebalancing vs. Market Sentiment
The largest individual entries in the September filing occurred on July 20, 2026, when investment managers executed broad sell-offs in major cloud and AI infrastructure vendors.
As reported by Quartz, individual sell orders for Microsoft and Amazon each landed in the $5 million to $25 million filing bracket. Simultaneously, managers offloaded between $1 million and $5 million in Oracle stock, alongside position trims in Meta Platforms, Alphabet, and Nvidia.
However, reporting focused exclusively on liquidations misses the broader picture:
- Simultaneous Accumulation: On the very day managers sold Oracle, they added $500,000 to $1 million in Nvidia, while opening $1 million to $5 million positions in enterprise software giants like Salesforce, Intuit, and Marvell Technology.
- Immediate Re-entry: Just three days after the July 20 sell-off, the accounts repurchased positions in Microsoft ($100,001–$250,000 range) and Amazon ($1,001–$15,000 range).
- Fixed-Income Pivot: Significant capital was rotated into defensive yield assets, including the Vanguard Short-Term Bond Index ETF, State Street SPDR Bloomberg International Treasury Bond ETF, and local government bonds such as Miami-Dade County aviation paper.
Financial analysts noted in coverage by Livemint that these multi-directional trades mirror index-tracking models adjusting for market weightings rather than a deliberate directional bet on the tech sector.
White House Clarification: Automated Model Portfolios
Trading volume of this scale by a sitting U.S. president inevitably draws regulatory and public scrutiny. Addressing the disclosures, White House spokesperson Davis Ingle emphasized that the President maintains no personal involvement in daily trade execution.
“The President’s investment portfolio is managed by independent third-party financial institutions through automated model portfolios benchmarked to broad indices like the Schwab 1000,” White House officials stated. “Trading decisions are algorithmically executed without input, direction, or prior knowledge from the President or his family.”
Unlike past presidential administrations that placed assets into blind trusts or single-index mutual funds, the current arrangement relies on third-party wealth managers utilizing direct indexing models.
Regulatory Scrutiny and Geopolitical Overlap
Despite White House assurances, the timing of specific trades has drawn criticism from Capitol Hill.
On July 20, the same day managers sold $250,000 to $500,000 worth of defense contractor Northrop Grumman, President Trump signed an executive order tightening supply chain mandates for defense suppliers and restricting critical material sourcing from foreign nations.
According to government oversight documents cited by Bloomberg, congressional lawmakers—including Senator Elizabeth Warren—have submitted formal inquiries demanding full transparency regarding the identity of the third-party money managers overseeing the accounts to rule out insider conflicts of interest under U.S. Securities and Exchange Commission rules.
Key Takeaways for Market Observers
- Net Buyer Status: Despite headline sales in Big Tech, Trump’s accounts were overall net buyers in July, adding at least $43.6 million in assets.
- Broad Sector Diversification: Capital moved away from concentrated cloud computing mega-caps into short-duration fixed income, municipal bonds, and specialized semiconductor stocks.
- Systemic Model Management: The rapid buy-sell cycles (such as selling and repurchasing Microsoft within 72 hours) strongly align with algorithmic portfolio rebalancing rather than strategic macroeconomic forecasting.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

The iPhone 18 Pro transitions to TSMC’s 2nm process node, integrating a titanium-alloy chassis with advanced graphene vapor chambers. This solves thermal throttling for AAA gaming and AI rendering. However, these material upgrades push the bill of materials higher, indicating an impending increase in Average Selling Price and altering enterprise fleet procurement strategies.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know

How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)

CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]

IPhone 18 Pro Specifications, Pricing, and Thermal Architecture Leaks Analyzed

Pre-IPO Investing Strategies: How Institutional Money is Approaching Anthropic

Smash Bros Ultimate 13.0.5 Patch Notes: What Actually Changed
CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]
Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know
How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)
IPhone 18 Pro Specifications, Pricing, and Thermal Architecture Leaks Analyzed
NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support
World School Summit 2026 Malaysia: 41st Edition
Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings
PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand
-
Digital5 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital5 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China5 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools