Analysis
Stablecoins vs Visa/Mastercard 2026: What’s Really Happening

You’ve probably seen the headline by now: stablecoins processed $33 trillion in transaction volume in 2025, surpassing the combined $25.5 trillion handled by Visa and Mastercard in the same period (Forbes). It’s been repeated across crypto media, investor decks, and conference stages throughout 2026, often framed as evidence that card networks are on borrowed time. It’s also, according to the payments specialists who actually understand how these systems work internally, a comparison that misunderstands what’s happening.
Why the Headline Comparison Is Misleading
Here’s the architectural reality most viral commentary skips entirely: when you swipe a credit card, money doesn’t actually move in that moment — data moves. The transaction sends an authorization request through a chain of intermediaries (payment processor, acquiring bank, Visa’s network, issuing bank) that checks available credit and responds “approved” in about two seconds. Your bank simply places a hold on the funds; no actual money transfer occurs at that point (Crossmint).
Stablecoins operate at a fundamentally different layer of the financial stack — settlement, not authorization. When you send USDC from one wallet to another, authorization and final settlement happen simultaneously in a single blockchain transaction, with no separate clearing process or correspondent banking chain required. That means stablecoins are competing directly with ACH and SWIFT — the settlement and cross-border transfer infrastructure — not with Visa and Mastercard’s authorization network (Crossmint).
The clearest evidence this distinction matters: Visa and Mastercard aren’t fighting stablecoins — they’re actively integrating them into their own settlement infrastructure. Visa expanded its stablecoin settlement program in 2025 to support USDC, PYUSD, USDG, and EURC across four blockchains, already settling over $225 million through these channels specifically to help issuers and acquirers fulfill their existing VisaNet settlement obligations faster (Crossmint).
The Real Battle: Card Networks Are Building Their Own Stablecoin
The far more consequential story, and one that’s received comparatively little mainstream attention, is that Visa, Mastercard, Stripe, and Coinbase have moved to build stablecoin infrastructure rather than simply integrate around existing options from Circle and Tether — the two firms that currently control roughly 80% of the $325 billion stablecoin market (Forbes).
This culminated on June 30, 2026, with the public launch of a consortium called Open Standard, which will issue a dollar-pegged stablecoin called Open USD. The group’s members — Visa, Mastercard, Coinbase, and BNY — structured the initiative around collaborative economics, sharing earnings from the reserves backing the token among members after operational costs, and allowing businesses to mint and redeem the stablecoin without fees or volume limits (Crowdfund Insider).
Zach Abrams, Open Standard’s founding CEO, framed the initiative’s rationale around a specific gap: scaling stablecoins for genuine business use requires a system that’s transparent, economical, high-volume capable, and structured to serve participants’ collective interests — implicitly distinguishing the consortium’s approach from the current Tether/Circle duopoly model.
The strategic logic behind this move is worth understanding clearly: an issuer like Tether or Circle sells a token, but has no consumer brand, no merchant acceptance network, and no balance-sheet relationship with the world’s banks. A network like Visa or Mastercard sells the reason a merchant accepts a payment method in the first place, and already holds those banking relationships. That distribution advantage is something Circle and Tether cannot quickly acquire at any price — and it’s exactly the asset Visa and Mastercard already possess (Forbes).
The Prize Underneath: Reserve Yield
There’s a specific financial mechanism driving much of this consortium activity that deserves more attention than it’s getting: stablecoin reserves — the cash and short-term Treasuries backing every token in circulation — earn interest. At a market approaching $325 billion, that yield runs into billions of dollars annually. Under the GENIUS Act, the US federal stablecoin framework signed into law in 2025, issuers are barred from passing that interest directly to stablecoin holders — meaning the yield accrues entirely to whoever issues the coin and controls its circulation (Forbes). That single provision explains much of the strategic urgency behind Open Standard: it’s not just about payments infrastructure, it’s about capturing a growing pool of risk-free reserve income currently flowing almost entirely to Tether and Circle.
Where Stablecoins Are Already Winning: B2B Payments
Beneath the consumer-facing headlines, the more concrete adoption story is happening in business-to-business payments. B2B stablecoin payments expanded from under $100 million per month in 2023 to more than $6 billion by mid-2025, now representing roughly 60% of genuine economic stablecoin activity rather than speculative crypto trading flows. Around 77% of surveyed companies already use stablecoins for supplier payments, and 41% report cost savings of at least 10% (Forbes). Crucially, this growth continued through 2025 even as speculative crypto trading activity cooled — a pattern that specifically distinguishes a structural infrastructure shift from a hype-driven bubble.
The cost advantage for large B2B transactions is genuinely dramatic: a $10,000 US card transaction typically carries roughly $150-250 in combined interchange, network, and acquirer fees, while the same value moved as USDC on a low-cost blockchain settles for mere cents in transaction gas fees, regardless of transaction size (Eco). That structural advantage is largest precisely for the high-ticket B2B flows where stablecoin adoption is concentrating.
The Underexplored Angle: What This Means for Monetary Sovereignty Beyond the US
Here’s the dimension of this story that gets the least attention in payments-industry coverage, but arguably matters most globally: stablecoins function as a form of “digital dollarization.” Historically, countries experiencing high inflation or currency instability have seen citizens shift toward holding foreign currencies, typically US dollars, as a store of value. Stablecoins now allow this same substitution to happen digitally, letting millions of users in unstable economies access dollar-denominated assets without needing a traditional bank account at all (Global Policy Journal).
For individual users in weak-currency economies, this is entirely rational risk management. But at a systemic level, if this substitution becomes widespread, central banks in those countries — particularly those with weak institutions, high inflation, or limited public confidence in the domestic currency — risk gradually losing part of the monetary ecosystem through which they exercise monetary sovereignty (Global Policy Journal). This is precisely the concern that surfaced in the Bloomberg reporting on concerns over economic sovereignty fueling a search for alternatives to Visa and Mastercard — the underlying anxiety isn’t really about card network fees, it’s about which entities, public or private, ultimately control the rails through which a country’s economic activity flows.
There’s also a quieter, related concern: private payment infrastructure companies (Visa, Mastercard, PayPal, and now stablecoin issuers) don’t issue money themselves, but they control the channels through which money circulates, extracting fees on every transaction that function economically similar to a tax — without being collected by, or accountable to, any government (Global Policy Journal).
The Regulatory Split Shaping Where This Goes Next
Regulatory divergence is already visibly shaping stablecoin adoption patterns globally. In the US, the GENIUS Act has provided the first federal stablecoin framework, favoring bank and licensed issuers. In Europe, MiCA (Markets in Crypto-Assets regulation) is creating a passportable EU-wide licensing framework, but its compliance costs are reportedly pushing some firms out of the European market entirely — Tether itself has refused to comply with MiCA, arguing its reserve rules create systemic banking risk (Payment Expert). Asia is moving at varying speeds, with Singapore, Hong Kong, and Japan each building stablecoin-friendly regulatory frameworks specifically designed to attract this activity to their markets.
What This Means for Businesses and Financial Institutions
For treasury and payments teams, the practical decision is no longer whether to engage with stablecoins — the B2B volume data and consortium formation activity have largely settled that question — but how and when. Building internal stablecoin capability from scratch is expensive and slow; partnering with existing infrastructure providers is faster but creates dependencies; and acquiring specialized firms outright, as Mastercard did with its BVNK purchase, is the most decisive path but the best acquisition targets are disappearing quickly as consolidation accelerates (Forbes).
For businesses specifically operating in emerging markets with currency instability, stablecoin-based supplier payments and remittances already offer measurable cost savings and settlement speed advantages worth evaluating now, rather than waiting for the consumer-facing “Visa vs. stablecoin” debate to resolve — that debate is largely beside the point for B2B use cases already delivering value today.
The Bottom Line
The “stablecoins beat Visa and Mastercard” framing captures headlines but ultimately obscures more than it reveals. Card networks aren’t being replaced — they’re integrating stablecoin settlement into their own infrastructure and building competing stablecoins of their own through consortiums like Open Standard, explicitly to capture the reserve-yield economics currently flowing to Tether and Circle. The genuinely disruptive story is happening in B2B payments and cross-border settlement, where stablecoins are displacing slower, costlier rails like ACH and SWIFT — and in the broader, less-discussed question of what happens to monetary sovereignty in weaker-currency economies as dollar-denominated digital assets become accessible to anyone with a smartphone, no bank account required.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead.
Quick answer: India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
On November 6, 2026, Reuters reported that the Nifty 50 was up about 0.51% while the Nikkei and Kospi suffered steep declines. The immediate explanation was not that India had escaped global financial conditions. A pullback in crude prices, an improvement in foreign portfolio flows and a shift away from AI-heavy exposures created a comparatively favorable mix for Indian equities.
Foreign investors reportedly bought about 150 billion rupees of Indian shares on November 5—the largest single-day net purchase in nearly six years. That is an important flow event, but a single day of buying is not the same as a durable change in ownership or earnings expectations.
Why cheaper oil matters to India
India imports substantial crude oil, so a sustained fall in its import price can reduce pressure on the trade balance and inflation, subject to the rupee, tax policy and refinery margins. It can improve sentiment toward transport, consumption and rate-sensitive stocks. But if oil falls because global demand is collapsing, weaker exports and risk appetite may offset part of that benefit.
The World Bank expects commodity conditions to remain volatile. Investors should therefore distinguish a temporary crude-price dip from a more structural improvement in India’s energy terms of trade.
Foreign buying is a signal, not a guarantee
Global portfolio managers can rapidly shift country weights when a crowded trade sells off. India may attract allocations because of domestic demand and different index composition, but flows can reverse if currency risk rises or earnings disappoint. The market’s resilience should be judged by a series of sessions and broad participation, not one spectacular inflow.
Domestic institutional investors are an additional source of demand. When foreign and local investors take opposite sides, the effect on the index depends on sector weights, liquidity and which large companies are being traded.
The valuation question remains
An index can grow while being expensive. To assess the Nifty 50, consider forward earnings multiples, historical valuation ranges, earnings revisions and expected return on equity. A lofty multiple can be justified by robust profit growth, but its downside increases if expectations are not met. Investors should avoid comparing India’s headline P/E mechanically with markets that have very different sector mixes.
Separate earnings growth driven by real volumes, pricing and margins from one-off gains, currency translation and financing effects. The stronger investment case is one in which earnings breadth improves rather than relying on a small group of index heavyweights.
Banks and IT will determine breadth
Private banks react to loan growth, deposit pricing, asset quality and regulation. IT services companies face technology spending cycles, contracts, exchange rates and hiring demand. The same global AI shock that hurts expensive chip makers can either help IT services through workflow demand or hurt them if customers cut budgets.
Small- and mid-cap shares have different liquidity and valuation risks from the Nifty 50. A headline benchmark recovery with weak market breadth is a weaker signal than simultaneous improvement across several sectors.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | Reuters Nov 6 India markets |
| Interpretive opportunity | Oil versus foreign inflows |
| Secondary question | Sector-level breadth |
| Next verification | Update the closing index level, foreign institutional flows and USD/INR before posting. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
Capital inflows and domestic profits are separate. Foreign fund flows can move prices before the underlying corporate earnings outlook improves. Analysts should identify which signal they are discussing and why it matters. In this article’s subject—Nifty 50 today outlook—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
Headline index gains can coexist with weak breadth. If a handful of large companies drives a rally while smaller shares fall, the apparent strength is less diverse than the benchmark return suggests. Update the closing index level, foreign institutional flows and USD/INR before posting. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Oil versus foreign inflows. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Sector-level breadth. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Risk of mistaking flows for earnings. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
Three tests for the Nifty rally
Foreign inflows meet genuine earnings strength. The best case combines lower sustained energy import costs, corporate profit growth and foreign portfolio confidence. Banks would demonstrate healthy credit demand without deterioration in loan quality, while domestic consumption would support margins. The critical evidence would be several reporting periods of earnings progress, not the November 5 flow spike by itself.
A commodity or currency reversal. If crude rises again or the rupee weakens sharply, inflation expectations and foreign returns could deteriorate. Expensive equity valuations may then amplify selling even in companies with acceptable operating results. Risk is especially pronounced when a market’s recent strength rests on a narrow set of very large stocks or short-lived portfolio rotation.
The market pauses while fundamentals catch up. A long consolidation would not necessarily invalidate India’s structural investment case. It could allow earnings to grow into valuations while global investors digest the AI sell-off. Examine the direction of consensus earnings revisions, financial-sector profitability and market breadth before treating each daily Nifty movement as a turning point.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
A final distinction worth checking
India’s apparent resilience also needs sector and currency discipline. An investor who buys the Nifty in rupees but measures wealth in dollars faces both equity and foreign-exchange movements. A multinational technology exporter may respond differently from a domestic lender when the rupee or U.S. spending changes. Index breadth, banking-sector credit costs and the earnings trajectory of large consumer companies should be placed beside the November foreign-flow figures. Without this context, a sharp positive session can be mistaken for a lasting improvement in risk-adjusted returns.
Questions readers are asking
Why was Nifty stronger than Nikkei and Kospi?
Reuters cited falling oil, foreign buying and a rotation away from heavily AI-linked markets.
Is the Nifty 50 an AI index?
No. It is a diversified large-company Indian equity index with major financial, consumption, industrial and technology exposures.
Should a one-day rise be treated as a breakout?
No. Confirm trends with earnings, breadth, flows and repeated trading sessions.
What can reverse the rally?
Renewed oil inflation, rupee weakness, expensive valuations, weak earnings and abrupt foreign selling.
The judgment
India’s benchmark has shown resilience during a regional technology rout, but valuation and capital-flow tests remain ahead. The most responsible conclusion is conditional: Update the closing index level, foreign institutional flows and USD/INR before posting. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
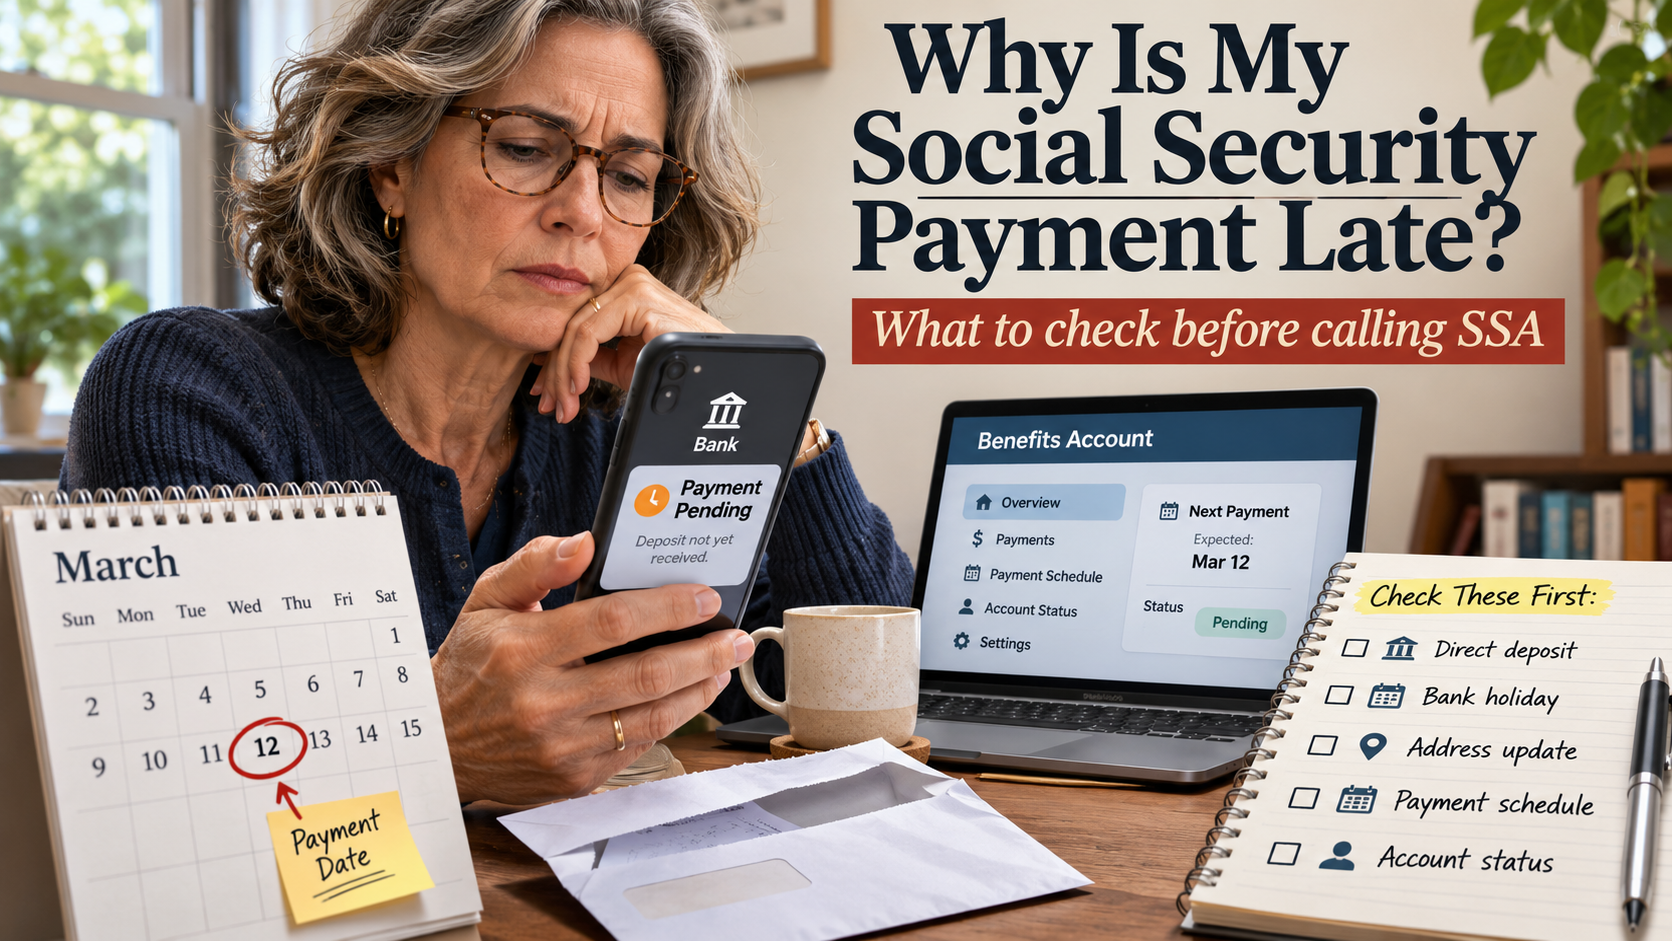
Quick answer: If your Social Security or SSI deposit has not appeared, first confirm the scheduled payment date for your program, then check with your bank or financial institution. The Social Security Administration’s missing-payment FAQ specifically says to contact your bank first for an electronic payment that does not arrive as scheduled. If the money remains missing, call SSA at 1-800-772-1213 or contact a local Social Security office. Do not pay a third party to ‘release’ your benefits.
A delayed deposit can be frightening when it is meant to cover rent, food, medicine or electricity. But the timing problem may have several explanations, and not all mean that the government has stopped the benefit. The most useful response is to determine whether the payment is not yet due, issued but not posted, sent to the wrong account, withheld after an eligibility change, or truly missing. Those categories lead to different next steps.
Step one: make sure today is really your payment date
The most common source of confusion is assuming every Social Security recipient is paid on the third of the month. In reality, the SSA’s published payment rules place most retirement, disability and survivor beneficiaries on one of three Wednesdays, generally based on the relevant birth-date category. Certain people who started benefits before May 1997, and some who receive SSI and Social Security together, have special schedules.
| Recipient category | Ordinary schedule | What to verify |
|---|---|---|
| SSI | First of the month, adjusted for weekends/holidays | Benefit month versus bank deposit date |
| Certain long-standing or dual beneficiaries | Third of the month, subject to adjustments | Whether your award follows the special cycle |
| Regular Social Security, birth date 1–10 | Second Wednesday | Holiday shifts and relevant birth date |
| Regular Social Security, birth date 11–20 | Third Wednesday | Correct calendar month |
| Regular Social Security, birth date 21–31 | Fourth Wednesday | Correct calendar month |
Consult the official benefit calendar rather than a social-media image. A chart that mechanically copies weekday patterns without considering federal holidays can misstate a particular month’s deposit date. For example, the first November 2026 Wednesday cohort was scheduled for November 10 rather than Veterans Day, November 11, under SSA’s holiday adjustment.
Step two: check holiday and weekend adjustments
When a normal payment date falls on a weekend or legal public holiday, Social Security generally issues the payment on the preceding business day. The agency’s holiday FAQ explains the principle. Consequently, a payment may show up earlier than a generic calendar suggests rather than later.
The November 2026 SSI example is instructive. Because November 1 fell on a Sunday, the SSI payment for the November benefit month was scheduled for October 30. Someone searching the bank statement only for a transaction dated November might think a payment is missing even though it arrived at the end of October. That is a question of benefit month versus calendar posting date, not necessarily entitlement.
Different banks may display transaction descriptions and posting times differently. A pending payment, an available balance and a settled transaction are not always the same entry. Use the statement details, not a push notification alone, when checking whether money arrived.
Step three: ask your bank whether a payment was received
SSA’s official advice is clear: if an electronic payment did not arrive on its scheduled date, contact your bank or financial institution first. The institution may be experiencing a delay in posting a deposit it has received. Ask whether there is a pending government benefit payment, whether there is a hold or account problem, and whether the institution has returned a transaction.
It helps to have the scheduled pay date and the last successful benefit transaction on hand. Do not assume the bank can reveal confidential SSA processing information; the bank can explain what its own systems show. If the bank sees no payment, tell SSA that you have already checked. This avoids repeatedly being sent back to the same first troubleshooting step.
If your bank account was recently closed or changed, the payment could have been rejected or returned. The SSA direct-deposit update FAQ describes how recipients can update relevant information, with different options for Social Security versus SSI. Never email complete bank details to an unsolicited address or disclose credentials to someone who calls unexpectedly.
Step four: use SSA’s official missing-payment reporting channel
If the bank cannot resolve the problem and the money is genuinely missing, contact the Social Security Administration. The missing-payment FAQ gives the number 1-800-772-1213 and the TTY line 1-800-325-0778, along with the option to contact a local office. SSA says it will review a qualifying missing-payment report and replace payment if it is due.
When contacting the agency, prepare the benefit type, scheduled pay date, the payment amount you expected, a brief description of what the bank told you and whether you changed accounts. You may need to verify your identity through an official process. The purpose is to give the representative enough information to investigate without sharing sensitive details through insecure channels.
A key distinction is between a payment the agency issued but you did not receive and a payment the agency has not authorized because of a change in eligibility or other adjudicated matter. The remedy for an issued-and-lost deposit is not necessarily the same as the appeal or correction process for a change in benefits.
What if my benefit amount changed rather than disappeared?
A smaller payment can feel like a missing payment when you budget a fixed amount. But Social Security deposits can reflect Medicare premium deductions, tax withholding, repayment of overpayments, adjustments to benefits and other legally applicable changes. SSI payments can also change with income, resources or living arrangements.
Check your most recent award or adjustment notice in your secure my Social Security account if your benefit type permits the relevant online service. Compare the gross entitlement with the net bank deposit. If the gross benefit has changed, ask what notice or determination supports the new amount. If only deductions changed, identify each one before assuming the benefit was reduced arbitrarily.
A person who receives both Social Security and SSI should check each benefit independently. For example, an increase in countable Social Security income may affect the SSI component under means-testing rules. Two deposits can move in different directions without there being a computer error. The SSA overview of SSI explains that income and living circumstances can change payment amounts.
What if the deposit goes to an old bank account?
Contact both your bank and SSA through verified channels. An account closure or change can cause a government deposit to be returned, which may require a reissue after the information is corrected. Do not assume transferring your ordinary paycheck to a new account also updates the Social Security benefit instructions.
The SSA’s direct deposit guidance notes that many retirement, survivors and disability recipients can use their personal online account to change banking information. The same online self-service functionality is not available for all SSI users, who may need to call or visit an office. That difference matters if an article promises one-click bank changes to everyone.
Before submitting a change, review the routing and account number carefully on a legitimate banking document. A single incorrect digit can cause a failure that takes time to investigate. If someone pressures you to reroute a benefit into an account that is not yours, treat that as a fraud warning and contact SSA directly.
How long should I wait before reporting a late payment?
The practical answer is: follow the agency’s current missing-payment instructions. The SSA FAQ asks electronic-payment recipients to contact their bank on the scheduled date if the payment is missing, then reach SSA if necessary. It does not instruct everyone to wait an arbitrary three or five business days before making any inquiry. If a new claim is involved, different processing and notification timelines may apply.
If the missing payment creates urgent hardship, explain that when you contact the agency. An inquiry may not produce an immediate replacement, but a clear description helps the agency understand the consequences. Seek local emergency assistance if you cannot obtain essentials while the problem is investigated; do not turn to a supposed ‘SSA release fee’ offered by a stranger.
Can scams look like payment problems?
Yes. Fraudsters often use worries about a missing deposit to lure victims into clicking links or revealing identification numbers, one-time passcodes and bank details. They may falsely claim a payment is frozen pending a small fee. Official government sites, including SSA’s account portal, should be accessed by typing the address directly or using a saved trusted bookmark.
SSA does not require you to pay a social-media account or intermediary to speed up a routine missing-payment report. Avoid handing over your entire banking login to anyone promising a quicker resolution. Preserve screenshots of suspicious messages if you need to report them, but do not forward sensitive attachments to unknown addresses.
A payment-troubleshooting checklist
Before making the call, write down these five answers: (1) Which program pays you? (2) What is the scheduled date according to SSA? (3) Did the calendar move that date because of a holiday? (4) What does your bank show? (5) Has your address, account or benefit entitlement changed? The sequence stops a simple calendar adjustment from escalating into an unnecessary dispute, while making genuinely missing payments easier to explain.
Keep copies of formal notices and bank transaction entries, but redact sensitive personal numbers if seeking help from a third party. A caregiver assisting another person should also follow SSA’s authorization rules and avoid impersonating the beneficiary during an inquiry.
Frequently asked questions
Why has my Social Security payment not arrived today?
It may not be your scheduled date, the bank may not have posted the payment yet, or SSA may need to review a bank-account or entitlement issue. Verify the schedule, then contact the bank and SSA if needed.
Who should I call first for a missing direct deposit?
SSA’s FAQ recommends contacting the bank first, followed by SSA at 1-800-772-1213 if the problem remains unresolved.
Can SSI be paid in the previous month?
Yes. If the first falls on a weekend or holiday, the monthly SSI payment may arrive on the prior business day, as happened for November 2026.
Does a smaller deposit mean SSA stopped my benefits?
Not necessarily. A deduction or an eligibility-related adjustment can change the net payment. Review notices and distinguish the gross award from the deposited amount.
Can I change my direct deposit online?
Many retirement, survivors and disability beneficiaries can, but online options differ for SSI. Follow SSA’s official instructions.
Bottom line
When a Social Security payment seems late, a measured sequence is more effective than panic or rumors: confirm the official date, check the bank’s posting, inspect notices and then report the problem through SSA. A correct diagnosis protects both your household budget and your personal information. A missing deposit deserves prompt attention, but it should not be confused with a benefit that was issued on a different calendar date.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
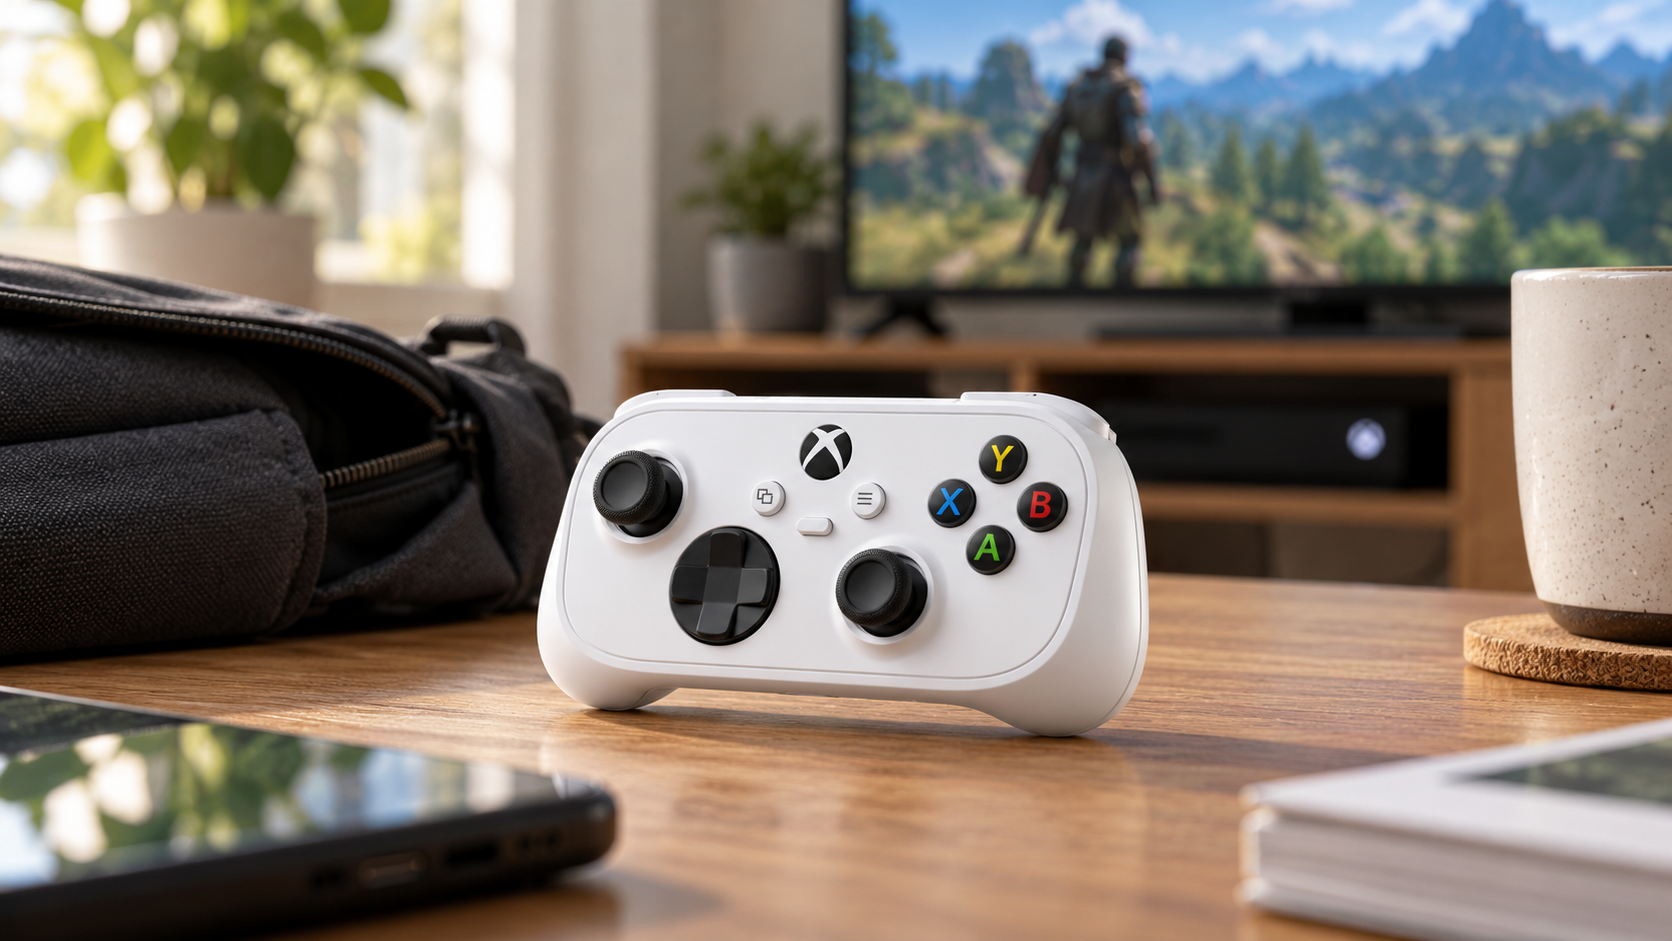
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. For primary-source background, consult Xbox Wire official announcement; Xbox official specification page; Microsoft Store US. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What Microsoft actually announced
The Xbox Wire announcement places the controller at a little over five inches long and approximately 3.5 ounces. Microsoft says it retains 18 standard gameplay inputs despite the smaller chassis. Its list price is $49.99 USD, though local prices and availability differ. It also reports a rechargeable internal battery and a programmable Action Button for tasks such as capturing screenshots or gameplay. This is a real official product launch, not a rumor based on leaked images. Product listings and availability should be checked for the buyer’s country.
Who benefits from a smaller controller
Small-hand ergonomics may be useful for some adults and younger players, but one size does not fit everyone. Grip diameter, shoulder-button reach, thumbstick placement and hand fatigue can matter more than weight alone. A tiny controller may be convenient in a bag but less comfortable during extended sessions for some users. A good review therefore evaluates real people with different hand sizes rather than calling compactness universally better. For parents, compatibility with age-appropriate games and device setup is part of the purchase decision. A low sticker price does not remove the need for usability testing.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026.
Wireless support and device compatibility
Microsoft says the Nano supports Xbox Wireless with compatible consoles and Bluetooth with supported PCs, mobile devices, tablets and smart TVs. That does not mean every game on every device is compatible. Operating-system support, cloud-play subscription availability and game-specific controller input differ. Players should inspect Microsoft’s compatibility notes before purchase, particularly for smart TVs or mobile games that require touch input. The internal battery uses USB-C charging, but the product page notes that the charging cable may be sold separately. Such minor accessories are relevant to total cost and should be visible in product comparisons.
Battery, Action Button and trade-offs
A built-in rechargeable battery changes ownership convenience compared with controllers that use replaceable cells, but it does not guarantee a particular play time. Battery duration depends on wireless mode, features and conditions. Microsoft has not established every real-world endurance result in the launch announcement, so editors should wait for independent testing before making precise claims. The programmable Action Button could reduce menu navigation for popular tasks, but users should verify exactly which shortcuts are available in supported software. Standard inputs may preserve familiar gameplay while smaller thumbstick travel or grip could affect precision; these are review questions, not proven flaws.
Is $49.99 good value?
Value depends on the buyer’s existing devices, preferred games and ergonomics. Someone who already owns a comfortable full-size controller may gain portability without needing to replace their main controller. A family seeking a second or third controller may prioritize price and consistent wireless pairing. A competitive player might instead favor adjustable controls, wired latency or premium hardware that the Nano does not claim to provide. Compare after-sales warranty, charging accessory costs, import taxes, local support and return rules. The launch is best understood as a compact mainstream option, not a universal upgrade from every other Xbox controller.
Worked example: how to interpret a difficult headline
Two buyers can reach different conclusions at the same price: a traveler wanting a lightweight Bluetooth controller may value the smaller form factor, while someone who plays long racing sessions on a console may prefer a larger grip. A useful review explains this trade-off rather than ranking products solely by price or feature count. Check a local store’s return policy in case the fit is unsuitable. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Official Xbox Nano | Small, $49.99 list price, rechargeable and portable. |
| Full-size standard controller | Potentially different hand fit and battery arrangements. |
| Premium controller | May add advanced customization at a higher price. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- November 2026 retail availability and regional pricing.
- Independent battery-life and ergonomic testing.
- Compatibility changes via software updates.
- Store returns, warranty and accessory requirements.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
Specifications make the Nano controller appealing, but personal hand fit, device compatibility, charging accessories, and return policy determine its value. The editorial differentiator is a use-case comparison rather than a copied feature list or an unsupported claim about measured latency.
Frequently asked questions
What is the Xbox Nano price?
Microsoft lists $49.99 USD before location-specific taxes and differences. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
When does Xbox Nano launch?
Microsoft describes November 2026 availability, with a specific November 4 date on its US store listing. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it have all the standard buttons?
Microsoft says it includes 18 standard gameplay inputs. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it work on PC and phones?
It supports Bluetooth on compatible devices; verify software and game compatibility. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off

Why Is My Social Security Payment Late? What to Check Before Calling SSA

Bitcoin ETF Outflows: Has Institutional Demand Really Turned?

Xbox Nano Controller 2026: $49.99 Price, Features, November Release

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know

How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)
Why Is My Social Security Payment Late? What to Check Before Calling SSA
Xbox Nano Controller 2026: $49.99 Price, Features, November Release
Bitcoin ETF Outflows: Has Institutional Demand Really Turned?
Nifty 50 Outlook: Why India Is Defying the Asian Tech Sell-Off
-
Digital6 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital6 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China6 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools