Business
The Payment Revolution: How Smart Startups Are Weaponizing Payment Infrastructure in 2025

Discover the 10 payment solutions driving startup success in 2025. Expert analysis backed by market data on Stripe, embedded finance, stablecoins, and strategic infrastructure choices.
The payment stack has quietly become the most critical competitive advantage for startups—and most founders are getting it catastrophically wrong.
When Stripe processed its trillionth dollar in transactions last year, something fundamental shifted in the startup ecosystem. Payment infrastructure stopped being back-office plumbing and became the strategic moat separating winners from also-rans. Today, 45% of U.S. e-commerce businesses now use Stripe as their primary processor, yet this represents just the tip of a far more profound transformation reshaping how startups handle money.
The numbers tell a compelling story: the embedded finance market exploded to $146.17 billion in 2025, racing toward $690 billion by 2030 at a staggering 36.4% compound annual growth rate.
Cross-border payment flows are projected to hit $222.1 billion by year-end. Meanwhile, payment fraud losses surpassed $40 billion globally, making security not just a feature but a survival imperative.
After spending fifteen years covering fintech evolution—from the pre-mobile payment Stone Age through today’s AI-powered settlement networks—I’ve watched countless startups either soar or stall based entirely on their payment infrastructure choices. The difference between a $10 million Series A and a failed fundraise often comes down to one question: Can you collect money efficiently, globally, and profitably?
Here’s my definitive analysis of the ten payment solutions actually moving the needle for startups in 2025, backed by data, real-world performance metrics, and hard-earned strategic insights.
Why Payment Infrastructure Became Your Most Important Hire
Three seismic shifts have elevated payment systems from commodity to competitive weapon:
The Embedded Finance Explosion: Financial services are no longer separate from product experiences. Shopify evolved from e-commerce platform to comprehensive business operating system by embedding payments, loans, and banking. The result? Over 50% of North American independent software vendors now offer embedded payments directly in their platforms, driving both revenue and retention through the roof.
The Compliance Cost Crisis: Payment fraud detection alone costs businesses billions annually, with 71% of companies reporting payment fraud attacks in 2023. Regulatory complexity—from PSD2 in Europe to evolving AML directives globally—means 98% of financial institutions report rising compliance costs. Getting this wrong doesn’t just cost money; it kills companies.
The AI Revolution in Risk Assessment: Machine learning now processes over 500 million daily API requests for platforms like Stripe, enabling real-time fraud detection and personalized financial products. AI-driven credit scoring is opening markets previously deemed too risky, particularly in underserved segments like gig workers and emerging market SMEs.
The startups winning today aren’t just accepting payments—they’re using payment data to drive product decisions, using settlement speed as a retention tool, and turning transaction flows into predictive analytics that inform every business decision.
Top 10 Payment Solutions Defining the 2025 Landscape
1. Stripe Treasury – The Full-Stack Financial Operating System
What It Solves: Startups need more than payment processing—they need embedded banking that turns cash flow into strategic advantage.
Stripe’s market position speaks volumes: 17.15% global market share, processing $1.4 trillion in 2024 (up 40% year-over-year), with a valuation now recovered to $91.5 billion. But the real story is Stripe Treasury, which embeds banking-grade financial services directly into applications.
Key Capabilities:
- Bank accounts with FDIC insurance through partner banks
- Real-time payment tracking and automated reconciliation
- Built-in spend management and multi-currency support
- Developer-friendly APIs that reduce integration time from months to days
By The Numbers: Stripe now serves 1.35 million live websites globally, with 80% of America’s largest software companies using the platform. Processing volume increased 133% during the pandemic year alone, proving its scalability during crisis moments.
Strategic Application: A SaaS startup using Stripe Treasury cut their payment reconciliation time by 87% while adding same-day settlement for customers—turning a back-office function into a sales differentiator. The platform’s 99.999% uptime means financial operations literally never stop.
When To Choose This: You’re building a global-first product, need developer flexibility, and plan to embed financial services into your core offering. The 2.9% + 30¢ transaction fee becomes trivial when weighed against operational efficiency gains.
2. Adyen – Enterprise-Grade Unified Commerce Platform
What It Solves: Multi-channel commerce complexity and cross-border payment optimization at scale.
While Stripe dominates startups, Adyen owns enterprise adoption with a different philosophy: unified commerce across every channel and geography. Their single platform handles in-store, online, and mobile payments with consistent experience and consolidated data.
Key Features:
- 250+ payment methods across 150+ transaction currencies
- Real-time fraud prevention using machine learning across billions of transactions
- Network tokenization reducing payment failures by 2-5 percentage points
- Dynamic routing optimizing acceptance rates per transaction
Real-World Impact: Adyen’s AI-powered fraud prevention analyzes patterns across its entire network, meaning each merchant benefits from threat intelligence gathered from global transaction flows. This network effect becomes more valuable as the platform scales.
Strategic Consideration: Best for startups planning rapid international expansion or those in high-risk verticals needing sophisticated fraud tools. The platform supports 45 countries with local acquiring, essential for optimizing payment acceptance rates in diverse markets.
Market Position: Adyen’s focus on enterprise clients means higher barriers to entry but also more robust infrastructure for startups planning to scale quickly. Their embedded finance capabilities rival Stripe’s while offering stronger omnichannel support.
3. PayPal Complete Payments – The Trust Advantage
What It Solves: Consumer trust barriers and immediate credibility for new brands.
PayPal still commands 45% of the online payment processing market—more than double Stripe’s 17%. This isn’t just legacy; it’s strategic asset. Consumer trust remains the invisible conversion killer, and PayPal’s brand recognition removes that friction instantaneously.
The Data Story: PayPal’s acquisition of Honey (cashback rewards) and expansion of Venmo (peer-to-peer payments) creates an ecosystem play that goes far beyond transaction processing. They’re building embedded commerce experiences where payments, rewards, and social proof intertwine.
Key Advantages:
- Instant brand trust with consumers globally
- Buyer protection programs reducing purchase anxiety
- BNPL (Buy Now, Pay Later) capabilities through PayPal Pay Later
- Cryptocurrency transaction support for future-forward positioning
Use Case Reality: E-commerce startups consistently report 20-30% higher conversion rates when offering PayPal as a checkout option alongside card payments. The brand simply removes mental friction at the critical moment.
When It Makes Sense: Consumer-facing products where trust is paramount, or businesses targeting demographics with high PayPal adoption. The higher per-transaction fees (typically 3.49% + fixed fee) are offset by conversion lift and reduced cart abandonment.
4. Wise Business – Cross-Border Payment Specialist
What It Solves: The 5-10% cross-border payment tax killing global startup margins.
Traditional international payments are highway robbery—5-10% fees, 3-5 day settlement times, opaque exchange rates. Wise (formerly TransferWise) built a different model using multi-currency accounts and peer-to-peer matching that cuts costs by 80%.
The Wise Advantage:
- Real mid-market exchange rates without markup
- Multi-currency accounts with local bank details in 50+ countries
- API integration for automated international payroll and supplier payments
- Transparent, upfront fees typically 0.35-1% vs. 5-8% for traditional banks
Market Context: With cross-border payments projected to reach $222.1 billion in 2025, efficient international settlement becomes existential for globally distributed teams. Wise processes billions monthly while saving customers millions in hidden fees.
Real Application: A remote-first startup with contractors in 23 countries switched from traditional banks to Wise, cutting international payment costs by 73% while reducing settlement time from 5 days to 24 hours. The speed improvement alone reduced contractor churn by creating reliable payment schedules.
Strategic Fit: Essential for startups with international contractors, suppliers, or customers. The cost savings at scale often exceed what you’d save through aggressive vendor negotiation elsewhere in the stack.
5. Checkout.com – The Flexible Infrastructure Play
What It Solves: Payment orchestration for businesses needing ultimate flexibility and control.
Checkout.com’s approach differs fundamentally: rather than locking you into their ecosystem, they provide payment orchestration letting you route transactions across multiple processors while maintaining unified reporting and reconciliation.
Technical Sophistication:
- Dynamic routing across 12+ payment processors
- Local acquiring in 150+ currencies
- Advanced retry logic and cascading when primary processors fail
- Unified API abstracting processor complexity
Why This Matters: Payment processor outages cost e-commerce businesses $5,600 per minute on average. Checkout.com’s redundancy architecture means you’re never dependent on single processor uptime. More importantly, you can optimize for cost vs. acceptance rate on a transaction-by-transaction basis.
Performance Data: Businesses using intelligent routing see acceptance rate improvements of 3-7 percentage points—directly impacting revenue without changing anything about the product or marketing.
Ideal For: High-volume businesses where payment optimization becomes a meaningful profit center, or companies operating in emerging markets where payment landscape fragmentation demands flexibility.
6. Razorpay – The India-First Full-Stack Solution
What It Solves: India’s unique payment complexity and SME banking desert.
India’s digital payment explosion—UPI transactions grew from 920 million in 2017-18 to 83.75 billion in 2022-23 (147% CAGR)—created unique infrastructure needs. Razorpay became India’s only full-stack financial solutions company by understanding local market dynamics better than global players.
India-Specific Capabilities:
- Complete UPI integration and Bharat QR support
- Automated GST reconciliation (critical pain point)
- Localized payment methods (wallets, net banking, cards)
- First completely digital onboarding for startups
Market Position: Razorpay serves over 5,000 Indian establishments and has expanded internationally with Curlec by Razorpay in Malaysia, proving the model’s regional portability. They’re addressing India’s $45 billion embedded finance opportunity projected to grow at 45% CAGR.
Strategic Value: For startups targeting Indian consumers or operating in South Asian markets, local payment method support isn’t optional—it’s existential. Razorpay’s deeper integration with Indian banking rails provides acceptance rates global players simply cannot match.
When To Use: India market focus, need for local payment methods, or building for price-sensitive segments where transaction fees matter materially.
7. Stablecoin Payment Rails (BVNK, Rain, Noah) – The Future of B2B Settlements
What It Solves: The 2-5 day settlement lag and currency conversion costs crushing B2B cash flow.
The most profound shift in 2025 isn’t another payment API—it’s institutional embrace of stablecoin settlement infrastructure. Companies like BVNK, Rain, and Noah are building payment rails enabling instant, near-zero-cost cross-border transactions using USDC and other regulated stablecoins.
The Paradigm Shift: Traditional B2B payments take days and cost hundreds in fees. Stablecoin rails settle in seconds for dollars. This isn’t cryptocurrency speculation—it’s infrastructure replacement for an antiquated correspondent banking system.
Key Advantages:
- Near-instant settlement (seconds vs. days)
- Minimal transaction costs (pennies vs. percentages)
- 24/7/365 operation (no banking hours or holidays)
- Transparent, auditable settlement trails
Market Momentum: With regulatory tailwinds accelerating—Hong Kong’s stablecoin sandbox, Singapore’s dual-licensing framework—institutional adoption is exploding. Major banks now offer tokenized asset services, while platforms like RedotPay integrate crypto payments via Visa and Mastercard networks.
Real-World Case: A software company with global enterprise clients switched international invoicing to stablecoin rails, reducing payment processing time from 7-10 days to under 10 minutes while cutting forex fees by 95%. The cash flow acceleration alone improved their working capital position dramatically.
Consider This If: You handle significant B2B cross-border transactions, need instant settlement for operational reasons, or serve markets with banking infrastructure challenges. The regulatory landscape is maturing rapidly, making 2025 the inflection point for mainstream adoption.
8. Klarna – BNPL as Acquisition Channel
What It Solves: High-ticket purchase hesitation and conversion optimization for premium products.
Buy Now, Pay Later isn’t just about deferred payment—it’s a customer acquisition channel hiding in plain sight. Klarna’s 150 million global users actively seek out merchants offering their preferred payment method, creating organic discovery benefits beyond the transaction itself.
Strategic Value Proposition:
- 30-40% increase in average order value for participating merchants
- Access to Klarna’s active shopper marketplace
- Zero credit risk (Klarna assumes default risk)
- Younger demographic acquisition (75% of users under 40)
The Business Model: Klarna makes money from merchant fees (typically 2.49-3.29% + $0.30) while offering consumers interest-free installments. They’re betting on volume and merchant marketing value exceeding credit losses—a bet that’s working with their unicorn valuation.
Performance Metrics: E-commerce businesses report BNPL options increasing conversion rates by 20-30% and average cart value by 35-45%. The psychology is simple: breaking a $400 purchase into four $100 payments removes the pain of payment while maintaining product appeal.
Strategic Fit: Consumer products priced $100-$2,000 where purchase consideration is primary friction. Fashion, electronics, furniture, and experiences see highest impact. B2B startups have less application unless selling to SMEs with cash flow constraints.
Caution: BNPL creates customer expectations for flexibility across all purchases. Once offered, removing it often causes conversion rate drops. Treat it as permanent infrastructure, not temporary promotion.
9. Stripe Atlas + Mercury – The Complete Formation Stack
What It Solves: The international founder’s American incorporation and banking nightmare.
Building a U.S. company from abroad historically meant $5,000+ in legal fees, weeks of bureaucratic maze navigation, and banking relationships requiring physical presence. Stripe Atlas combined with Mercury banking collapses this to 48 hours and $500.
The Complete Package:
- Delaware C-Corp formation with IRS tax ID (EIN)
- U.S. bank account through Mercury (no physical presence required)
- Stripe payment processing pre-configured
- Stock certificate issuance and 83(b) election guidance
- $10,000 in partner discounts (AWS, Google Cloud, etc.)
Why This Matters: Over 140 countries now access this service, democratizing U.S. market entry for global founders. Mercury adds FDIC-insured banking, corporate cards, and automated bookkeeping—the complete financial operations stack for remote teams.
The Network Effect: More than 50,000 Atlas companies have been created, forming a global founder network. This community value often exceeds the direct service value, providing peer learning and partnership opportunities.
Real Impact: An Indian AI startup used Atlas + Mercury to incorporate and access U.S. payment rails within 72 hours, enabling them to charge enterprise customers immediately rather than waiting months for traditional incorporation. First customer revenue arrived within a week.
Perfect For: Non-U.S. founders targeting American customers, SaaS businesses needing U.S. entity structure for enterprise sales, or anyone wanting modern digital-first banking infrastructure. The combination costs roughly $500 setup + monthly fees but eliminates traditional formation complexity entirely.
10. Usage-Based Billing Platforms (Stripe Billing, Chargebee) – The SaaS Revenue Optimization Layer
What It Solves: Complex subscription management, failed payment recovery, and revenue leakage.
Every SaaS company loses 5-10% of revenue to failed payments, billing complexity, and churn. Specialized billing platforms don’t just process subscriptions—they’re revenue optimization engines preventing millions in leakage.
The Forrester Recognition: Stripe Billing was named Leader in both The Forrester Wave: Recurring Billing Solutions (Q1 2025) and by Gartner. This institutional validation matters because billing complexity scales exponentially with business model sophistication.
Core Capabilities:
- Dunning management (automated retry logic for failed payments)
- Usage-based billing and metering for consumption models
- Revenue recognition and accounting automation
- Multi-currency and tax compliance automation
- Subscription lifecycle management (upgrades, downgrades, pausing)
Financial Impact: Companies implementing sophisticated dunning recover 60-70% of failed payments that would otherwise be lost. For a $10M ARR SaaS company losing $500K annually to failed payments, that’s $300-350K recovered revenue.
The Stripe Billing Story: Stripe reports their billing suite is on track for $500 million annual run rate, up from essentially zero five years ago. This explosive growth reflects the massive pain point around subscription complexity, particularly for usage-based and hybrid models.
Strategic Application: A vertical SaaS company switched from homegrown billing to Stripe Billing, immediately recovering $180K in failed payments annually while reducing engineering time spent on billing logic by 80%. The freed engineering capacity went directly to product development.
When Essential: Any subscription or usage-based business model, particularly those with:
- Multiple pricing tiers and add-ons
- Usage-based components (API calls, storage, transactions)
- International customers requiring multi-currency
- Complex revenue recognition requirements
Trying to build this internally is classic founder trap—it always takes 10x longer and distracts from core product development.
The Strategic Framework: Choosing Your Payment Stack
Payment infrastructure selection isn’t one-size-fits-all. Here’s how to think about it by startup stage and profile:
Pre-Seed to Seed ($0-$2M Raised)
- Primary Goal: Speed to market and operational simplicity
- Recommended Stack: Stripe for payments + Mercury for banking + Wise for international
- Why: You need to prove product-market fit, not optimize payment operations. Stripe’s developer experience gets you live in days. Mercury handles banking basics. Wise solves international contractors.
- Cost Reality: You’ll pay higher percentage fees but save thousands in engineering time.
Series A ($2M-$10M Raised)
- Expansion Needs: International growth, specialized payment methods, beginning optimization
- Recommended Stack: Stripe or Adyen (depending on B2B vs. B2C) + specialized billing (Chargebee or Stripe Billing) + regional specialists as needed
- Strategic Additions: Consider Klarna for e-commerce, stablecoin rails for B2B international, Razorpay if India-focused
- Why: You’ve proven product-market fit and need infrastructure supporting scale. Payment optimization now materially impacts unit economics.
Series B+ ($10M+ Raised)
- Optimization Phase: Payment orchestration, multi-processor redundancy, data-driven routing
- Recommended Stack: Payment orchestration layer (Checkout.com) + multiple processors + specialized billing + AI-powered fraud prevention
- Focus Areas: Acceptance rate optimization (every percentage point matters at scale), fraud prevention ROI, settlement speed as competitive advantage
- Why: At high transaction volumes, payment infrastructure becomes profit center, not cost center.
Geography-Specific Considerations:
- India/South Asia: Razorpay is non-negotiable for local payment methods and regulatory compliance
- Global B2B: Stablecoin rails should be in pilot testing immediately—competitive advantage within 12 months
- Consumer E-commerce: PayPal + Klarna combination typically delivers best conversion rates
- Mobile-First: Ensure payment stack supports 62% of transactions now happening mobile (per 2025 data)
The Emerging Trends Reshaping 2025-2027
AI-Powered Underwriting at Point of Sale
Machine learning models now assess creditworthiness using real-time transaction data rather than static credit scores. This enables instant lending decisions embedded directly in checkout flows. Expect AI underwriting to unlock $15-20 billion in previously unqualified consumer lending by 2027.
Real-Time Payment Rails Go Mainstream
The Federal Reserve’s FedNow service joined instant payment networks globally. By late 2025, real-time settlement becomes baseline expectation rather than premium feature. This fundamentally changes working capital management for businesses.
Open Banking Transforms Data Access
PSD2 in Europe demonstrated how standardized APIs unlock innovation. Similar frameworks spreading globally mean payment platforms increasingly access banking data for better fraud detection, credit decisions, and personalized offers. The data advantage becomes the moat.
Regulatory Consolidation Around Stablecoins
Hong Kong’s sandbox, Singapore’s licensing framework, and U.S. regulatory clarity emerging in 2025 all point toward institutional-grade stablecoin infrastructure. This transforms cross-border payments from days/dollars to seconds/pennies. Companies building on this now win disproportionately.
Embedded Finance Becomes Universal
The $146 billion embedded finance market racing to $690 billion by 2030 isn’t hype—it’s infrastructure shift. Every SaaS platform will offer financial services within 5 years. Early movers in vertical-specific financial embedding are building unassailable competitive positions.
Payment Data as Product Input
Forward-thinking startups use payment data as product development intelligence. Transaction patterns reveal feature usage, churn signals, expansion opportunities, and market trends invisible in traditional analytics. Payment infrastructure becomes business intelligence layer.
The Hard Truth About Payment Infrastructure
After analyzing hundreds of startups over fifteen years, I’ve seen this pattern repeatedly: companies that treat payments as commodity typically plateau at $10-20M ARR. Companies that view payment infrastructure as strategic asset routinely scale past $100M.
The difference isn’t the technology—it’s the mindset. Payment infrastructure touches every customer interaction, reveals business health in real-time, and increasingly determines whether you can serve customers profitably across geographies.
Three questions reveal whether you’re thinking strategically about payments:
- Can your payment stack tell you which customer segments are most profitable BEFORE you do cohort analysis? If not, you’re missing real-time intelligence that should inform pricing and acquisition strategy.
- Does payment acceptance rate factor into your geographic expansion decisions? It should—entering a market where you can’t accept 85%+ of preferred payment methods is burning capital.
- Have you modeled how settlement speed impacts your cash conversion cycle? Two-day faster settlement can meaningfully improve working capital, especially for inventory businesses.
The startups winning in 2025 aren’t just choosing payment processors—they’re architecting financial infrastructure as core competitive advantage. They’re embedding banking services into products, using AI-powered fraud detection to enter riskier (but higher-margin) markets, and leveraging payment data for business intelligence.
The Bottom Line
Payment infrastructure stopped being back-office plumbing the moment Stripe processed its first trillion dollars. Today it’s the strategic moat separating market leaders from everyone else.
The ten solutions profiled here represent fundamentally different approaches to the same challenge: how do you collect money efficiently, globally, and profitably while creating customer experiences so seamless they become forgettable?
For pre-seed startups, the answer is speed to market—get live fast with Stripe and Mercury. For Series A companies, it’s strategic expansion—add specialized tools for your specific use case. For later-stage companies, it’s optimization—build payment orchestration that compounds competitive advantages.
But here’s what matters most: the payment landscape is consolidating around winners while simultaneously fragmenting around specialized solutions. You need both the simplified developer experience of platforms like Stripe AND the specialized capabilities of providers like Wise for international, Klarna for BNPL, or stablecoin rails for B2B.
The companies that will dominate the next decade are being built right now on payment infrastructure that didn’t exist five years ago. Embedded finance, AI underwriting, real-time settlement, and cryptocurrency rails are moving from experimental to essential. The question isn’t whether to adopt these technologies—it’s how quickly you can integrate them before competitors do.
The payment revolution is here. The only question left: Are you building on infrastructure that compounds your advantages or holds you back?
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


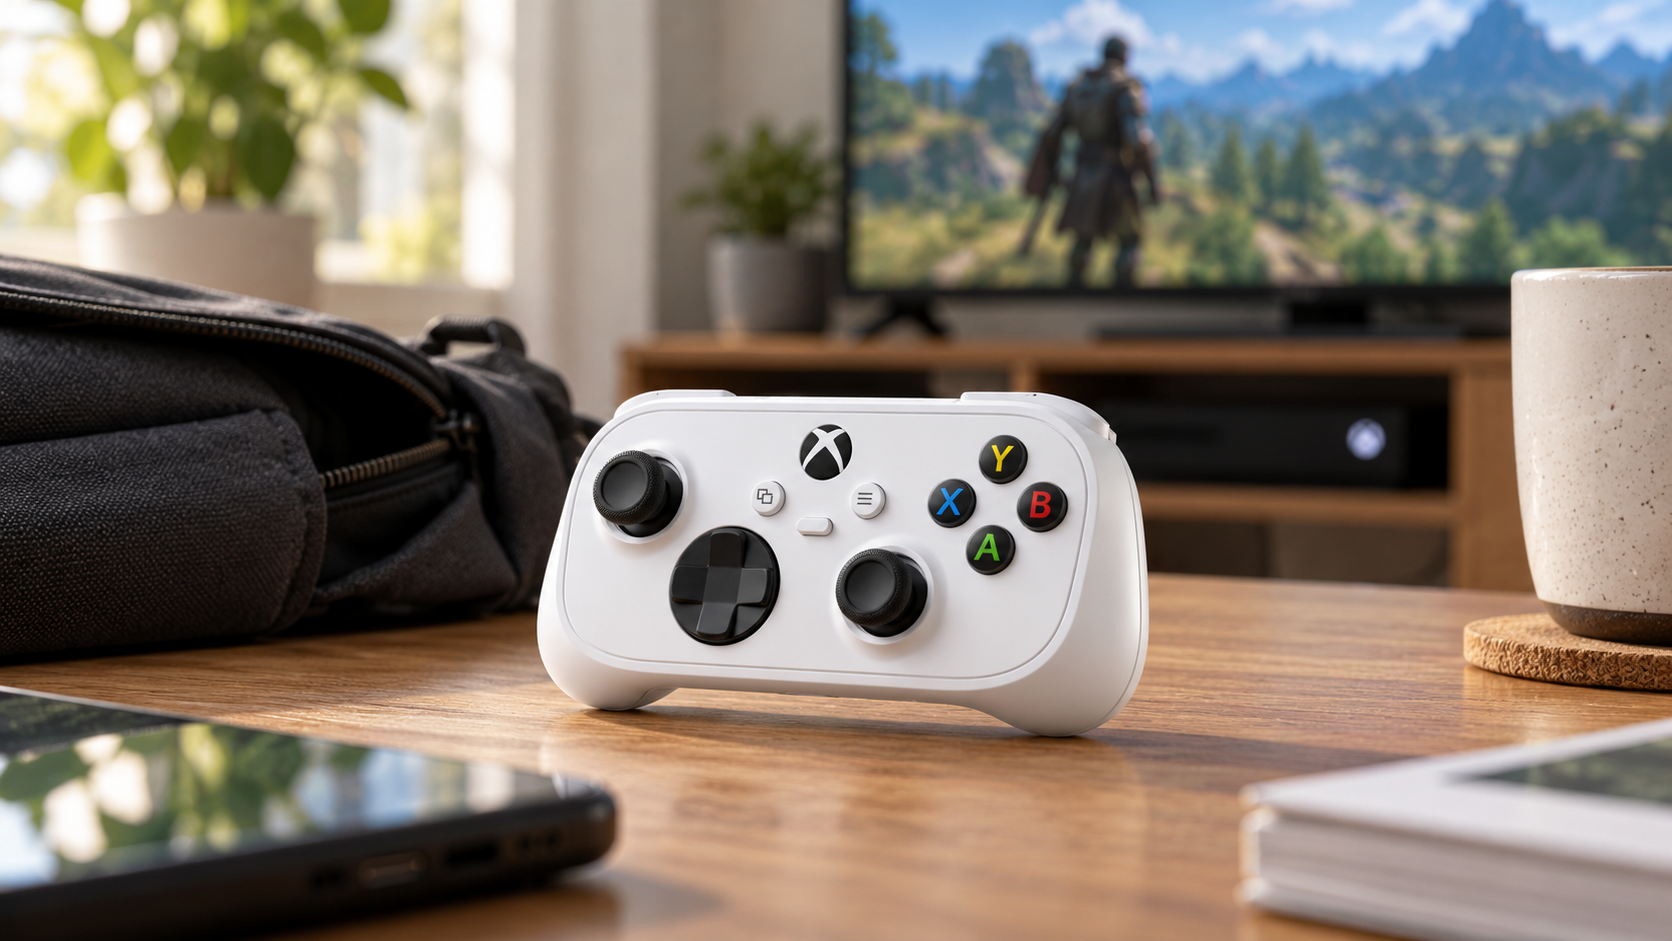
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. For primary-source background, consult Xbox Wire official announcement; Xbox official specification page; Microsoft Store US. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What Microsoft actually announced
The Xbox Wire announcement places the controller at a little over five inches long and approximately 3.5 ounces. Microsoft says it retains 18 standard gameplay inputs despite the smaller chassis. Its list price is $49.99 USD, though local prices and availability differ. It also reports a rechargeable internal battery and a programmable Action Button for tasks such as capturing screenshots or gameplay. This is a real official product launch, not a rumor based on leaked images. Product listings and availability should be checked for the buyer’s country.
Who benefits from a smaller controller
Small-hand ergonomics may be useful for some adults and younger players, but one size does not fit everyone. Grip diameter, shoulder-button reach, thumbstick placement and hand fatigue can matter more than weight alone. A tiny controller may be convenient in a bag but less comfortable during extended sessions for some users. A good review therefore evaluates real people with different hand sizes rather than calling compactness universally better. For parents, compatibility with age-appropriate games and device setup is part of the purchase decision. A low sticker price does not remove the need for usability testing.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026.
Wireless support and device compatibility
Microsoft says the Nano supports Xbox Wireless with compatible consoles and Bluetooth with supported PCs, mobile devices, tablets and smart TVs. That does not mean every game on every device is compatible. Operating-system support, cloud-play subscription availability and game-specific controller input differ. Players should inspect Microsoft’s compatibility notes before purchase, particularly for smart TVs or mobile games that require touch input. The internal battery uses USB-C charging, but the product page notes that the charging cable may be sold separately. Such minor accessories are relevant to total cost and should be visible in product comparisons.
Battery, Action Button and trade-offs
A built-in rechargeable battery changes ownership convenience compared with controllers that use replaceable cells, but it does not guarantee a particular play time. Battery duration depends on wireless mode, features and conditions. Microsoft has not established every real-world endurance result in the launch announcement, so editors should wait for independent testing before making precise claims. The programmable Action Button could reduce menu navigation for popular tasks, but users should verify exactly which shortcuts are available in supported software. Standard inputs may preserve familiar gameplay while smaller thumbstick travel or grip could affect precision; these are review questions, not proven flaws.
Is $49.99 good value?
Value depends on the buyer’s existing devices, preferred games and ergonomics. Someone who already owns a comfortable full-size controller may gain portability without needing to replace their main controller. A family seeking a second or third controller may prioritize price and consistent wireless pairing. A competitive player might instead favor adjustable controls, wired latency or premium hardware that the Nano does not claim to provide. Compare after-sales warranty, charging accessory costs, import taxes, local support and return rules. The launch is best understood as a compact mainstream option, not a universal upgrade from every other Xbox controller.
Worked example: how to interpret a difficult headline
Two buyers can reach different conclusions at the same price: a traveler wanting a lightweight Bluetooth controller may value the smaller form factor, while someone who plays long racing sessions on a console may prefer a larger grip. A useful review explains this trade-off rather than ranking products solely by price or feature count. Check a local store’s return policy in case the fit is unsuitable. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Official Xbox Nano | Small, $49.99 list price, rechargeable and portable. |
| Full-size standard controller | Potentially different hand fit and battery arrangements. |
| Premium controller | May add advanced customization at a higher price. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- November 2026 retail availability and regional pricing.
- Independent battery-life and ergonomic testing.
- Compatibility changes via software updates.
- Store returns, warranty and accessory requirements.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
Specifications make the Nano controller appealing, but personal hand fit, device compatibility, charging accessories, and return policy determine its value. The editorial differentiator is a use-case comparison rather than a copied feature list or an unsupported claim about measured latency.
Frequently asked questions
What is the Xbox Nano price?
Microsoft lists $49.99 USD before location-specific taxes and differences. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
When does Xbox Nano launch?
Microsoft describes November 2026 availability, with a specific November 4 date on its US store listing. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it have all the standard buttons?
Microsoft says it includes 18 standard gameplay inputs. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it work on PC and phones?
It supports Bluetooth on compatible devices; verify software and game compatibility. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
AI
PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand
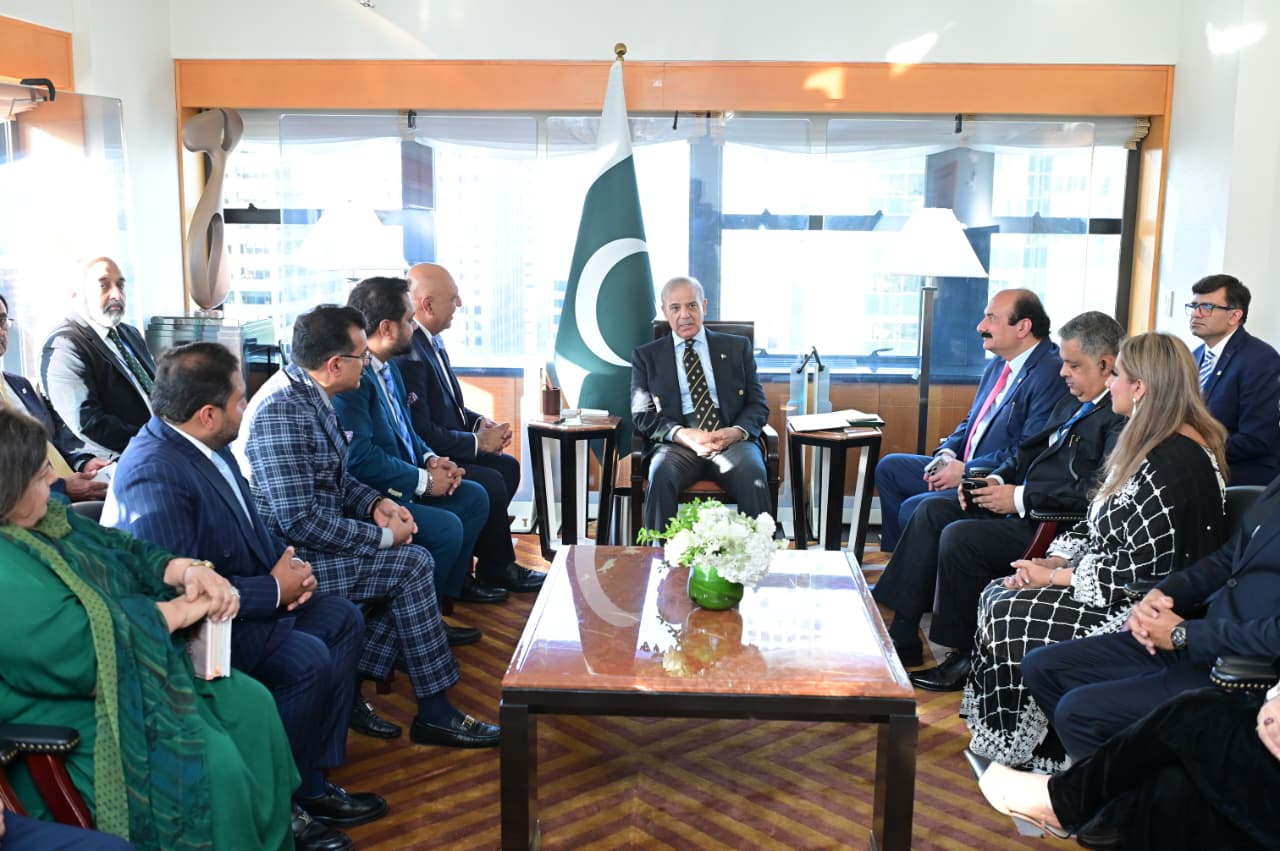
NEW YORK, September 24, 2026 — Prime Minister Muhammad Shehbaz Sharif has invited Pakistani business leaders and professionals based in the United States to invest in Pakistan, highlighting government measures aimed at improving the business environment and encouraging investment.
The invitation came during meetings with Pakistani-American business personalities and professionals working across information technology, artificial intelligence, automobiles, energy, construction and other sectors.
According to the Associated Press of Pakistan (APP), the prime minister said the government was working to create a conducive environment for investment and business activity. He also pointed to reforms at the Federal Board of Revenue (FBR) and measures intended to promote innovation in agriculture.
But the latest appeal to the Pakistani-American business community comes against a broader backdrop: Pakistan is seeking to attract more private investment, expand exports and turn improving macroeconomic conditions into sustained economic activity.
Why Pakistani-American Investors Are Being Targeted
The Pakistani diaspora represents an important source of capital, business expertise and international commercial connections.
Pakistan’s remittance flows demonstrate the economic significance of its overseas population. World Bank data show that Pakistan received approximately $40.48 billion in personal remittances in 2025, equivalent to around 9.9% of GDP.
The State Bank of Pakistan also reported workers’ remittances of approximately $3.66 billion in August 2026, with the monthly series showing substantial inflows throughout 2026.
Investment, however, differs from remittances: it involves deploying capital into businesses, projects or financial assets with the expectation of returns. That distinction makes the government’s effort to attract diaspora entrepreneurs particularly relevant.
IT and AI Among the Sectors in Focus
The technology sector is one of the most significant areas highlighted by the government.
The September 24 meeting included Pakistani-American professionals associated with IT and artificial intelligence, alongside representatives from traditional sectors such as automobiles, energy and construction.
Pakistan’s broader investment framework identifies services, including IT and telecommunications, as areas open to foreign investment. The Board of Investment says Pakistan maintains a liberal investment regime and has mechanisms designed to facilitate local and foreign investors.
For Pakistani-American technology entrepreneurs, potential areas include:
- Software and SaaS businesses
- Artificial intelligence
- IT-enabled services
- Fintech
- Digital infrastructure
- Business-process outsourcing
- Export-oriented technology companies
- Technology startups and venture investment
The attraction for diaspora entrepreneurs is not necessarily limited to providing capital. Entrepreneurs with operations in the United States can potentially bring technology, management expertise, international customers, investment networks and access to global markets.
Agriculture Is Another Priority
Agriculture was also specifically mentioned during the prime minister’s meetings.
APP reported that Shehbaz Sharif said the government was taking measures to promote innovation in agriculture.
That creates potential investment themes around:
- Agri-processing
- Agricultural technology
- Cold-chain infrastructure
- Food processing
- Irrigation technology
- Storage and logistics
- Export-oriented agriculture
- Livestock and dairy
- Farm mechanization
For investors, the distinction between producing agricultural commodities and investing in higher-value processing and supply-chain infrastructure can be particularly important because value-added businesses can connect domestic production with international markets.
What Pakistan’s Investment Framework Offers Foreign Investors
Pakistan’s Board of Investment states that the country follows a liberal investment regime and that its mandate includes promoting, encouraging and facilitating both local and foreign investment.
The Board’s investment information also states that foreign investors can have 100% equity ownership in many areas, although restrictions or specific rules apply to certain sectors.
The government’s Investment Policy 2023 also emphasizes investor protection, investment promotion and expanding Pakistan’s investment-promotion presence abroad, including in the United States.
That policy framework provides important context for the prime minister’s latest appeal to Pakistani-American businesses.
Pakistan Has Also Introduced a New Long-Term Residency Route for Investors
Another development relevant to international investors is Pakistan’s Long-Term Residency (LTR) framework.
According to the Board of Investment, the Foreigners (Long Term Residency) Order, 2025 created a residency-by-investment framework offering five-, seven- and ten-year residency options, subject to eligibility and investment requirements. The BOI says the minimum investment requirement is $50,000, to be materialized within one year through authorized banking channels.
The scheme is separate from the government’s broader investment-promotion policies, but it illustrates the effort to create additional mechanisms for attracting international capital and entrepreneurs.
The U.S.-Pakistan Economic Relationship Adds Another Layer
The appeal to Pakistani-American businesses also comes while economic engagement between Pakistan and the United States remains an important part of Pakistan’s external economic strategy.
In July 2026, Reuters reported that Pakistan had requested a proposed $10 billion U.S. exchange stabilization facility, while discussions were also taking place with U.S. financial institutions including the Export-Import Bank and the U.S. International Development Finance Corporation.
More recently, Reuters reported that Pakistan expected a decision from the United States on the proposed facility while continuing discussions with U.S. EXIM Bank and the Development Finance Corporation on potential projects.
These developments concern government-to-government and institutional financing rather than Pakistani-American private investment, but together they illustrate the wider economic relationship in which the latest business-community outreach is taking place.
What the Government Says About Investment Facilitation
Pakistan’s Board of Investment describes itself as the interface between international and domestic investors and the public and private sectors. Its investment regime information highlights measures intended to reduce the cost and procedural burden of doing business and to facilitate investment.
The government has also continued promoting the Special Investment Facilitation Council and other mechanisms intended to streamline investment processes.
For an investor considering Pakistan, however, the existence of an investment framework does not remove the need for sector-specific due diligence, regulatory approvals, taxation analysis, foreign-exchange considerations and commercial risk assessment.
What Pakistani-American Investors Should Examine Before Investing
The prime minister’s invitation is a political and economic call for greater investment, but prospective investors still need to evaluate individual opportunities on their own merits.
Key issues include:
1. Regulatory requirements
Investment rules differ according to the sector. The BOI notes that some industries are subject to specific restrictions or approvals.
2. Ownership structure
Foreign ownership can reach 100% in many sectors, but exceptions exist, making a sector-specific review necessary before establishing a company.
3. Profit and capital repatriation
Pakistan’s investment framework provides mechanisms for foreign investors to repatriate eligible profits, dividends and investment proceeds, subject to applicable foreign-exchange procedures.
4. Taxation
Investors should examine federal and provincial taxes, withholding obligations, customs duties and sector-specific incentives before committing capital.
5. Infrastructure and operating costs
An attractive investment proposition depends not only on headline incentives but also on electricity, logistics, labor, financing, connectivity and supply-chain costs.
6. Exit strategy
Investors should establish how capital can be repatriated, shares transferred and profits distributed before entering the market.
Pakistan’s Investment Push Extends Beyond the United States
The latest initiative is part of a wider effort to attract overseas Pakistani capital.
Earlier in September 2026, Economic Affairs Minister Ahad Cheema directed officials to develop a structured mechanism through which overseas Pakistanis could participate in viable infrastructure projects, including potential opportunities involving railways, highways, power, civic infrastructure and airports.
In July, Planning Minister Ahsan Iqbal also invited Pakistani-American entrepreneurs, technologists and financiers in Chicago to bring capital, expertise and global networks to Pakistan’s economic development.
This indicates that the September 24 appeal is not an isolated announcement but part of a broader government effort to engage overseas Pakistanis and international investors.
The Bigger Question: Can Investment Follow the Outreach?
The government’s challenge is to convert investment invitations into bankable projects and completed investments.
That requires more than announcements. Investors typically assess regulatory predictability, taxation, currency convertibility, infrastructure, security, financing costs, market size, contract enforcement and the ability to repatriate returns.
The U.S. State Department’s investment-climate assessment has previously identified challenges in Pakistan including regulatory complexity, intellectual-property concerns, changing taxation policies and security-related investor concerns. At the same time, it noted that U.S. companies operate profitably in several Pakistani sectors and that there are no restrictions specifically targeting U.S. investors.
That combination—investment opportunity alongside identifiable investment risks—is important context when assessing the latest government outreach.
What Comes Next for Pakistani-American Investment
Prime Minister Shehbaz Sharif’s September 24 appeal places Pakistani-American businesses at the center of Pakistan’s effort to attract additional investment.
The sectors discussed—AI, IT, energy, automobiles, construction and agriculture—cover both emerging technologies and established parts of the economy.
Pakistan’s investment framework, expanding diaspora-focused initiatives and continuing U.S.-Pakistan economic engagement could provide additional channels for investment. However, the eventual impact will depend on whether proposed opportunities develop into commercially viable projects and whether investors find the regulatory and economic environment sufficiently predictable.
For Pakistani-American entrepreneurs, the latest message from Islamabad is therefore straightforward: the government wants greater diaspora participation not only through remittances, but also through entrepreneurship, capital, technology and long-term investment.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
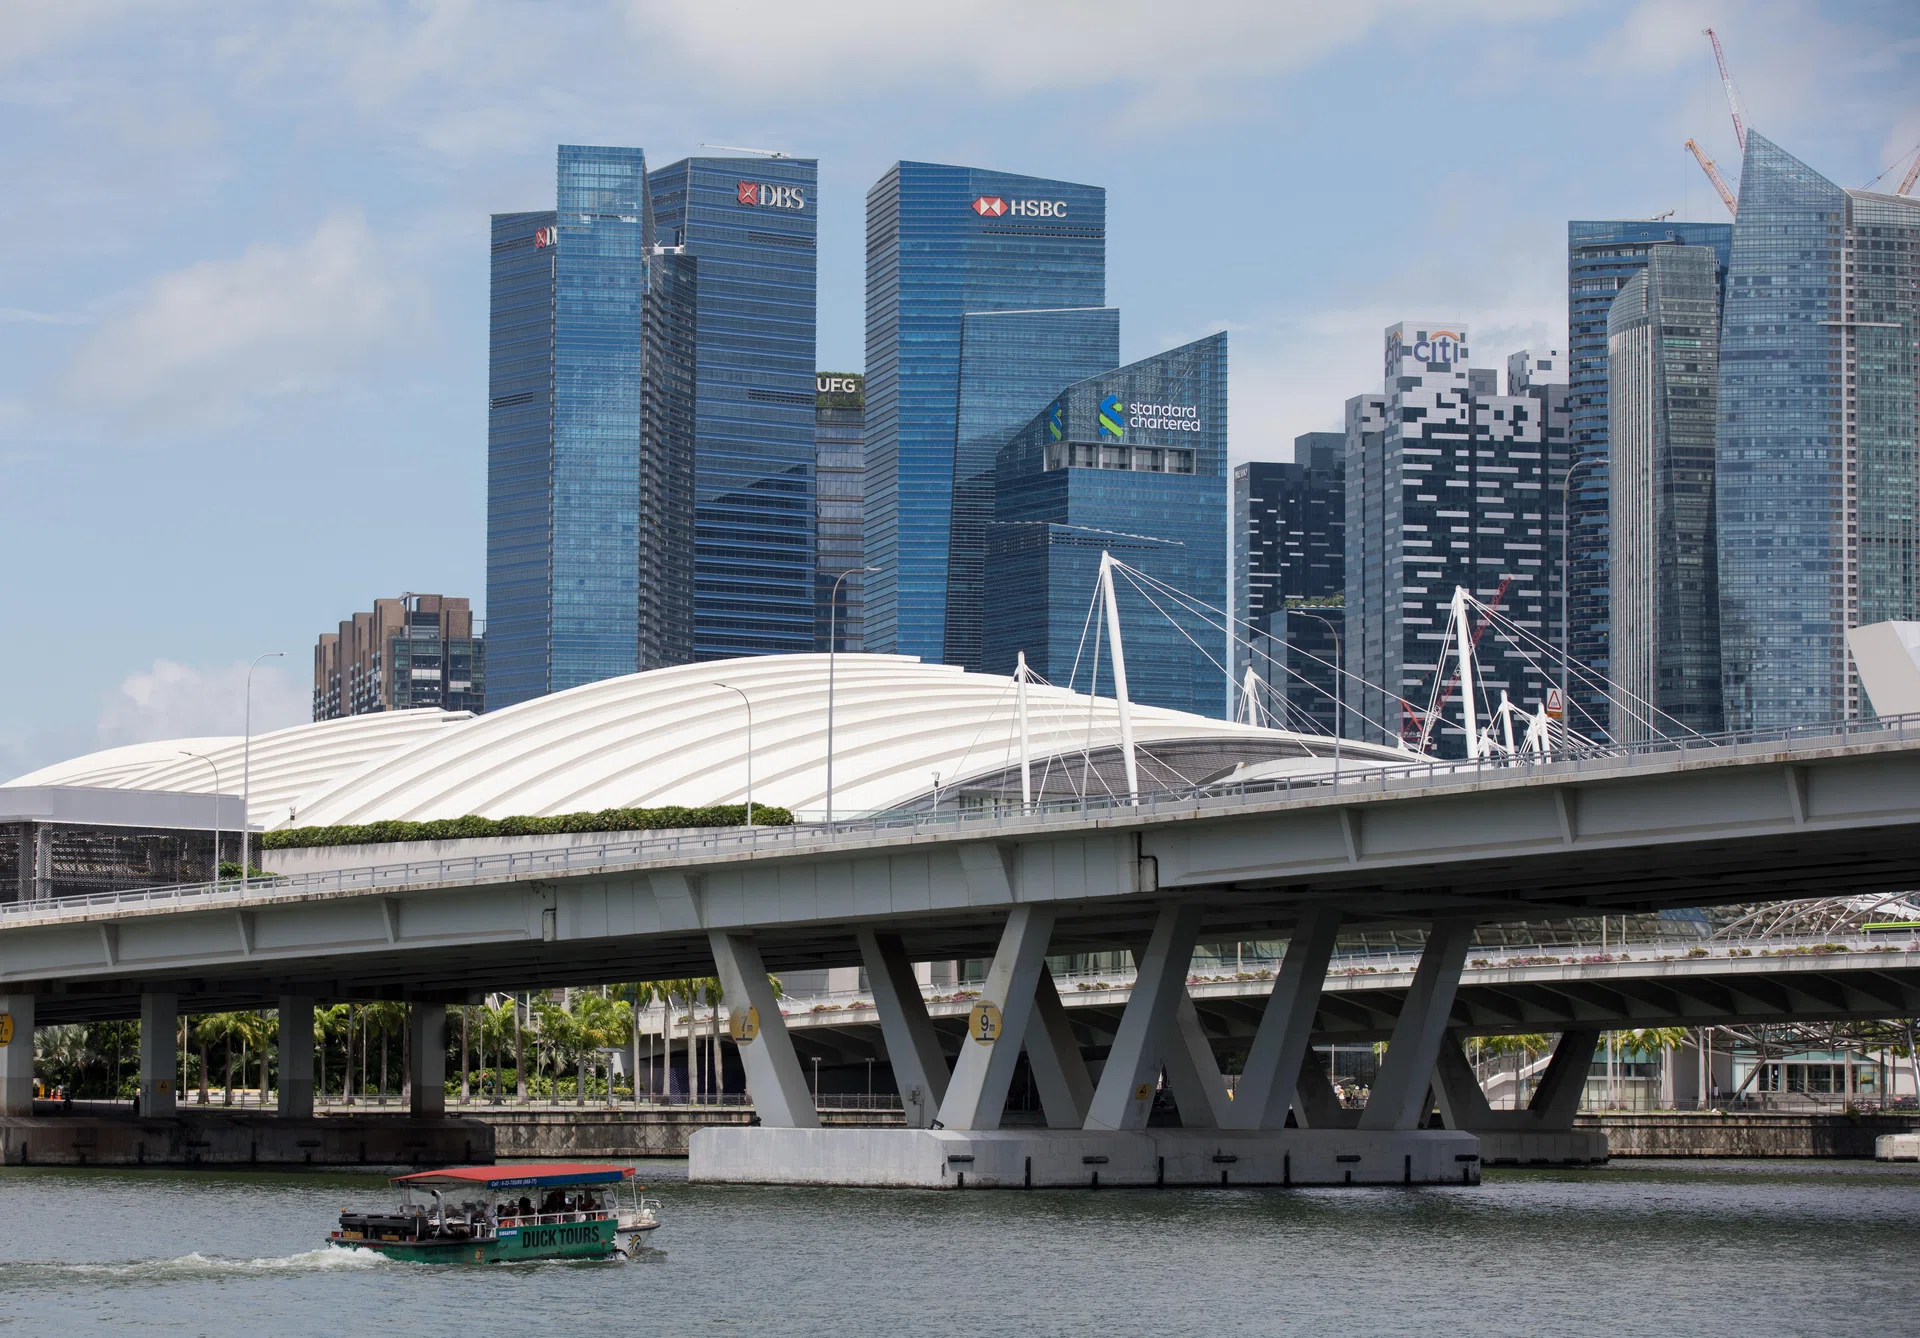
Singapore’s economy delivered a genuine surprise heading into the second half of 2026: Q1 GDP growth came in at 6.0% year-on-year, comfortably beating flash estimates of 4.6% and marking the strongest quarterly growth since Q3 2024 (Joey Choy Newsletter). That’s a substantial beat — not a rounding error — and it deserves more scrutiny than the celebratory framing it’s mostly received.
What Actually Drove the Beat
The growth was broad-based rather than concentrated in a single sector, which is itself a meaningfully positive signal. Construction output picked up, the services sector expanded faster than expected — led specifically by wholesale and retail trade, accommodation, and finance and insurance — while manufacturing held up reasonably well despite slower underlying momentum (Joey Choy Newsletter).
The Curious Gap Nobody’s Fully Explaining
Here’s the detail that deserves far more scrutiny than it’s getting: despite this substantial first-quarter beat, Singapore’s Ministry of Trade and Industry has maintained its full-year 2026 GDP growth forecast at a relatively modest 2.0% to 4.0% range (Singstat / Business Times, cited in Joey Choy Newsletter).
That’s a genuinely unusual pattern. A 6.0% first-quarter print against a full-year forecast ceiling of 4.0% implies MTI is either expecting a meaningfully sharp deceleration through the remaining three quarters, or is being deliberately conservative in its official guidance — perhaps to preserve policy flexibility given ongoing global trade uncertainty, tariff risk, and the broader geopolitical volatility still working through the Middle East conflict’s aftermath. Coverage celebrating the Q1 beat has largely glossed over this tension rather than interrogating it, which is precisely the kind of gap a sharper competitive analysis piece should fill.
The Economic Strategy Review: Singapore’s Long-Game Positioning
Running alongside the growth numbers, Singapore released the Final Report of its Economic Strategy Review, offering more detailed proposals for the country’s longer-term economic direction (Business Times, cited in Joey Choy Newsletter). While the specific policy contents of that review extend beyond what’s captured in available reporting, its timing alongside a growth beat and unchanged full-year guidance suggests Singapore’s policymakers are focused on structural, multi-year positioning rather than reacting to any single quarter’s data — consistent with the country’s historical approach to economic planning.
Singapore Airlines: A Microcosm of the Broader Margin Story
One specific corporate data point illustrates a pattern worth watching across Singapore’s broader economy: Singapore Airlines reported full-year FY2026 revenue of S$20.5 billion, up 5.0% from the prior year and beating analyst revenue estimates by 2.2%, with earnings per share surpassing estimates by 9.4%. Yet net income declined 57% to S$1.18 billion, driven by higher expenses, and profit margin fell sharply to 5.8% from 14% in FY2025 (Joey Choy Newsletter).
That’s a genuinely instructive pattern: revenue growth remaining resilient while margins compress sharply due to elevated costs — plausibly linked to the same energy price volatility and broader input-cost pressures affecting economies globally through 2026. Despite the profit decline, SIA still declared a final dividend of S$0.29 per share, covered at a 70% payout ratio on earnings and a 36% cash payout ratio, translating to a dividend yield of approximately 5.8% — a signal that management retains confidence in the underlying cash generation capacity of the business even amid margin pressure.
Why This Matters Beyond Singapore’s Borders
Singapore’s economic performance functions as a genuinely useful bellwether for the broader Southeast Asian and global trade environment, given the city-state’s outsized role as a regional financial hub, trade entrepôt, and — as detailed in the parallel Johor-Singapore Special Economic Zone story — an increasingly important node in the global AI infrastructure buildout through its role funneling data centre investment into neighboring Johor.
A services-led, broad-based Q1 growth beat, occurring even as the Middle East conflict’s energy price volatility and US tariff uncertainty weighed on global sentiment, suggests underlying Southeast Asian demand may be more resilient than headline global risk narratives suggest — though the unusually cautious full-year MTI forecast is a meaningful counter-signal worth taking seriously rather than dismissing.
What Investors and Businesses Should Watch Next
The practical signals worth tracking through the remainder of 2026: whether Q2 and Q3 GDP prints show the sharp deceleration implicit in MTI’s unchanged full-year forecast range, or whether the ministry revises its guidance upward as subsequent quarters confirm the Q1 strength wasn’t a one-off; whether services-sector momentum (wholesale/retail trade, finance and insurance specifically) proves durable or was partly boosted by one-off factors; and whether corporate margin compression, visible clearly in Singapore Airlines’ results, is broadening across other Singapore-listed companies as a signal of economy-wide cost pressure rather than an airline-specific story tied to fuel costs.
The Bottom Line
Singapore’s 6.0% Q1 GDP print is a genuine, broad-based positive surprise that deserves recognition — but the striking gap between that result and the Ministry of Trade and Industry’s unchanged, far more conservative full-year forecast is the more interesting and underexplored story. Either Singapore’s policymakers are bracing for a meaningful slowdown through the rest of 2026 that hasn’t been fully explained publicly, or official guidance is running deliberately behind the data as a hedge against global uncertainty. Investors and businesses positioning around Singapore’s growth trajectory should watch which of those two explanations proves correct over the next two quarters, rather than extrapolating the Q1 beat forward uncritically.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

Bitcoin ETF Outflows: Has Institutional Demand Really Turned?

Xbox Nano Controller 2026: $49.99 Price, Features, November Release

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know

How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)

CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]

IPhone 18 Pro Specifications, Pricing, and Thermal Architecture Leaks Analyzed
Xbox Nano Controller 2026: $49.99 Price, Features, November Release
Bitcoin ETF Outflows: Has Institutional Demand Really Turned?
-
Digital6 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital5 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China5 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools