Analysis
A Theory of Elon Musk’s Maniacal Drive

Introduction
Elon Musk, the enigmatic entrepreneur, inventor, and CEO of multiple groundbreaking companies, has captivated the world with his relentless drive and audacious vision. From Tesla’s electric cars to SpaceX’s ambitious goal of colonizing Mars, Musk’s ventures have redefined industries and challenged conventional thinking. But what fuels this maniacal drive that sets him apart from his contemporaries? In this blog post, we will delve deep into the psyche of Elon Musk to explore the theory behind his insatiable ambition and relentless pursuit of innovation.
The Genesis of Elon Musk’s Ambition
To understand the origins of Musk’s drive, we must first look at his upbringing and early experiences. Born in Pretoria, South Africa, in 1971, Musk’s childhood was marked by curiosity and a voracious appetite for knowledge. He was an avid reader, devouring science fiction novels and books on engineering and physics, which undoubtedly fueled his imagination.
Musk’s parents divorced when he was young, and he developed a close bond with his father, Errol Musk, an electromechanical engineer. It was through this relationship that Musk gained early exposure to engineering concepts and technology. These formative years, spent exploring the world of electronics and mechanics, laid the foundation for his future endeavours.

The PayPal Windfall
Elon Musk’s journey as an entrepreneur began with Zip2, an online business directory he co-founded in 1996. The sale of Zip2 in 1999 brought him his first significant financial success. However, it was his involvement in the creation of PayPal that truly catapulted him into the ranks of Silicon Valley’s elite.
In 2002, PayPal was acquired by eBay for $1.5 billion in stock. Musk’s share of the proceeds amounted to approximately $165 million. This massive windfall provided him with the financial means to pursue his grand ambitions, and it marked a pivotal moment in his career.
The PayPal sale not only gave Musk the resources he needed but also a taste of the impact he could have on the world through technology and innovation. It was a glimpse of what lay ahead, and he was determined to make the most of it.
Visionary Ventures
With his newfound wealth, Elon Musk embarked on a journey that would see him establish some of the most groundbreaking companies of the 21st century. Here, we’ll explore Musk’s ventures and the driving forces behind each of them:
- Tesla, Inc.: In 2004, Musk co-founded Tesla Motors (now Tesla, Inc.) with a mission to accelerate the world’s transition to sustainable energy. His relentless pursuit of electric vehicles (EVs) as a solution to climate change and fossil fuel dependence stemmed from his concern for the environment and a desire to disrupt the automotive industry. Musk’s commitment to innovation in battery technology and EV design has made Tesla a global leader in the electric car market.
- The Drive Factor: Musk’s drive in the electric vehicle sector is rooted in a deep sense of responsibility toward the planet’s future. He envisions a world where sustainable energy sources replace fossil fuels, and he’s determined to make that future a reality.
- SpaceX: In 2002, Musk founded SpaceX with the goal of reducing the cost of space exploration and making it possible for humans to colonize Mars. SpaceX has achieved numerous milestones, including the first privately funded spacecraft to reach orbit and the development of the reusable Falcon 9 rocket.
- The Drive Factor: Musk’s obsession with space exploration is driven by a belief that humanity should become a multi-planetary species to ensure our survival. His desire to establish a human presence on Mars is a testament to his audacious ambition and long-term thinking.
- SolarCity (Now Tesla Solar): Musk’s vision for a sustainable future extended beyond electric cars. In 2006, he co-founded SolarCity (now part of Tesla) to accelerate the adoption of solar energy. By providing solar panels and energy storage solutions, Musk aimed to reduce the world’s reliance on fossil fuels for electricity.
- The Drive Factor: Musk’s drive in the renewable energy sector is tied to his conviction that transitioning to clean, renewable energy sources is essential to combat climate change and create a more sustainable world.
- Neuralink: In 2016, Musk founded Neuralink, a neurotechnology company focused on developing brain-computer interfaces. The aim is to merge the human brain with artificial intelligence (AI) to enhance cognitive abilities and potentially address neurological conditions.
- The Drive Factor: Musk’s involvement in Neuralink stems from his concerns about the existential risks posed by AI and his belief that merging with AI is a way for humanity to remain relevant in an increasingly AI-driven world.
- The Boring Company: Musk founded The Boring Company in 2016, with the goal of revolutionizing tunnel construction and transportation. The company’s projects include high-speed underground transportation systems (e.g., the Hyperloop) and urban tunnel networks.
- The Drive Factor: Musk’s motivation for The Boring Company is rooted in his frustration with traffic congestion and a desire to improve urban transportation. His commitment to solving such seemingly intractable problems showcases his persistence and innovative thinking.
Driving Forces Behind Musk’s Maniacal Ambition
Elon Musk’s maniacal drive can be attributed to several key factors:
- Mission-Driven Leadership: Musk’s ventures are fueled by missions that transcend profit motives. He sees himself as a catalyst for positive change in the world, whether it’s reducing carbon emissions, enabling space exploration, or advancing neurotechnology. This sense of purpose drives him relentlessly.
- Risk-Taking: Musk is not afraid to take enormous risks, both personally and financially. He invested nearly all his wealth in SpaceX and Tesla, even when both companies faced existential threats. This willingness to risk it all is a testament to his unwavering commitment to his visions.
- Long-Term Vision: Musk thinks in terms of decades and centuries, not just quarters or years. His focus on long-term goals allows him to overcome short-term setbacks and persevere in the face of adversity.
- Relentless Work Ethic: Musk is known for his grueling work schedule, often putting in 80-100 hour weeks. His dedication to his companies and projects is unmatched, and he leads by example, expecting the same level of commitment from his teams.
- Fearlessness in the Face of Failure: Musk has faced numerous failures and setbacks throughout his career, from rocket explosions to production delays. Yet, he views failure as a stepping stone to success and remains undeterred by it.
- Innovation and Disruption: Musk’s drive is fueled by a desire to disrupt industries and challenge the status quo. He thrives on pushing the boundaries of what’s possible and is relentless in his pursuit of innovation.
Conclusion
Elon Musk’s maniacal drive is a complex interplay of his upbringing, early experiences, and unwavering commitment to missions that go beyond personal gain. His relentless pursuit of ambitious goals has not only revolutionized multiple industries but has also inspired countless individuals to think bigger and bolder.
Musk’s legacy extends far beyond the companies he’s founded; it’s a testament to the power of vision, determination, and a refusal to accept the limitations of the status quo. As we look to the future, Elon Musk serves as a reminder that the world needs more dreamers and doers who are willing to take risks, challenge convention, and strive for greatness.
In the end, Elon Musk’s maniacal drive isn’t just about success; it’s about changing the world, one audacious idea at a time.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.


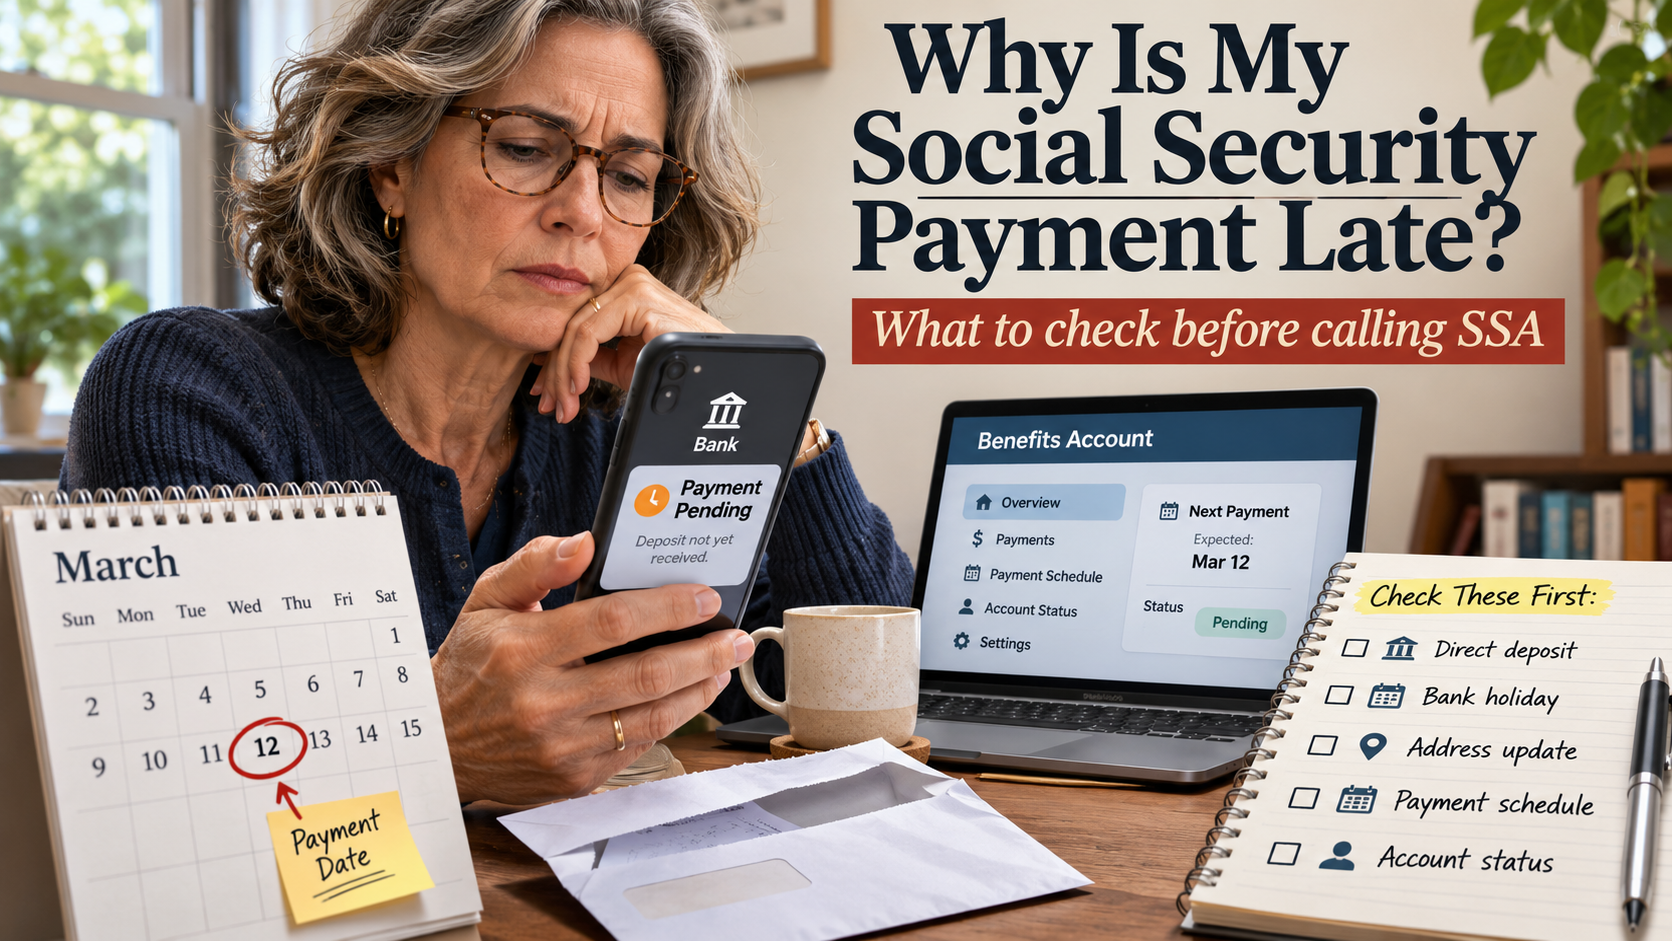
Quick answer: If your Social Security or SSI deposit has not appeared, first confirm the scheduled payment date for your program, then check with your bank or financial institution. The Social Security Administration’s missing-payment FAQ specifically says to contact your bank first for an electronic payment that does not arrive as scheduled. If the money remains missing, call SSA at 1-800-772-1213 or contact a local Social Security office. Do not pay a third party to ‘release’ your benefits.
A delayed deposit can be frightening when it is meant to cover rent, food, medicine or electricity. But the timing problem may have several explanations, and not all mean that the government has stopped the benefit. The most useful response is to determine whether the payment is not yet due, issued but not posted, sent to the wrong account, withheld after an eligibility change, or truly missing. Those categories lead to different next steps.
Step one: make sure today is really your payment date
The most common source of confusion is assuming every Social Security recipient is paid on the third of the month. In reality, the SSA’s published payment rules place most retirement, disability and survivor beneficiaries on one of three Wednesdays, generally based on the relevant birth-date category. Certain people who started benefits before May 1997, and some who receive SSI and Social Security together, have special schedules.
| Recipient category | Ordinary schedule | What to verify |
|---|---|---|
| SSI | First of the month, adjusted for weekends/holidays | Benefit month versus bank deposit date |
| Certain long-standing or dual beneficiaries | Third of the month, subject to adjustments | Whether your award follows the special cycle |
| Regular Social Security, birth date 1–10 | Second Wednesday | Holiday shifts and relevant birth date |
| Regular Social Security, birth date 11–20 | Third Wednesday | Correct calendar month |
| Regular Social Security, birth date 21–31 | Fourth Wednesday | Correct calendar month |
Consult the official benefit calendar rather than a social-media image. A chart that mechanically copies weekday patterns without considering federal holidays can misstate a particular month’s deposit date. For example, the first November 2026 Wednesday cohort was scheduled for November 10 rather than Veterans Day, November 11, under SSA’s holiday adjustment.
Step two: check holiday and weekend adjustments
When a normal payment date falls on a weekend or legal public holiday, Social Security generally issues the payment on the preceding business day. The agency’s holiday FAQ explains the principle. Consequently, a payment may show up earlier than a generic calendar suggests rather than later.
The November 2026 SSI example is instructive. Because November 1 fell on a Sunday, the SSI payment for the November benefit month was scheduled for October 30. Someone searching the bank statement only for a transaction dated November might think a payment is missing even though it arrived at the end of October. That is a question of benefit month versus calendar posting date, not necessarily entitlement.
Different banks may display transaction descriptions and posting times differently. A pending payment, an available balance and a settled transaction are not always the same entry. Use the statement details, not a push notification alone, when checking whether money arrived.
Step three: ask your bank whether a payment was received
SSA’s official advice is clear: if an electronic payment did not arrive on its scheduled date, contact your bank or financial institution first. The institution may be experiencing a delay in posting a deposit it has received. Ask whether there is a pending government benefit payment, whether there is a hold or account problem, and whether the institution has returned a transaction.
It helps to have the scheduled pay date and the last successful benefit transaction on hand. Do not assume the bank can reveal confidential SSA processing information; the bank can explain what its own systems show. If the bank sees no payment, tell SSA that you have already checked. This avoids repeatedly being sent back to the same first troubleshooting step.
If your bank account was recently closed or changed, the payment could have been rejected or returned. The SSA direct-deposit update FAQ describes how recipients can update relevant information, with different options for Social Security versus SSI. Never email complete bank details to an unsolicited address or disclose credentials to someone who calls unexpectedly.
Step four: use SSA’s official missing-payment reporting channel
If the bank cannot resolve the problem and the money is genuinely missing, contact the Social Security Administration. The missing-payment FAQ gives the number 1-800-772-1213 and the TTY line 1-800-325-0778, along with the option to contact a local office. SSA says it will review a qualifying missing-payment report and replace payment if it is due.
When contacting the agency, prepare the benefit type, scheduled pay date, the payment amount you expected, a brief description of what the bank told you and whether you changed accounts. You may need to verify your identity through an official process. The purpose is to give the representative enough information to investigate without sharing sensitive details through insecure channels.
A key distinction is between a payment the agency issued but you did not receive and a payment the agency has not authorized because of a change in eligibility or other adjudicated matter. The remedy for an issued-and-lost deposit is not necessarily the same as the appeal or correction process for a change in benefits.
What if my benefit amount changed rather than disappeared?
A smaller payment can feel like a missing payment when you budget a fixed amount. But Social Security deposits can reflect Medicare premium deductions, tax withholding, repayment of overpayments, adjustments to benefits and other legally applicable changes. SSI payments can also change with income, resources or living arrangements.
Check your most recent award or adjustment notice in your secure my Social Security account if your benefit type permits the relevant online service. Compare the gross entitlement with the net bank deposit. If the gross benefit has changed, ask what notice or determination supports the new amount. If only deductions changed, identify each one before assuming the benefit was reduced arbitrarily.
A person who receives both Social Security and SSI should check each benefit independently. For example, an increase in countable Social Security income may affect the SSI component under means-testing rules. Two deposits can move in different directions without there being a computer error. The SSA overview of SSI explains that income and living circumstances can change payment amounts.
What if the deposit goes to an old bank account?
Contact both your bank and SSA through verified channels. An account closure or change can cause a government deposit to be returned, which may require a reissue after the information is corrected. Do not assume transferring your ordinary paycheck to a new account also updates the Social Security benefit instructions.
The SSA’s direct deposit guidance notes that many retirement, survivors and disability recipients can use their personal online account to change banking information. The same online self-service functionality is not available for all SSI users, who may need to call or visit an office. That difference matters if an article promises one-click bank changes to everyone.
Before submitting a change, review the routing and account number carefully on a legitimate banking document. A single incorrect digit can cause a failure that takes time to investigate. If someone pressures you to reroute a benefit into an account that is not yours, treat that as a fraud warning and contact SSA directly.
How long should I wait before reporting a late payment?
The practical answer is: follow the agency’s current missing-payment instructions. The SSA FAQ asks electronic-payment recipients to contact their bank on the scheduled date if the payment is missing, then reach SSA if necessary. It does not instruct everyone to wait an arbitrary three or five business days before making any inquiry. If a new claim is involved, different processing and notification timelines may apply.
If the missing payment creates urgent hardship, explain that when you contact the agency. An inquiry may not produce an immediate replacement, but a clear description helps the agency understand the consequences. Seek local emergency assistance if you cannot obtain essentials while the problem is investigated; do not turn to a supposed ‘SSA release fee’ offered by a stranger.
Can scams look like payment problems?
Yes. Fraudsters often use worries about a missing deposit to lure victims into clicking links or revealing identification numbers, one-time passcodes and bank details. They may falsely claim a payment is frozen pending a small fee. Official government sites, including SSA’s account portal, should be accessed by typing the address directly or using a saved trusted bookmark.
SSA does not require you to pay a social-media account or intermediary to speed up a routine missing-payment report. Avoid handing over your entire banking login to anyone promising a quicker resolution. Preserve screenshots of suspicious messages if you need to report them, but do not forward sensitive attachments to unknown addresses.
A payment-troubleshooting checklist
Before making the call, write down these five answers: (1) Which program pays you? (2) What is the scheduled date according to SSA? (3) Did the calendar move that date because of a holiday? (4) What does your bank show? (5) Has your address, account or benefit entitlement changed? The sequence stops a simple calendar adjustment from escalating into an unnecessary dispute, while making genuinely missing payments easier to explain.
Keep copies of formal notices and bank transaction entries, but redact sensitive personal numbers if seeking help from a third party. A caregiver assisting another person should also follow SSA’s authorization rules and avoid impersonating the beneficiary during an inquiry.
Frequently asked questions
Why has my Social Security payment not arrived today?
It may not be your scheduled date, the bank may not have posted the payment yet, or SSA may need to review a bank-account or entitlement issue. Verify the schedule, then contact the bank and SSA if needed.
Who should I call first for a missing direct deposit?
SSA’s FAQ recommends contacting the bank first, followed by SSA at 1-800-772-1213 if the problem remains unresolved.
Can SSI be paid in the previous month?
Yes. If the first falls on a weekend or holiday, the monthly SSI payment may arrive on the prior business day, as happened for November 2026.
Does a smaller deposit mean SSA stopped my benefits?
Not necessarily. A deduction or an eligibility-related adjustment can change the net payment. Review notices and distinguish the gross award from the deposited amount.
Can I change my direct deposit online?
Many retirement, survivors and disability beneficiaries can, but online options differ for SSI. Follow SSA’s official instructions.
Bottom line
When a Social Security payment seems late, a measured sequence is more effective than panic or rumors: confirm the official date, check the bank’s posting, inspect notices and then report the problem through SSA. A correct diagnosis protects both your household budget and your personal information. A missing deposit deserves prompt attention, but it should not be confused with a benefit that was issued on a different calendar date.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
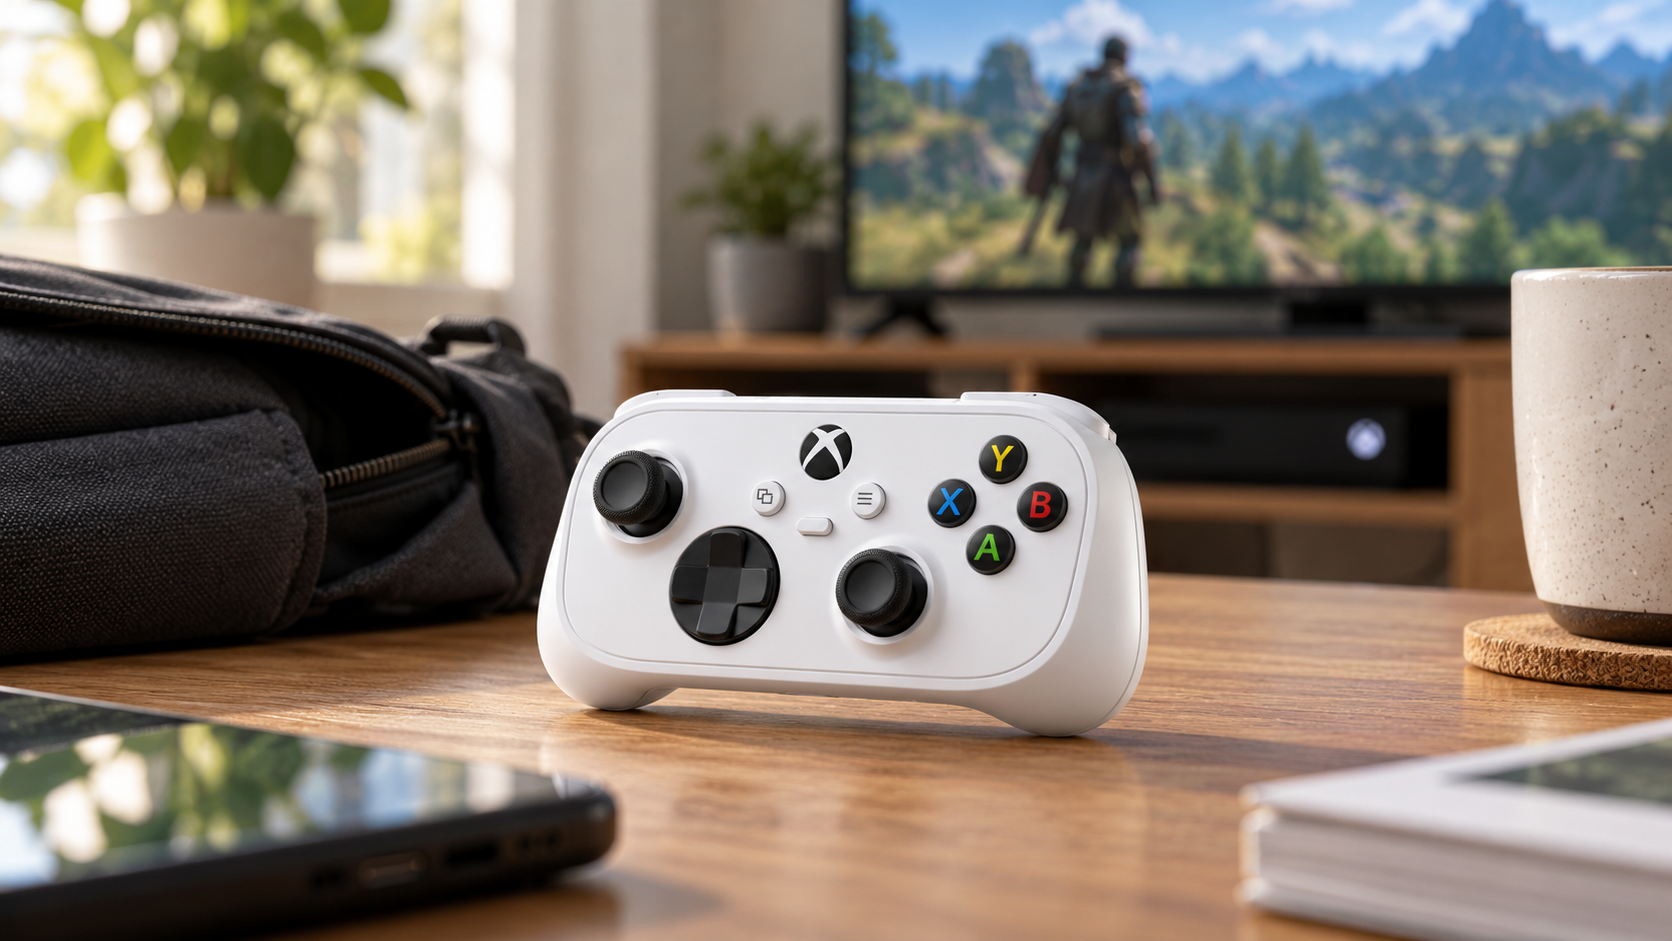
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. For primary-source background, consult Xbox Wire official announcement; Xbox official specification page; Microsoft Store US. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What Microsoft actually announced
The Xbox Wire announcement places the controller at a little over five inches long and approximately 3.5 ounces. Microsoft says it retains 18 standard gameplay inputs despite the smaller chassis. Its list price is $49.99 USD, though local prices and availability differ. It also reports a rechargeable internal battery and a programmable Action Button for tasks such as capturing screenshots or gameplay. This is a real official product launch, not a rumor based on leaked images. Product listings and availability should be checked for the buyer’s country.
Who benefits from a smaller controller
Small-hand ergonomics may be useful for some adults and younger players, but one size does not fit everyone. Grip diameter, shoulder-button reach, thumbstick placement and hand fatigue can matter more than weight alone. A tiny controller may be convenient in a bag but less comfortable during extended sessions for some users. A good review therefore evaluates real people with different hand sizes rather than calling compactness universally better. For parents, compatibility with age-appropriate games and device setup is part of the purchase decision. A low sticker price does not remove the need for usability testing.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026.
Wireless support and device compatibility
Microsoft says the Nano supports Xbox Wireless with compatible consoles and Bluetooth with supported PCs, mobile devices, tablets and smart TVs. That does not mean every game on every device is compatible. Operating-system support, cloud-play subscription availability and game-specific controller input differ. Players should inspect Microsoft’s compatibility notes before purchase, particularly for smart TVs or mobile games that require touch input. The internal battery uses USB-C charging, but the product page notes that the charging cable may be sold separately. Such minor accessories are relevant to total cost and should be visible in product comparisons.
Battery, Action Button and trade-offs
A built-in rechargeable battery changes ownership convenience compared with controllers that use replaceable cells, but it does not guarantee a particular play time. Battery duration depends on wireless mode, features and conditions. Microsoft has not established every real-world endurance result in the launch announcement, so editors should wait for independent testing before making precise claims. The programmable Action Button could reduce menu navigation for popular tasks, but users should verify exactly which shortcuts are available in supported software. Standard inputs may preserve familiar gameplay while smaller thumbstick travel or grip could affect precision; these are review questions, not proven flaws.
Is $49.99 good value?
Value depends on the buyer’s existing devices, preferred games and ergonomics. Someone who already owns a comfortable full-size controller may gain portability without needing to replace their main controller. A family seeking a second or third controller may prioritize price and consistent wireless pairing. A competitive player might instead favor adjustable controls, wired latency or premium hardware that the Nano does not claim to provide. Compare after-sales warranty, charging accessory costs, import taxes, local support and return rules. The launch is best understood as a compact mainstream option, not a universal upgrade from every other Xbox controller.
Worked example: how to interpret a difficult headline
Two buyers can reach different conclusions at the same price: a traveler wanting a lightweight Bluetooth controller may value the smaller form factor, while someone who plays long racing sessions on a console may prefer a larger grip. A useful review explains this trade-off rather than ranking products solely by price or feature count. Check a local store’s return policy in case the fit is unsuitable. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Official Xbox Nano | Small, $49.99 list price, rechargeable and portable. |
| Full-size standard controller | Potentially different hand fit and battery arrangements. |
| Premium controller | May add advanced customization at a higher price. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- November 2026 retail availability and regional pricing.
- Independent battery-life and ergonomic testing.
- Compatibility changes via software updates.
- Store returns, warranty and accessory requirements.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
Specifications make the Nano controller appealing, but personal hand fit, device compatibility, charging accessories, and return policy determine its value. The editorial differentiator is a use-case comparison rather than a copied feature list or an unsupported claim about measured latency.
Frequently asked questions
What is the Xbox Nano price?
Microsoft lists $49.99 USD before location-specific taxes and differences. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
When does Xbox Nano launch?
Microsoft describes November 2026 availability, with a specific November 4 date on its US store listing. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it have all the standard buttons?
Microsoft says it includes 18 standard gameplay inputs. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does it work on PC and phones?
It supports Bluetooth on compatible devices; verify software and game compatibility. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Microsoft officially introduced the Xbox Nano Controller on October 14, 2026. The compact controller is priced at $49.99 in the United States and is intended for people who want a lighter device, including users with smaller hands and players who carry a controller between locations. The company states it includes the standard 18 gameplay inputs, rechargeable battery, programmable Action Button, Xbox Wireless and Bluetooth connectivity.
A November 2026 launch is listed on Microsoft’s retail page. These are manufacturer specifications; independent comfort, latency and battery-life reviews still matter for a buying decision. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.
WASHINGTON — Newly disclosed federal financial records show that investment accounts belonging to President Donald Trump underwent an aggressive portfolio restructuring in July 2026, logging 1,156 individual securities transactions valued between $79 million and $270 million.
While headline attention has focused on multi-million-dollar sales of artificial intelligence and mega-cap tech leaders—including Microsoft, Amazon, and Meta Platforms—a comprehensive examination of the filings reveals a more complex strategy: a transition driven by automated index rebalancing, defensive fixed-income allocation, and concurrent dip-buying.
Executive Overview: July 2026 Disclosure Breakdown
According to analysis of official filings submitted to the U.S. Office of Government Ethics and reported by CNBC, total purchases across the eight managed accounts exceeded total sales.
| Category | Aggregate Value Range | Key Assets / Companies Involved |
| Total July Transactions | $79 Million – $270 Million | 1,156 total trades logged across 8 accounts |
| Total Purchases | $43.6 Million Minimum | Municipal bonds, short-term ETFs, Broadcom, Nvidia |
| Total Sales | $35.6 Million Minimum | Microsoft, Amazon, Oracle, Meta, Northrop Grumman |
| Primary Liquidation Event | July 20, 2026 | Multi-million dollar trims in $MSFT and$AMZN ($5M–$25M bracket each) |
| Quick Re-Entry Trades | July 23, 2026 | Modest buybacks in $MSFT ($100K–$250K) and$AMZN ($1K–$15K) |
Dissecting the Big Tech Trims: Algorithmic Rebalancing vs. Market Sentiment
The largest individual entries in the September filing occurred on July 20, 2026, when investment managers executed broad sell-offs in major cloud and AI infrastructure vendors.
As reported by Quartz, individual sell orders for Microsoft and Amazon each landed in the $5 million to $25 million filing bracket. Simultaneously, managers offloaded between $1 million and $5 million in Oracle stock, alongside position trims in Meta Platforms, Alphabet, and Nvidia.
However, reporting focused exclusively on liquidations misses the broader picture:
- Simultaneous Accumulation: On the very day managers sold Oracle, they added $500,000 to $1 million in Nvidia, while opening $1 million to $5 million positions in enterprise software giants like Salesforce, Intuit, and Marvell Technology.
- Immediate Re-entry: Just three days after the July 20 sell-off, the accounts repurchased positions in Microsoft ($100,001–$250,000 range) and Amazon ($1,001–$15,000 range).
- Fixed-Income Pivot: Significant capital was rotated into defensive yield assets, including the Vanguard Short-Term Bond Index ETF, State Street SPDR Bloomberg International Treasury Bond ETF, and local government bonds such as Miami-Dade County aviation paper.
Financial analysts noted in coverage by Livemint that these multi-directional trades mirror index-tracking models adjusting for market weightings rather than a deliberate directional bet on the tech sector.
White House Clarification: Automated Model Portfolios
Trading volume of this scale by a sitting U.S. president inevitably draws regulatory and public scrutiny. Addressing the disclosures, White House spokesperson Davis Ingle emphasized that the President maintains no personal involvement in daily trade execution.
“The President’s investment portfolio is managed by independent third-party financial institutions through automated model portfolios benchmarked to broad indices like the Schwab 1000,” White House officials stated. “Trading decisions are algorithmically executed without input, direction, or prior knowledge from the President or his family.”
Unlike past presidential administrations that placed assets into blind trusts or single-index mutual funds, the current arrangement relies on third-party wealth managers utilizing direct indexing models.
Regulatory Scrutiny and Geopolitical Overlap
Despite White House assurances, the timing of specific trades has drawn criticism from Capitol Hill.
On July 20, the same day managers sold $250,000 to $500,000 worth of defense contractor Northrop Grumman, President Trump signed an executive order tightening supply chain mandates for defense suppliers and restricting critical material sourcing from foreign nations.
According to government oversight documents cited by Bloomberg, congressional lawmakers—including Senator Elizabeth Warren—have submitted formal inquiries demanding full transparency regarding the identity of the third-party money managers overseeing the accounts to rule out insider conflicts of interest under U.S. Securities and Exchange Commission rules.
Key Takeaways for Market Observers
- Net Buyer Status: Despite headline sales in Big Tech, Trump’s accounts were overall net buyers in July, adding at least $43.6 million in assets.
- Broad Sector Diversification: Capital moved away from concentrated cloud computing mega-caps into short-duration fixed income, municipal bonds, and specialized semiconductor stocks.
- Systemic Model Management: The rapid buy-sell cycles (such as selling and repurchasing Microsoft within 72 hours) strongly align with algorithmic portfolio rebalancing rather than strategic macroeconomic forecasting.
Discover more from Startups Pro,Inc
Subscribe to get the latest posts sent to your email.

Why Is My Social Security Payment Late? What to Check Before Calling SSA

Bitcoin ETF Outflows: Has Institutional Demand Really Turned?

Xbox Nano Controller 2026: $49.99 Price, Features, November Release

PM Invites US-Based Pakistani Business Community to Invest in Pakistan as Investment Opportunities Expand

Trump Accounts Reshuffle Tens of Millions in Big Tech & AI Holdings

NIC Islamabad Launches Exclusive Acceleration Program with Up to PKR 5 Million Equity-Free Grant Support

World School Summit 2026 Malaysia: 41st Edition

Global Digital Trade Expo 2026: Dates, Schedule, Venue, Registration and Everything You Need to Know

How to Claim Your Sony PlayStation Store Credit Settlement (Up to $33.66)

CES 2027 Las Vegas: Registration Details, Dates and Venue [Ultimate Guide]
Xbox Nano Controller 2026: $49.99 Price, Features, November Release
Why Is My Social Security Payment Late? What to Check Before Calling SSA
Bitcoin ETF Outflows: Has Institutional Demand Really Turned?
-
Digital6 years ago
Social Media and polarization of society
-
Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Digital6 years ago
Karachi-based digital bookkeeping startup, CreditBook raises $1.5 million in seed funding
-
Kashmir6 years ago
Pakistan Mission Islamabad Celebrates “KASHMIRI SOLIDARITY DAY “
-
Digital6 years ago
WHATSAPP Privacy Concerns Affecting Public Data -MOIT&T Pakistan
-
News6 years ago
Dr . Arif Alvi visits the National Museum of Pakistan, Karachi
-
China6 years ago
TIKTOK’s global growth and expansion : a bubble or reality ?
-
Business5 years ago
Are You Ready to Start Your Own Business? 7 Tips and Decision-Making Tools